Telecommunications conglomerate AT&T (NYSE: T) announced better-than-expected revenue in Q3 2026, with sales up 5.3% year on year to $32.32 billion. Its GAAP profit of $0.12 per share was 80.6% below analysts’ consensus estimates.
Is now the time to buy AT&T? Find out by accessing our full research report, it’s free.
AT&T (T) Q3 2026 Highlights:
- Revenue: $32.32 billion vs analyst estimates of $31.67 billion (5.3% year-on-year growth, 2.1% beat)
- EPS (GAAP): $0.12 vs analyst expectations of $0.62 (80.6% miss)
- Operating Margin: 12.7%, down from 19.9% in the same quarter last year
- Free Cash Flow Margin: 16.9%, similar to the same quarter last year
- Market Capitalization: $160.5 billion
Company Overview
Founded by Alexander Graham Bell, AT&T (NYSE: T) is a multinational telecomm conglomerate providing a range of communications and internet services.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, AT&T struggled to consistently increase demand as its $128.9 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of poor business quality.
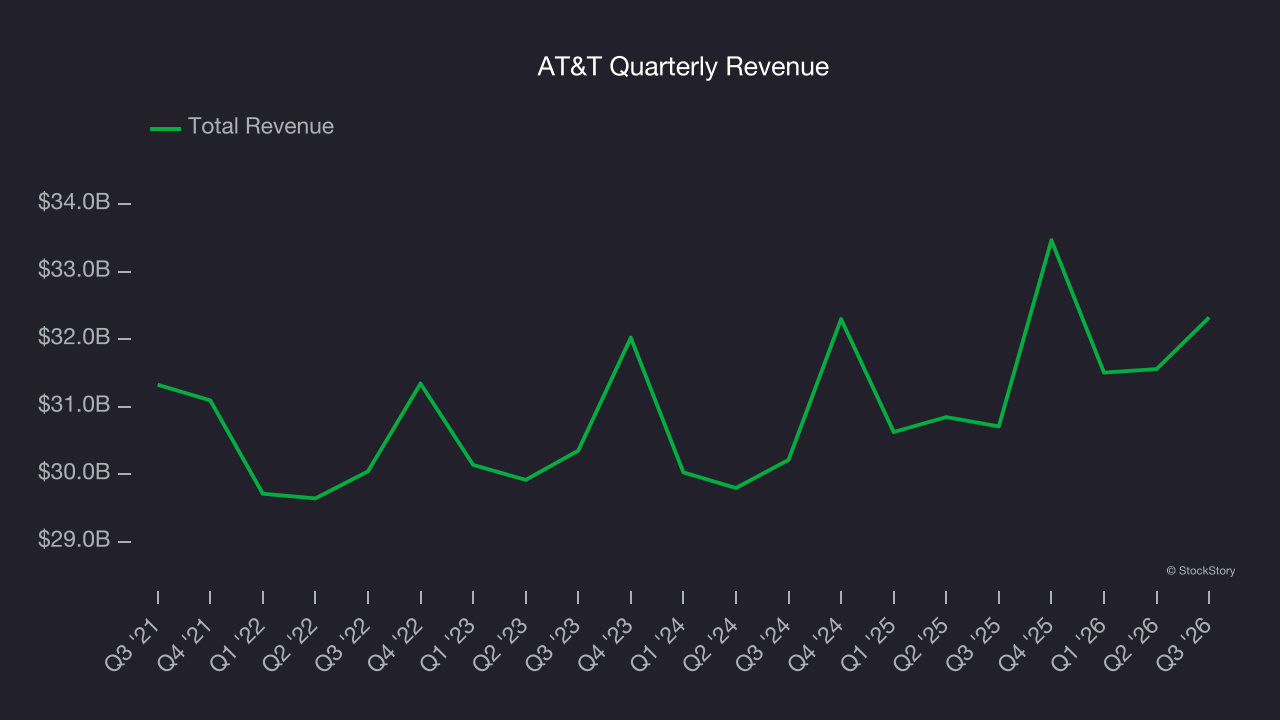
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. AT&T’s annualized revenue growth of 2.7% over the last two years is above its five-year trend, which is encouraging. 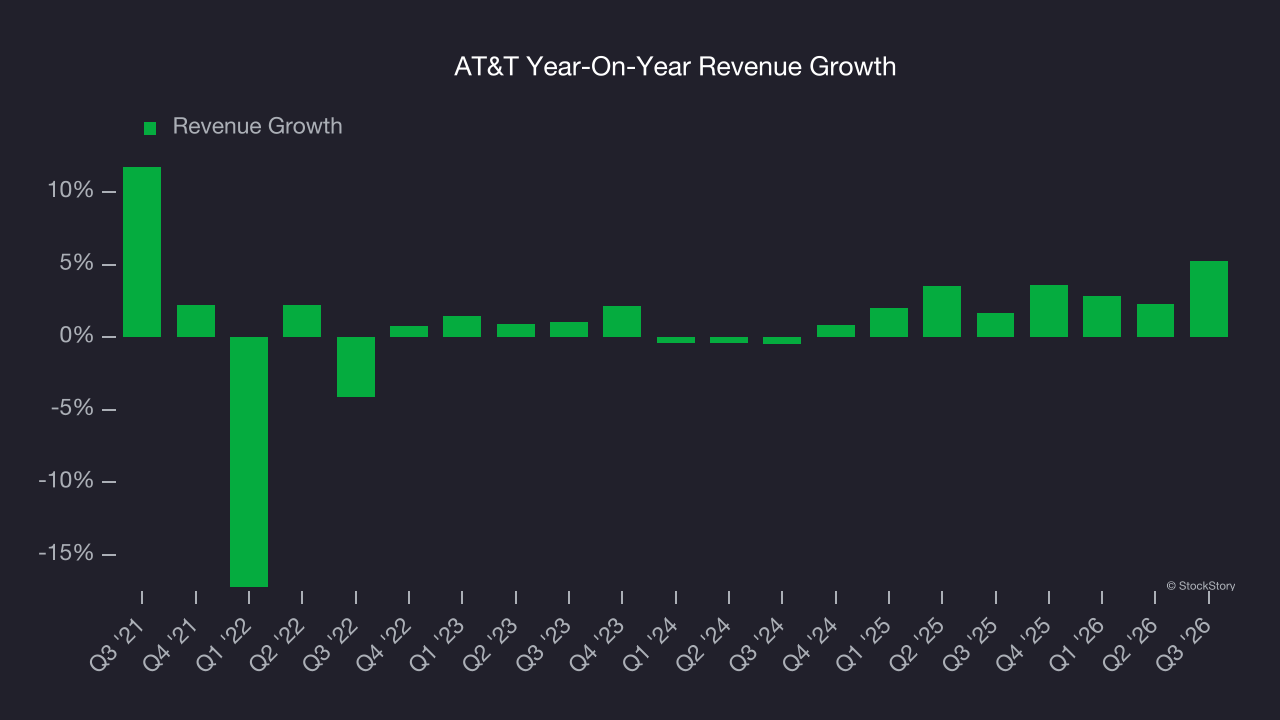
This quarter, AT&T reported year-on-year revenue growth of 5.3%, and its $32.32 billion of revenue exceeded Wall Street’s estimates by 2.1%.
Looking ahead, sell-side analysts expect revenue to grow 2% over the next 12 months, similar to its two-year rate. This projection doesn’t excite us and indicates its newer products and services will not catalyze better top-line performance yet.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
AT&T’s operating margin has more or less stayed the same over the last 12 months , and we generally like to see margin increases due to economies of scale and cost efficiency over time.
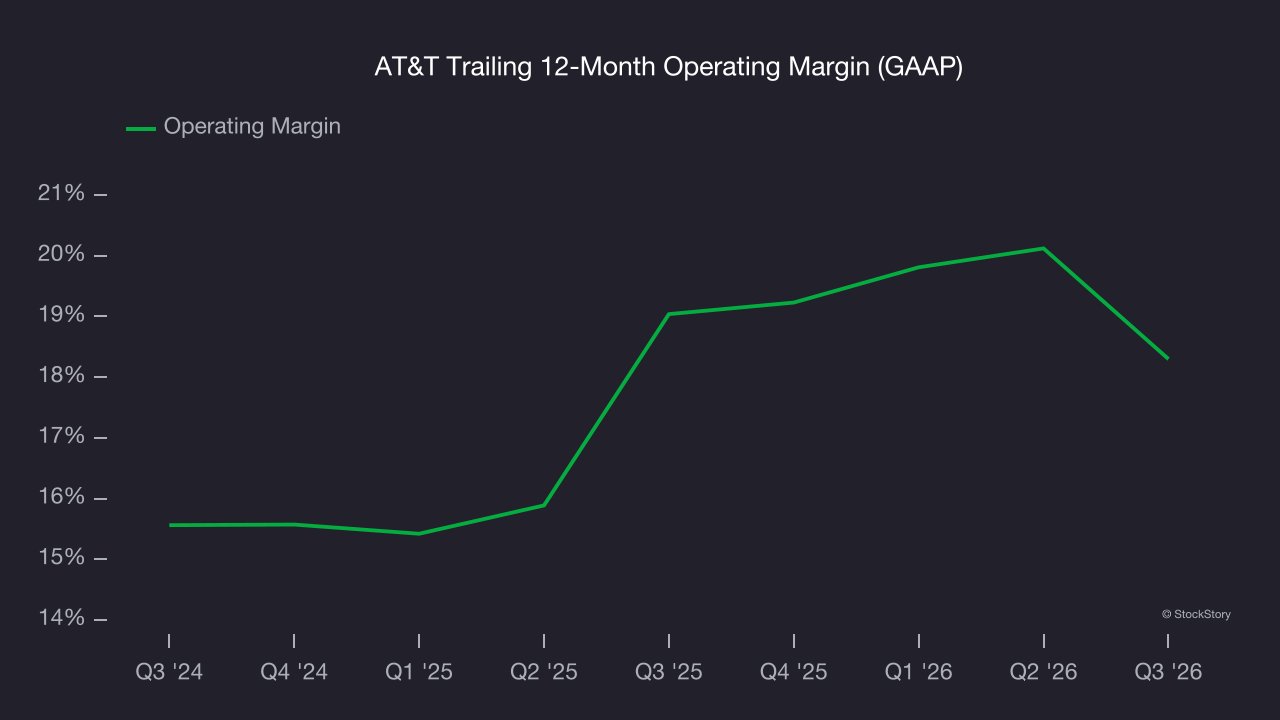
This quarter, AT&T generated an operating margin profit margin of 12.7%, down 7.3 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
AT&T’s EPS grew at 77.4% compounded annual growth rate over the last five years, higher than its flat revenue. However, this alone doesn’t tell us much about its business quality because its operating margin didn’t improve.
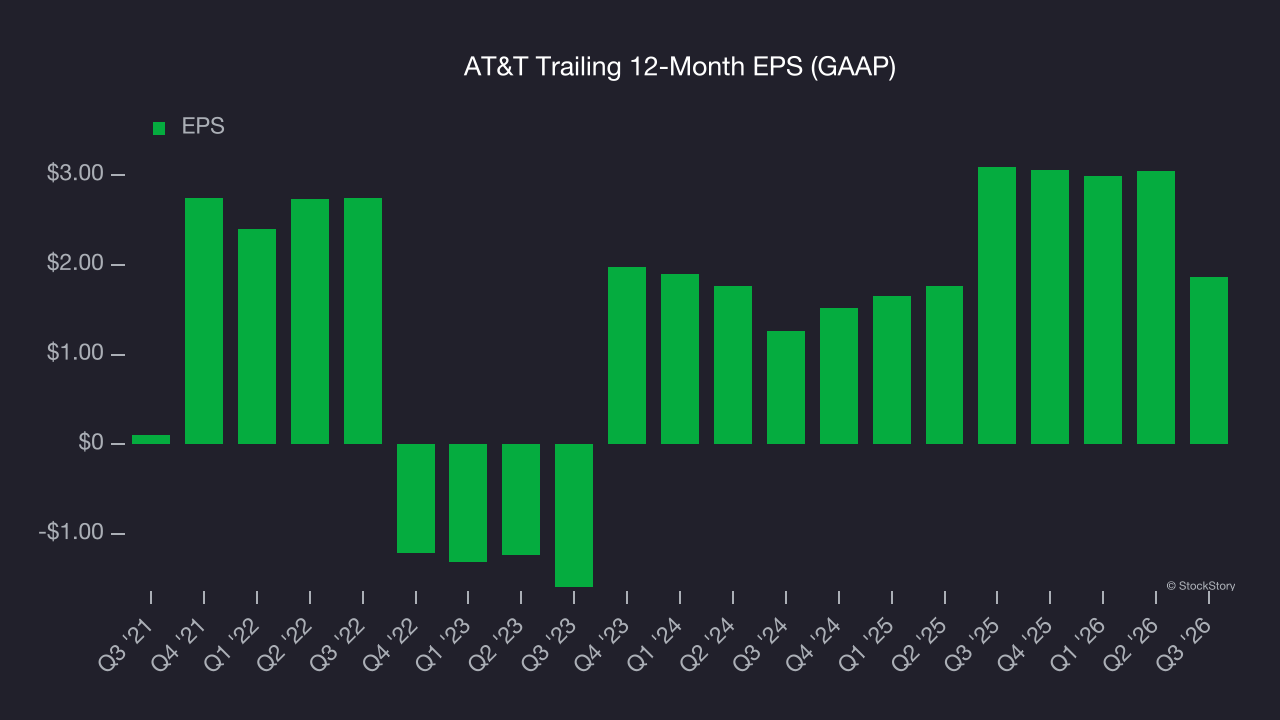
In Q3, AT&T reported EPS of $0.12, down from $1.30 in the same quarter last year. This print missed analysts’ estimates, but we care more about long-term EPS growth than short-term movements. Over the next 12 months, Wall Street expects AT&T’s full-year EPS to grow 35.2% from $1.86 to $2.52.
Key Takeaways from AT&T’s Q3 Results
It was encouraging to see AT&T beat analysts’ revenue expectations this quarter. On the other hand, its EPS missed. Overall, this quarter could have been better. The stock traded down 4.9% to $22.30 immediately following the results.
AT&T may have had a tough quarter, but does that actually create an opportunity to invest right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).