
Shareholders of Peabody Energy would probably like to forget the past six months even happened. The stock dropped 28.3% and now trades at $25.57. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in Peabody Energy, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Peabody Energy Will Underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons you should be careful with BTU, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
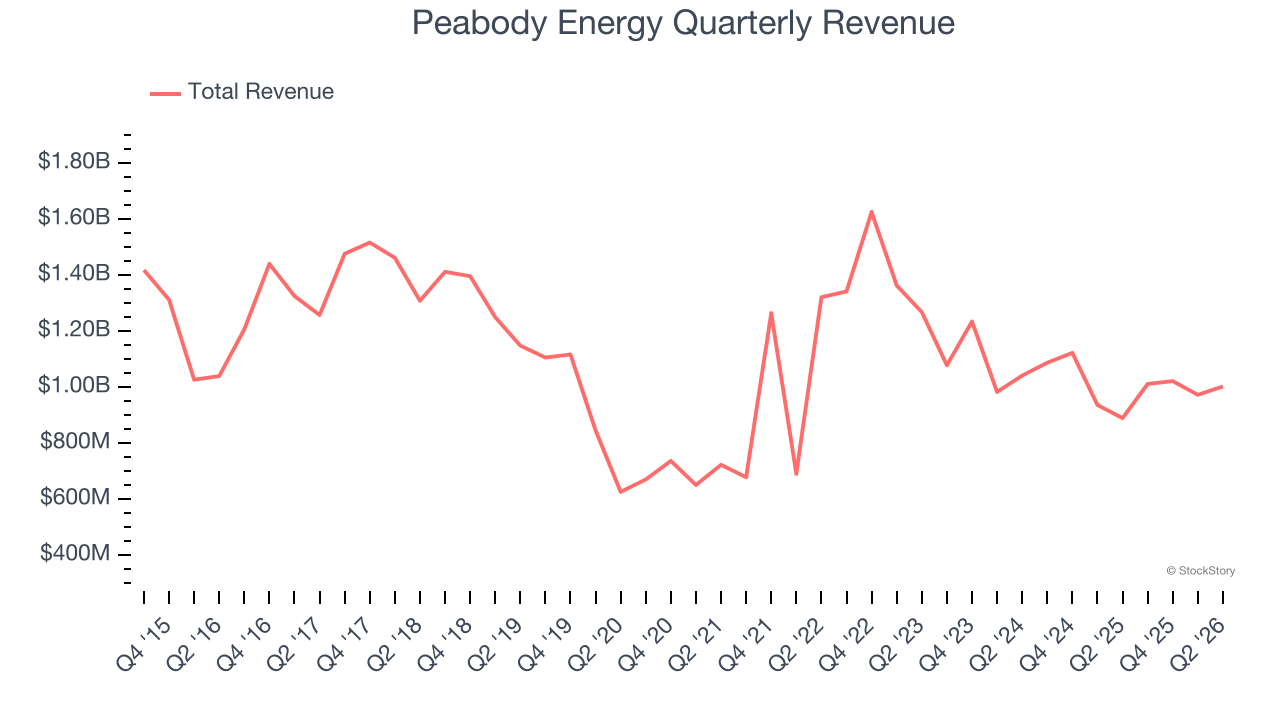
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Unfortunately, Peabody Energy’s 7.6% annualized revenue growth over the last five years was tepid. This was below our standard for the energy upstream and integrated energy sector.
2. Low Gross Margin Reveals Weak Structural Profitability
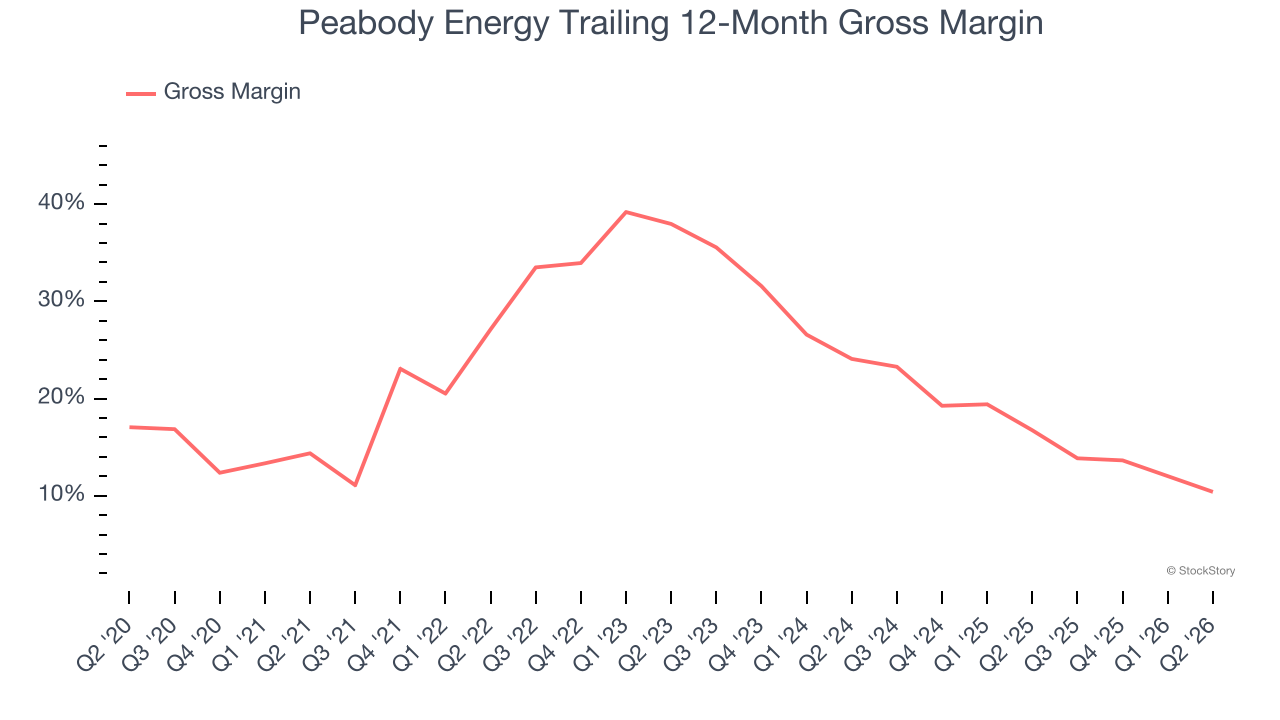
While energy gross margins can be distorted by commodity prices, hedging, and short-term cost swings, sustained margins across a full cycle reflect a producer’s underlying asset quality, infrastructure position, and cost structure.
Peabody Energy, which averaged 24.3% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. Shrinking EBITDA Margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
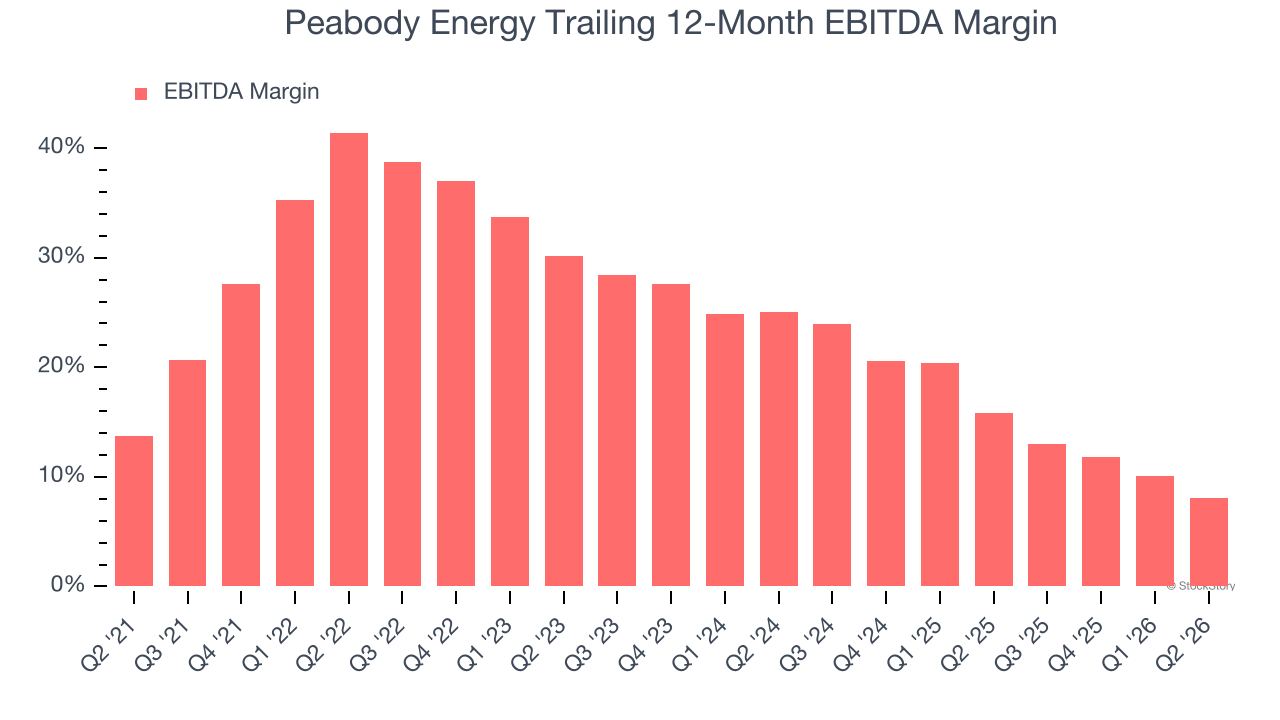
Analyzing the trend in its profitability, Peabody Energy’s EBITDA margin decreased by 33.3 percentage points over the last year. Peabody Energy’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its EBITDA margin for the trailing 12 months was 8.1%.
Final Judgment
Peabody Energy falls short of our quality standards. After the recent drawdown, the stock trades at 24.8× forward P/E (or $25.57 per share). This valuation tells us a lot of optimism is priced in - we think there are better opportunities elsewhere. We’d suggest looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.