Homebuilder Meritage Homes (NYSE: MTH) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 17.9% year on year to $1.17 billion. Its non-GAAP profit of $1.11 per share was 2.5% below analysts’ consensus estimates.
For more on Meritage Homes, read our full research report, available free.
Meritage Homes (MTH) Q3 2026 highlights:
- Revenue $1.17 billion vs S&P analysts’ consensus estimates of $1.30 billion (17.9% year-on-year decline, 10% miss)
- Adjusted EPS $1.11 vs S&P analysts’ consensus estimates of $1.14 (2.5% miss)
- Operating margin 7.1%, down from 8.4% in the same quarter last year
- Free cash flow -$35.3 million compared to -$104.2 million in the same quarter last year
- Backlog $637.2 million at quarter end, down 4.9% year on year
- Market capitalization $4.17 billion
"In today's volatile market, prudently managing capital is a key priority, as we continue to focus on maintaining sufficient liquidity. During the quarter, we pulled back our land investments by almost 40% year-over-year to $329 million and returned $86 million to shareholders via share repurchases and dividends. We are confident that the strength of our balance sheet and prudence around cash preservation will be a differentiator, as we expect market conditions to continue to be unpredictable over the next several quarters. In the first nine months of 2026, we have returned nearly $380 million of capital to shareholders, representing 177% of total earnings so far this year," concluded Mr. Lord. "We ended the third quarter of 2026 with cash of $677 million, no borrowings under our revolving credit facility, and a net debt-to-capital ratio of 18.9%. As of September 30, 2026, our book value per share increased 4% year-over-year."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Meritage Homes struggled to consistently increase demand as its $5.14 billion in revenue for the trailing 12 months was close to its revenue five years ago. This fell short of our standards and suggests it’s a low-quality business.
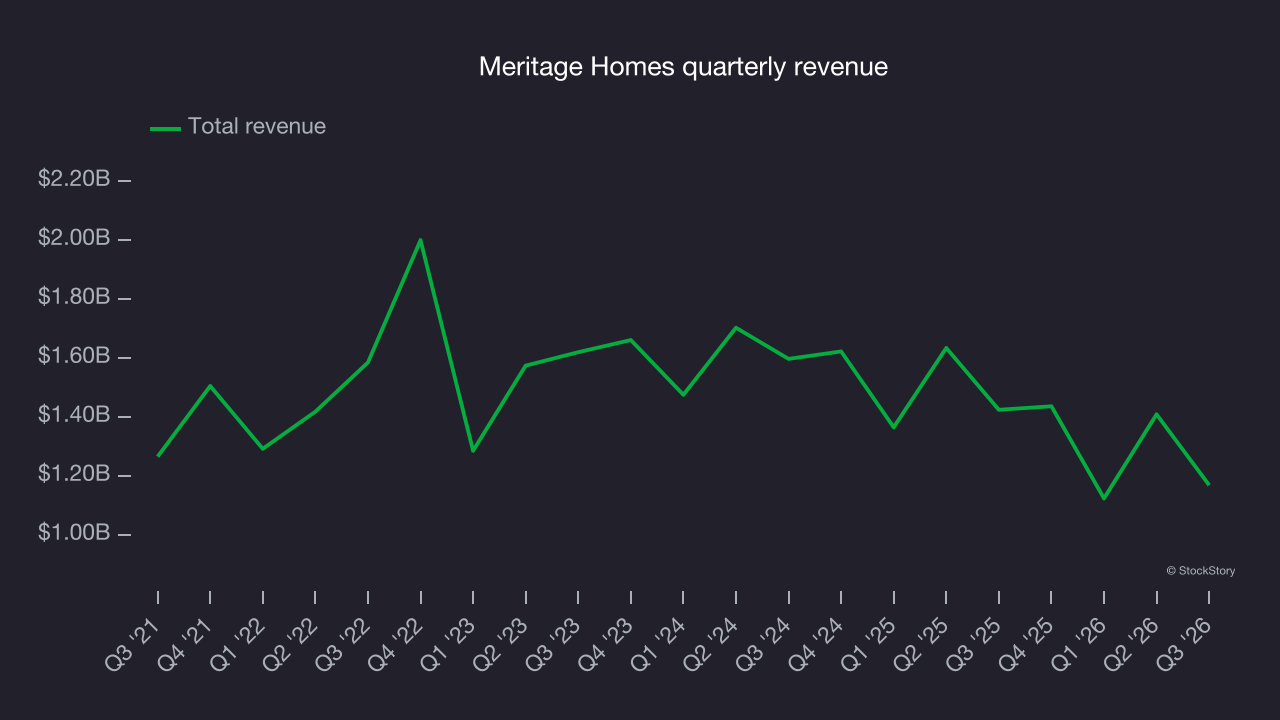
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Meritage Homes’s recent performance shows its demand remained suppressed as its revenue has declined by 10.7% annually over the last two years. Meritage Homes isn’t alone in its struggles as the home builders industry experienced a cyclical downturn, with many similar businesses reporting lower revenue during this period. 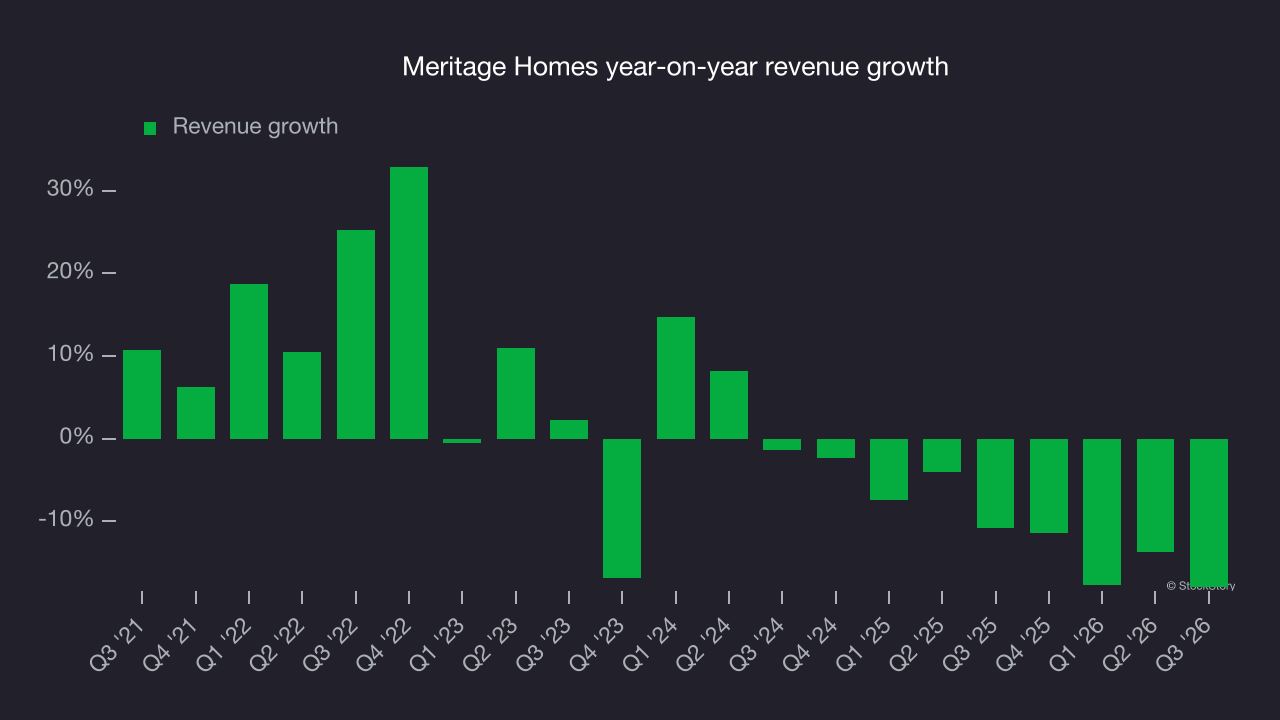
We can better understand the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. Meritage Homes’s backlog reached $637.2 million in the latest quarter and averaged 24.4% year-on-year declines over the last two years. Backlog declined faster than revenue, indicating the company hasn’t secured enough new orders to maintain its growth rate in the future. 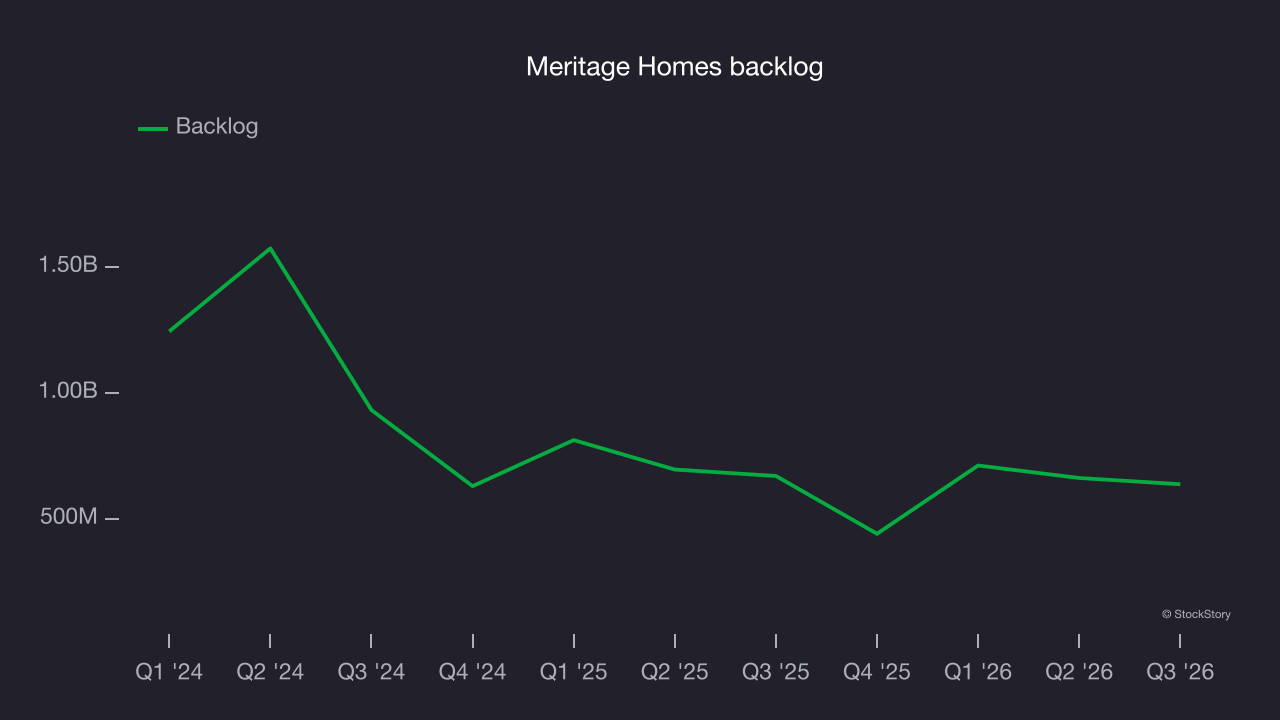
This quarter, Meritage Homes missed Wall Street’s consensus estimates and reported an uninspiring 17.9% year-on-year revenue decline, generating $1.17 billion in revenue.
Looking ahead, sell-side analysts expect revenue to grow 5.7% over the next 12 months, according to S&P. While this projection suggests its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
Meritage Homes has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 14.3%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes substantial shifts to move meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Looking at the trend in its profitability, Meritage Homes’s operating margin decreased by 14.5 percentage points over the last five years. Many home builders also saw their margins fall (along with revenue, as mentioned above) because the cycle turned unfavorable. Meritage Homes could emerge as a stronger company, as downturns offer opportunities to gain market share and improve efficiency.
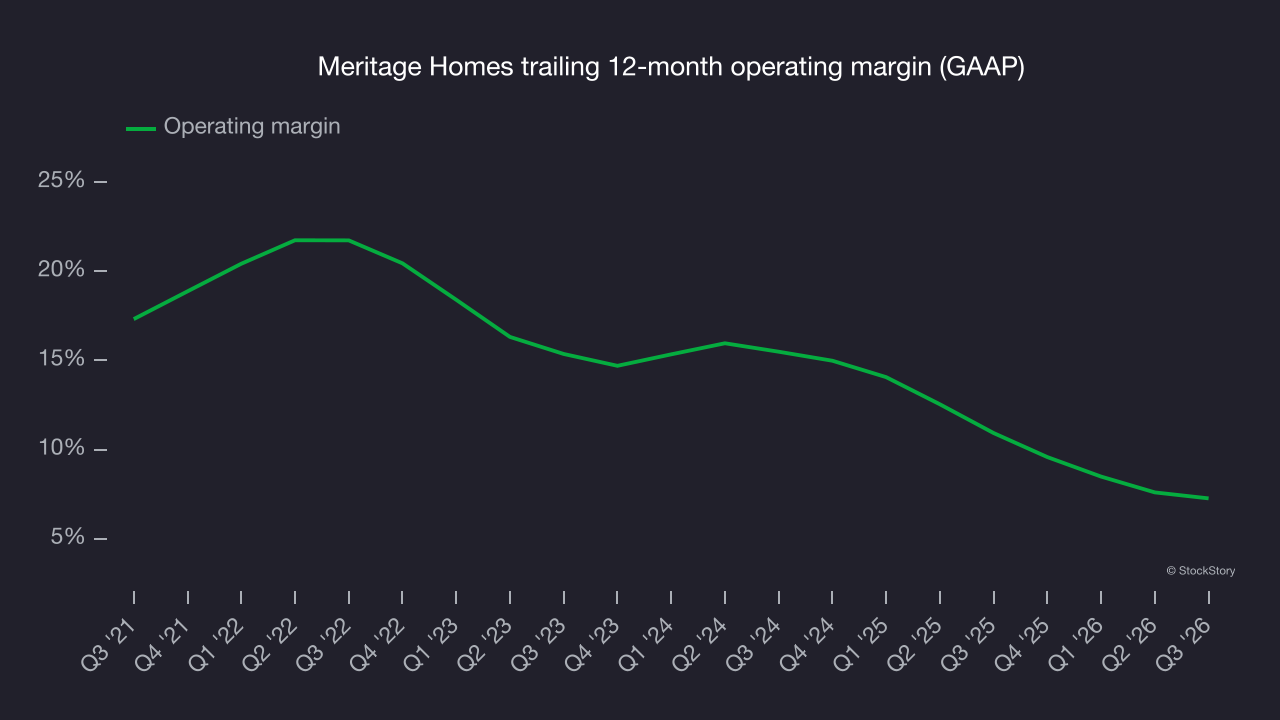
In Q3, Meritage Homes generated an operating margin of 7.1%, down 1.3 percentage points year on year. Meritage Homes’s gross margin decreased more than its operating margin, suggesting its recent inefficiencies were driven more by weaker leverage on its cost of sales than by increased marketing, R&D and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Meritage Homes’s EPS declined by 12.1% annually over the last five years while its revenue was flat. This indicates the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
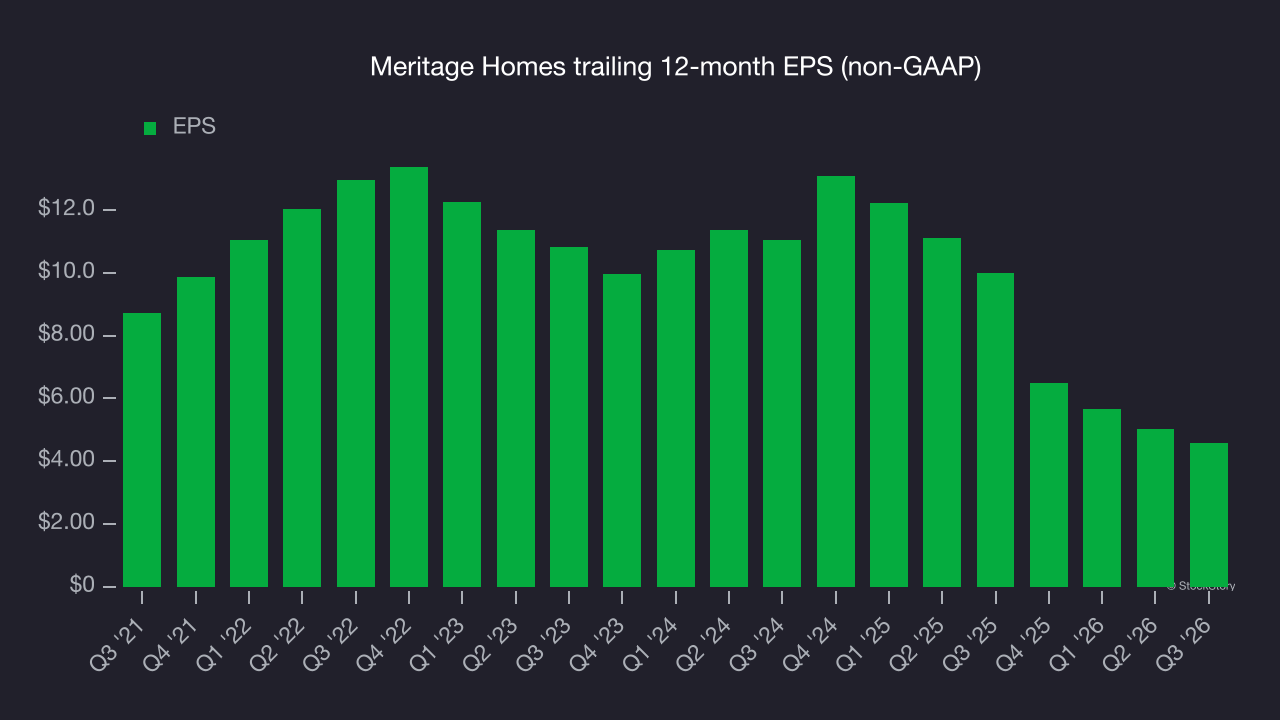
We can take a deeper look into Meritage Homes’s earnings to better understand the drivers of its performance. As we mentioned earlier, Meritage Homes’s operating margin declined by 14.5 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Meritage Homes, its two-year annual EPS declines of 35.5% show it’s continued to underperform. The results were poor over both periods.
In Q3, Meritage Homes reported adjusted EPS of $1.11, down from $1.55 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Meritage Homes’s full-year EPS to grow 17.9% from $4.59 to $5.41, according to S&P.
Key takeaways from Meritage Homes’s Q3 results
Meritage Homes delivered a weaker quarter, with few positives as both revenue and EPS fell short of Wall Street’s consensus estimates. Shares tumbled 6.1% to $58.27 immediately after the results.
Meritage Homes’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so assessing the stock at its current price requires a broader view. The latest results matter when deciding whether to invest, but not as much as longer-term business quality and valuation. For more on Meritage Homes, read our full research report here (it’s free).