
Aviation and defense services provider AAR CORP (NYSE: AIR) announced better-than-expected revenue in Q3 CY2026, with sales up 24.1% year on year to $918 million. Guidance for next quarter’s revenue was optimistic at $914.6 million at the midpoint, 2.6% above analysts’ estimates. Its non-GAAP profit of $1.49 per share was 14.9% above analysts’ consensus estimates.
Is now the time to buy AAR? Find out by accessing our full research report, it’s free.
AAR (AIR) Q3 CY2026 Highlights:
- Revenue: $918 million vs analyst estimates of $879.6 million (24.1% year-on-year growth, 4.4% beat)
- Adjusted EPS: $1.49 vs analyst estimates of $1.30 (14.9% beat)
- Adjusted EBITDA: $116.5 million vs analyst estimates of $107.2 million (12.7% margin, 8.7% beat)
- Revenue Guidance for Q4 CY2026 is $914.6 million at the midpoint, above analyst estimates of $891.4 million
- Operating Margin: 7.9%, in line with the same quarter last year
- Free Cash Flow was $44 million, up from -$53.6 million in the same quarter last year
- Market Capitalization: $4.53 billion
"Along with our strong fiscal first quarter earnings, we also announced an agreement to acquire a 65% controlling interest in MRO Holdings. Over the last several years, AAR has taken important steps to reshape our portfolio into an integrated Parts, Repair, and Software aviation aftermarket platform. Through the acquisition of MRO Holdings, AAR will achieve scale that significantly accelerates our strategy as heavy maintenance helps drive revenue to all other areas of the company. Further, the transaction structure allows us to partner with a proven team that brings decades of experience in a strategically important region while also providing the financial flexibility to continue to pursue AAR's broader strategy. This acquisition is highly strategic for AAR and marks a significant step in our long-term growth plan."
Company Overview
The first third-party MRO approved by the FAA for Safety Management System Requirements, AAR (NYSE: AIR) is a provider of aircraft maintenance services
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, AAR grew its sales at an incredible 15.3% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
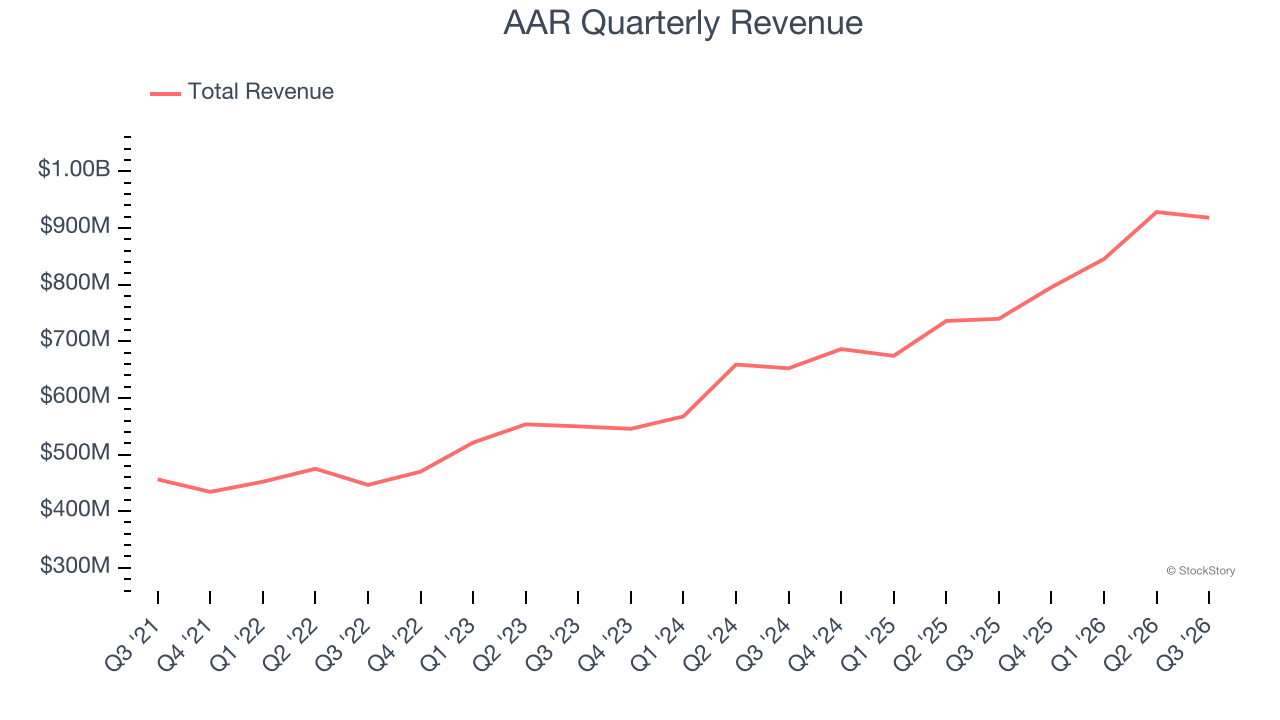
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. AAR’s annualized revenue growth of 19.9% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 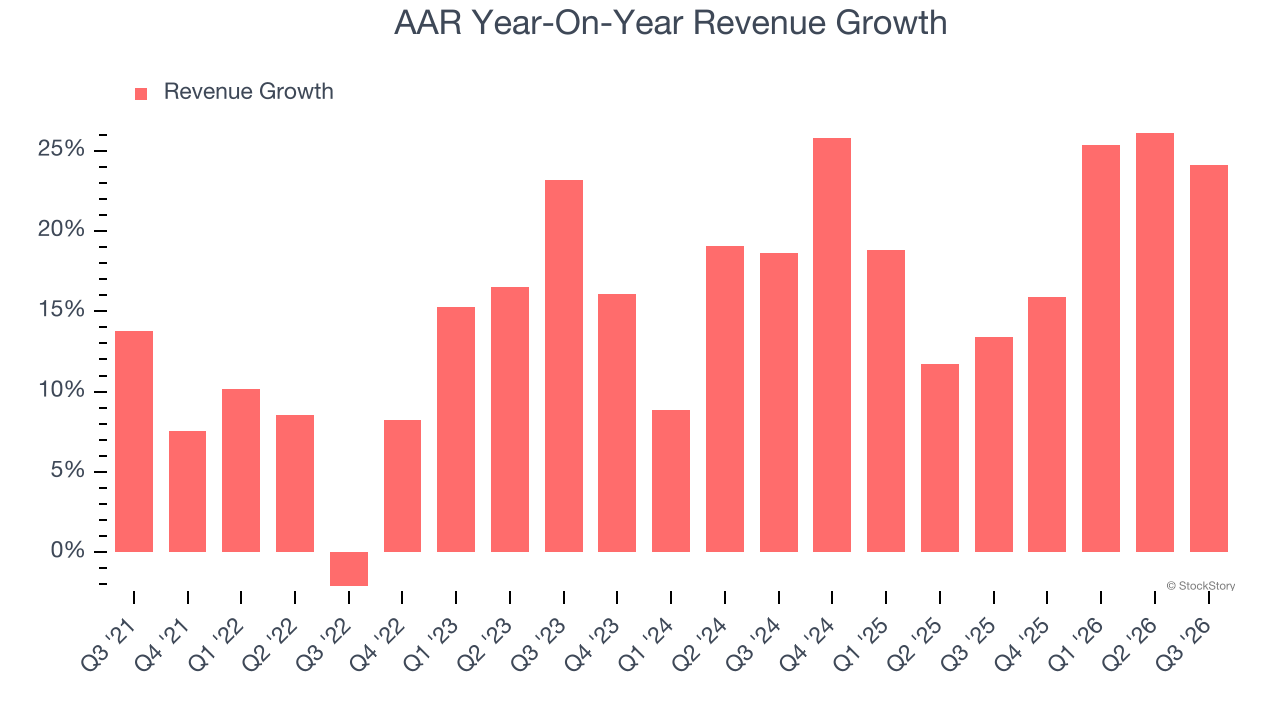
AAR also breaks out the revenue for its three most important segments: Parts Supply, Repair & Engineering, and Integrated Solutions, which are 45.2%, 32.4%, and 15.1% of revenue. Over the last two years, AAR’s Parts Supply (engine and airframe parts) and Repair & Engineering (maintenance, repair, and overhaul services) revenues averaged year-on-year growth of 28.5% and 23.5% while its Integrated Solutions revenue (fleet management) averaged 2.7% declines. 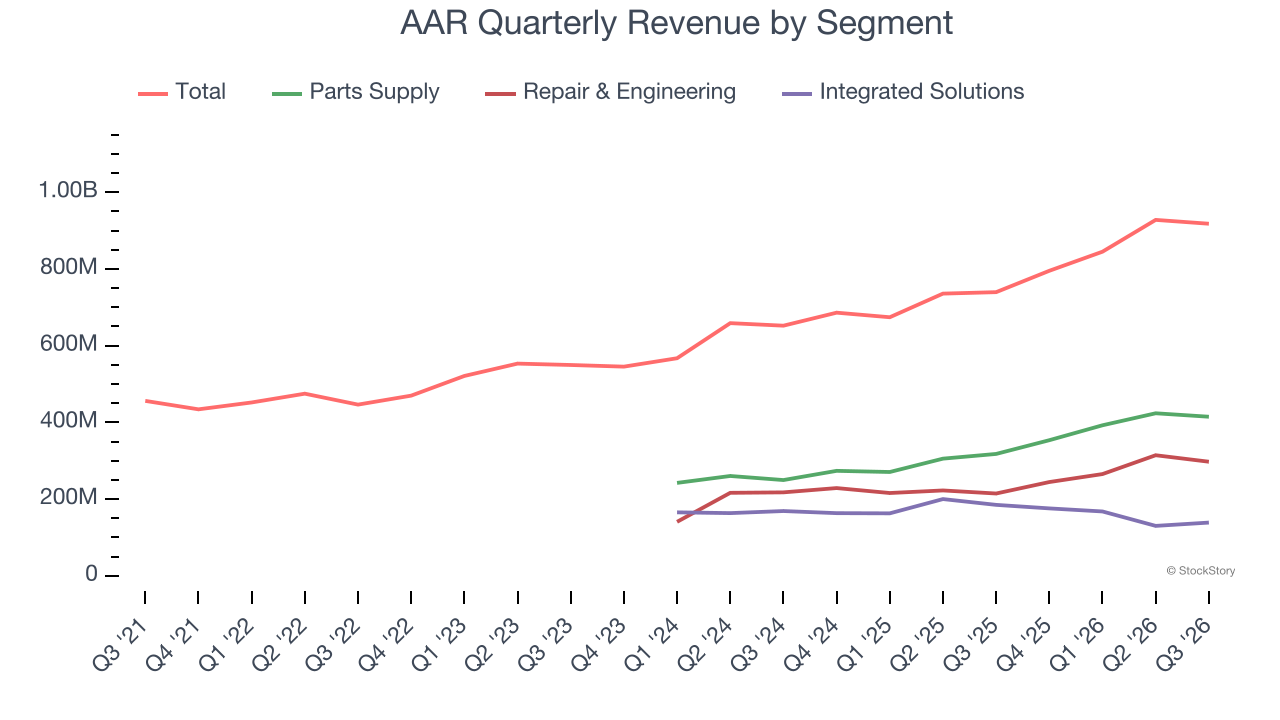
This quarter, AAR reported robust year-on-year revenue growth of 24.1%, and its $918 million of revenue topped Wall Street estimates by 4.4%. Company management is currently guiding for a 15% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 6.8% over the next 12 months, a deceleration versus the last two years. This projection doesn’t excite us and suggests its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating Margin
AAR was profitable over the last five years but held back by its large cost base. Its average operating margin of 7% was weak for an industrials business.
On the plus side, AAR’s operating margin rose by 1.4 percentage points over the last five years, as its sales growth gave it operating leverage.
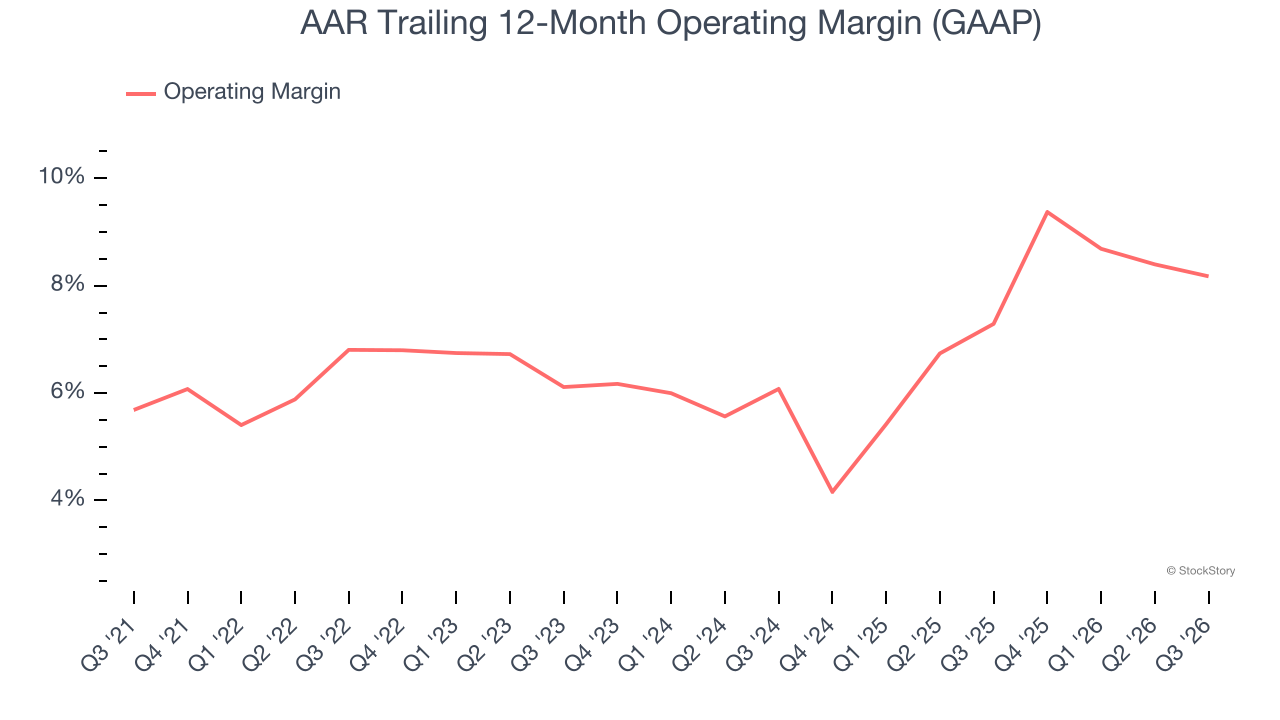
This quarter, AAR generated an operating margin profit margin of 7.9%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
AAR’s EPS grew at 26.7% compounded annual growth rate over the last five years, higher than its 15.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
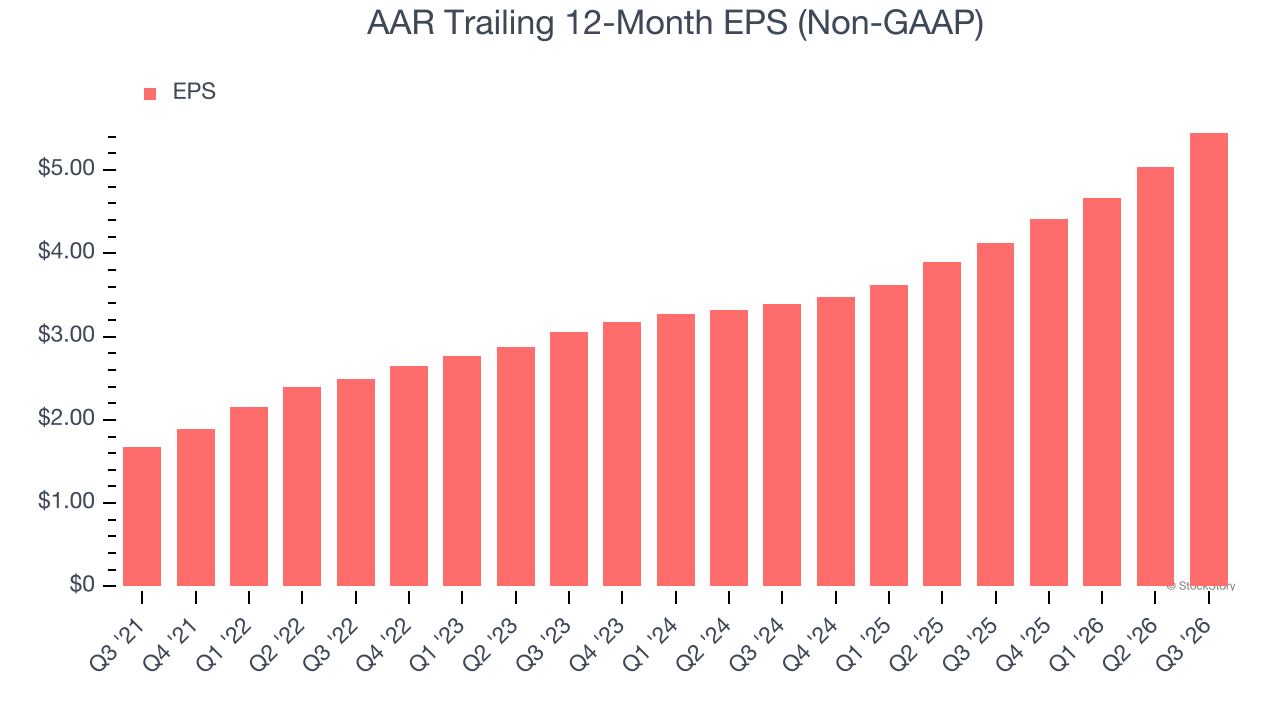
We can take a deeper look into AAR’s earnings to better understand the drivers of its performance. As we mentioned earlier, AAR’s operating margin was flat this quarter but expanded by 1.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For AAR, its two-year annual EPS growth of 26.8% is similar to its five-year trend, implying strong and stable earnings power.
In Q3, AAR reported adjusted EPS of $1.49, up from $1.08 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. We also like to analyze expected EPS growth based on Wall Street analysts’ consensus projections, but there is insufficient data.
Key Takeaways from AAR’s Q3 Results
We were impressed by how significantly AAR blew past analysts’ EBITDA expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a solid print. The market seemed to be hoping for more, and the stock traded down 7.6% to $106.36 immediately after reporting.
Is AAR an attractive investment opportunity at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).