Infrastructure equipment supplier SPX Technologies (NYSE: SPXC) met Wall Street’s revenue expectations in Q3 2026, with revenue up 20.5% year on year to $714.5 million. The company’s outlook for the full year was close to analysts’ consensus estimates with revenue guided to $2.78 billion at the midpoint. Its non-GAAP profit of $2.21 per share was 5.6% above analysts’ consensus estimates.
For more on SPX Technologies, read our free full research report.
SPX Technologies (SPXC) Q3 2026 highlights:
- Revenue $714.5 million vs S&P analysts’ consensus estimates of $711.6 million (20.5% year-on-year growth, in line)
- Adjusted EPS $2.21 vs S&P analysts’ consensus estimates of $2.09 (5.6% beat)
- Adjusted EBITDA $165.7 million vs analysts’ consensus estimates of $169 million (23.2% margin, 2% miss)
- Revenue guidance The company lifted its revenue guidance for the full year to $2.78 billion at the midpoint from $2.74 billion, a 1.5% increase
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $8.35 at the midpoint, a 0.6% decrease
- EBITDA guidance $635 million at the midpoint for the full year, below analysts’ consensus estimates of $645.8 million
- Operating margin 16.1%, in line with the same quarter last year
- Free cash flow margin 2.7%, down from 15.3% in the same quarter last year
- Organic revenue rose 11.8% year on year (miss)
- Market capitalization $8.27 billion
Gene Lowe, President and CEO, remarked, “We delivered another strong quarter, highlighted by robust revenue and earnings growth. HVAC continued to benefit from strong demand across key end markets, while Detection & Measurement delivered excellent profitability. Our results reflect the strength of our business model and the consistent execution of our teams.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. SPX Technologies’s revenue grew at a strong 16.4% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
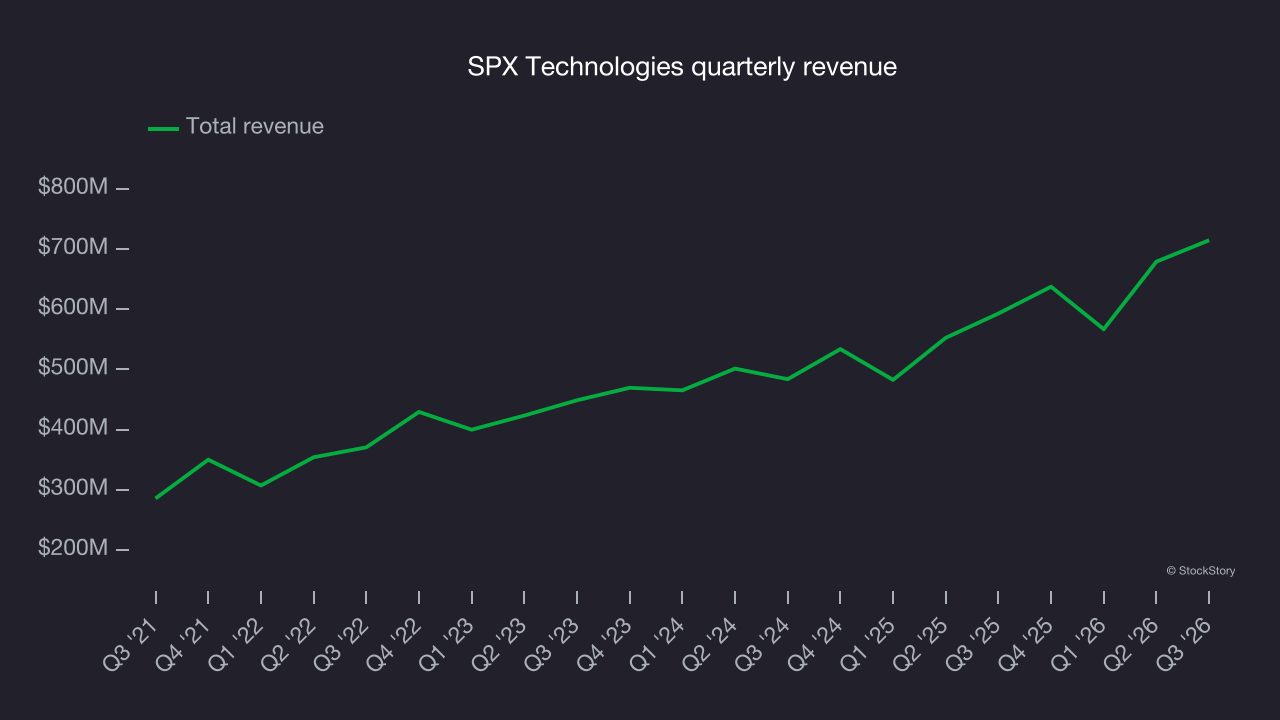
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. SPX Technologies’s annualized revenue growth of 16.3% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 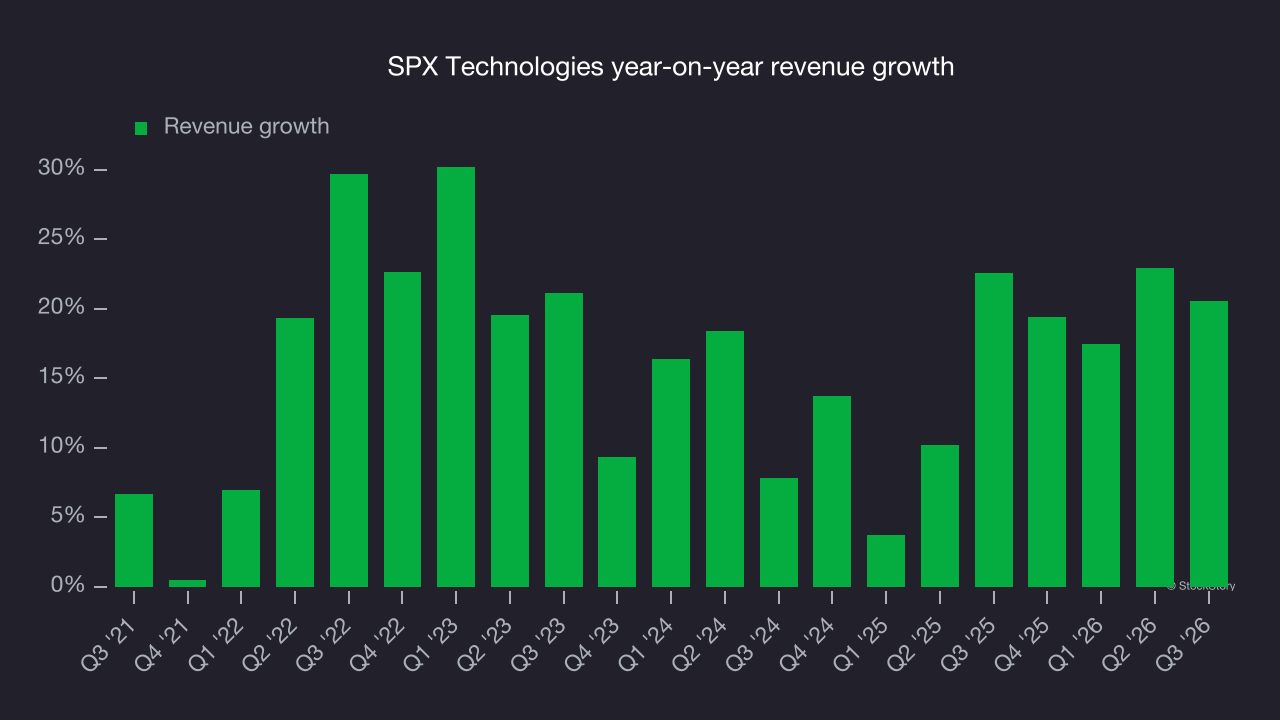
Organic revenue offers a closer look at the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, SPX Technologies’s organic revenue averaged 8.6% year-on-year growth. Total revenue growth outpaced organic growth over that period, indicating that a combination of acquisitions and foreign exchange rates boosted its headline results. 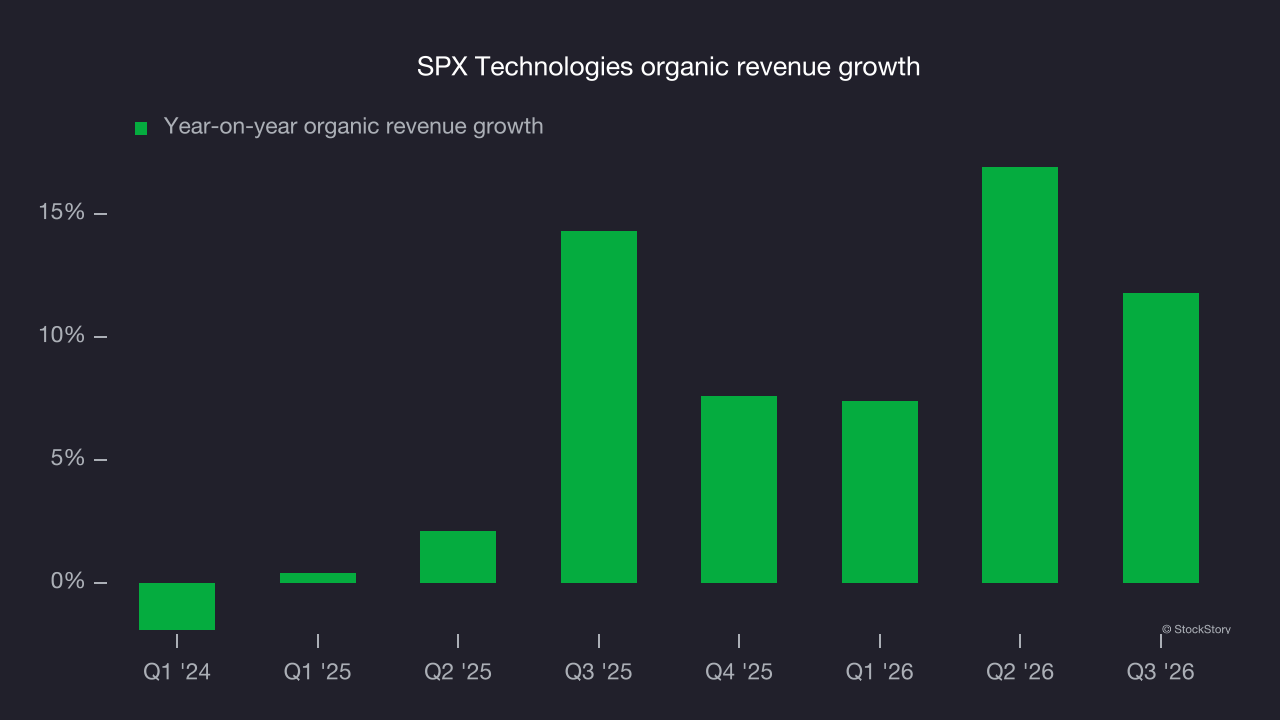
This quarter, SPX Technologies’s year-on-year revenue growth of 20.5% was strong, and its $714.5 million of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 18.3% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection suggests its newer products and services will spur better revenue performance.
Operating margin
SPX Technologies has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 12.9%. That result is unsurprising given its favorable gross margin baseline.
SPX Technologies’s operating margin rose by 9.6 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
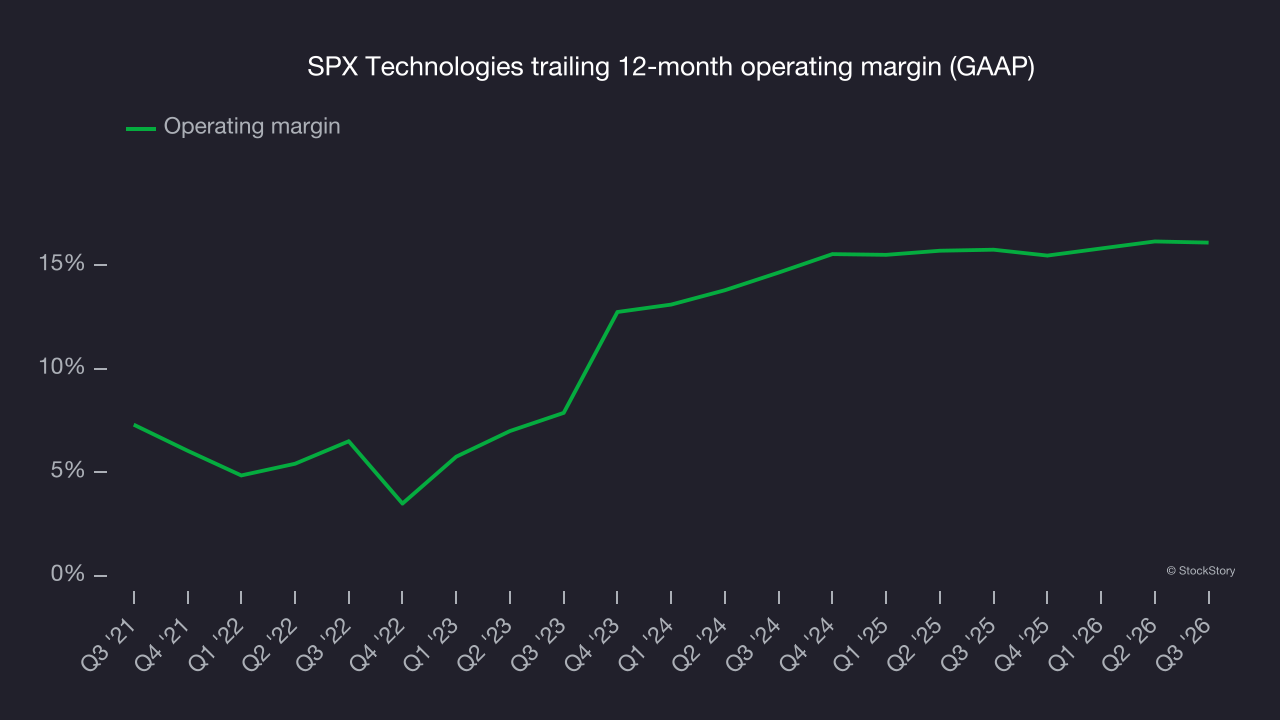
This quarter, SPX Technologies generated an operating margin of 16.1%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
SPX Technologies’s EPS grew at a 25.9% compounded annual growth rate over the last five years, higher than its 16.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
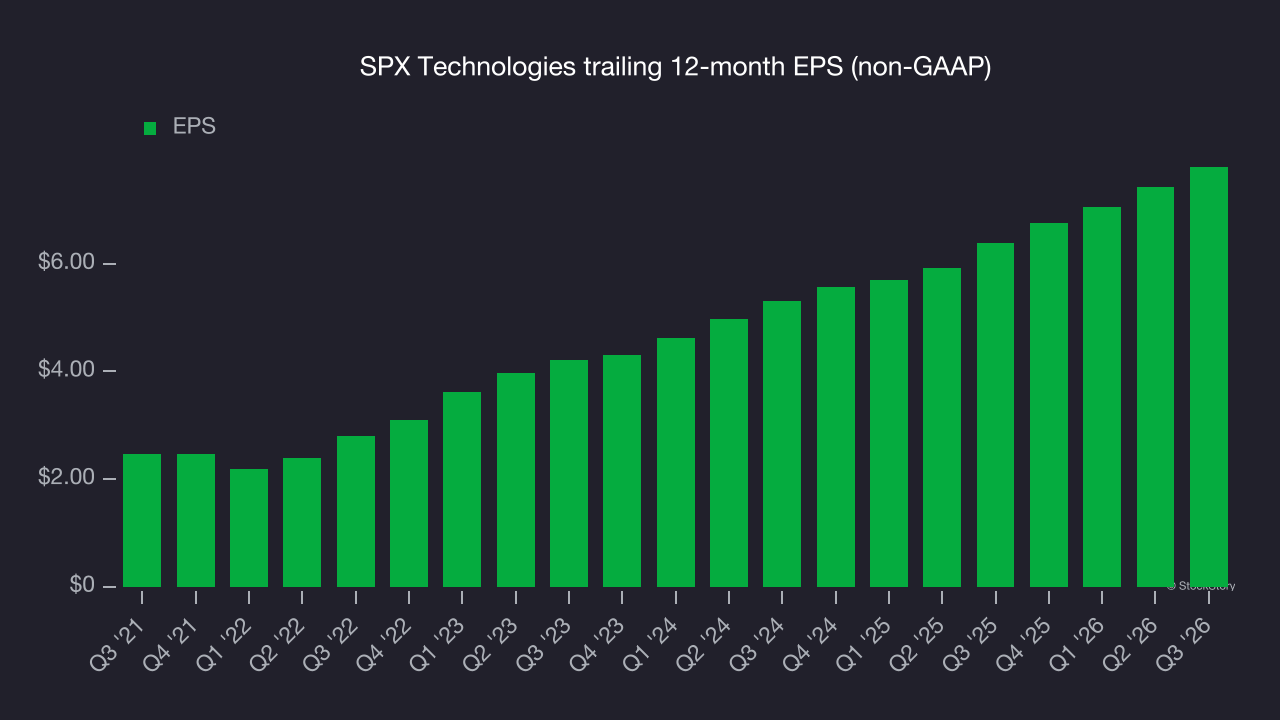
We can take a deeper look into SPX Technologies’s earnings to better understand the drivers of its performance. As we mentioned earlier, SPX Technologies’s operating margin was flat this quarter but expanded by 9.6 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For SPX Technologies, its two-year annual EPS growth of 21.2% was lower than its five-year trend. That was still a good pace of growth, and an acceleration would be welcome.
In Q3, SPX Technologies reported adjusted EPS of $2.21, up from $1.84 in the same quarter last year. This result beat analysts’ consensus estimates by 5.6%. Over the next 12 months, Wall Street expects SPX Technologies’s full-year EPS to grow 19.6% from $7.80 to $9.33, according to S&P.
Key takeaways from SPX Technologies’s Q3 results
SPX Technologies’ EPS beat wasn’t enough to make this a better quarter: organic revenue came in slightly below Wall Street’s consensus estimates, and full-year EBITDA guidance also missed. Full-year revenue guidance was in line with Wall Street’s consensus estimates, but the results overall could have been better. Shares remained flat at $168.79 immediately after the release.
Considering an investment in SPX Technologies at the current price? The latest quarter matters, but longer-term fundamentals and valuation matter more when deciding whether to buy the stock. Read the full research report here (it’s free).