Tanker company Scorpio Tankers (NYSE: STNG) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 14.4% year on year to $266.5 million. Its non-GAAP profit of $2.49 per share was 18.2% above analysts’ consensus estimates.
For more on Scorpio Tankers, read our free full research report.
Scorpio Tankers (STNG) Q3 2026 highlights:
- Revenue $266.5 million vs S&P analysts’ consensus estimates of $242.8 million (14.4% year-on-year growth, 9.7% beat)
- Adjusted EPS $2.49 vs S&P analysts’ consensus estimates of $2.11 (18.2% beat)
- Adjusted EBITDA $172.2 million vs analysts’ consensus estimates of $143.1 million (64.6% margin, 20.4% beat)
- Operating margin 101% (inclusive of 57% one-time benefit from gain on sale of vessels), up from 35.5% in the same quarter last year
- Free cash flow margin 34.6%, down from 50.6% in the same quarter last year
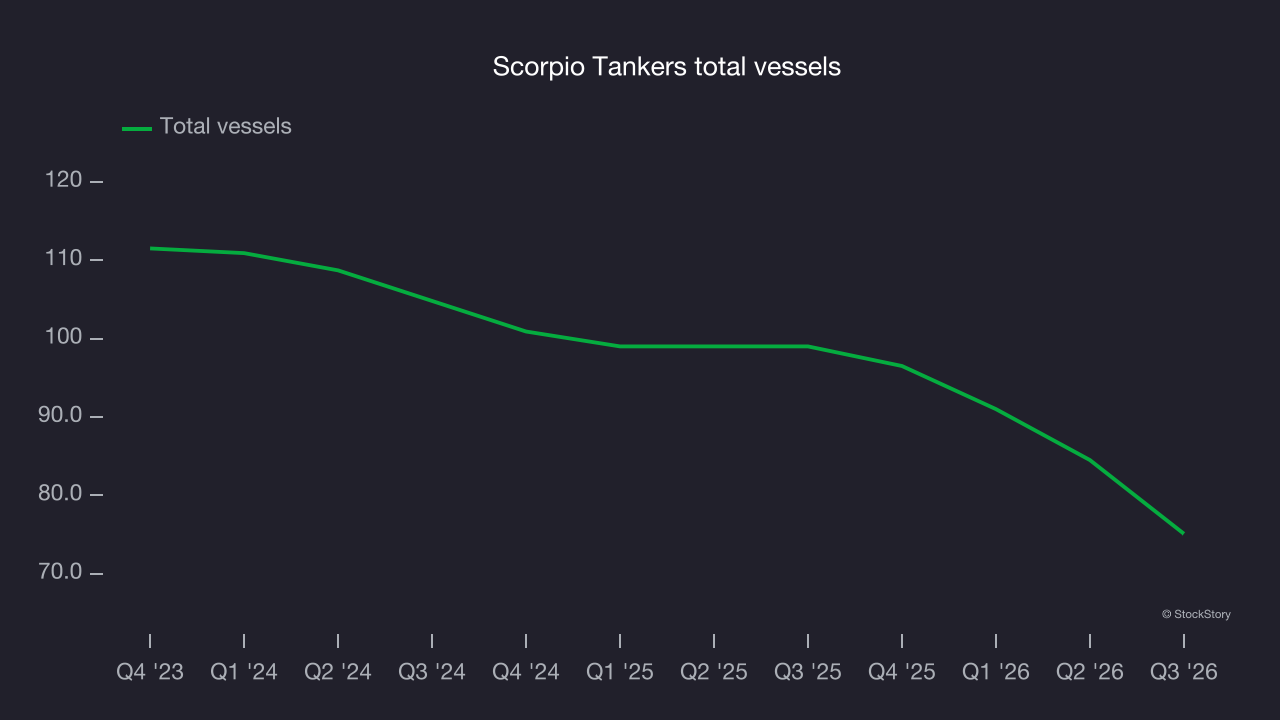
- Total vessels down 23.9 year on year
- Market capitalization $3.88 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Scorpio Tankers’s revenue grew at a strong 17.9% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
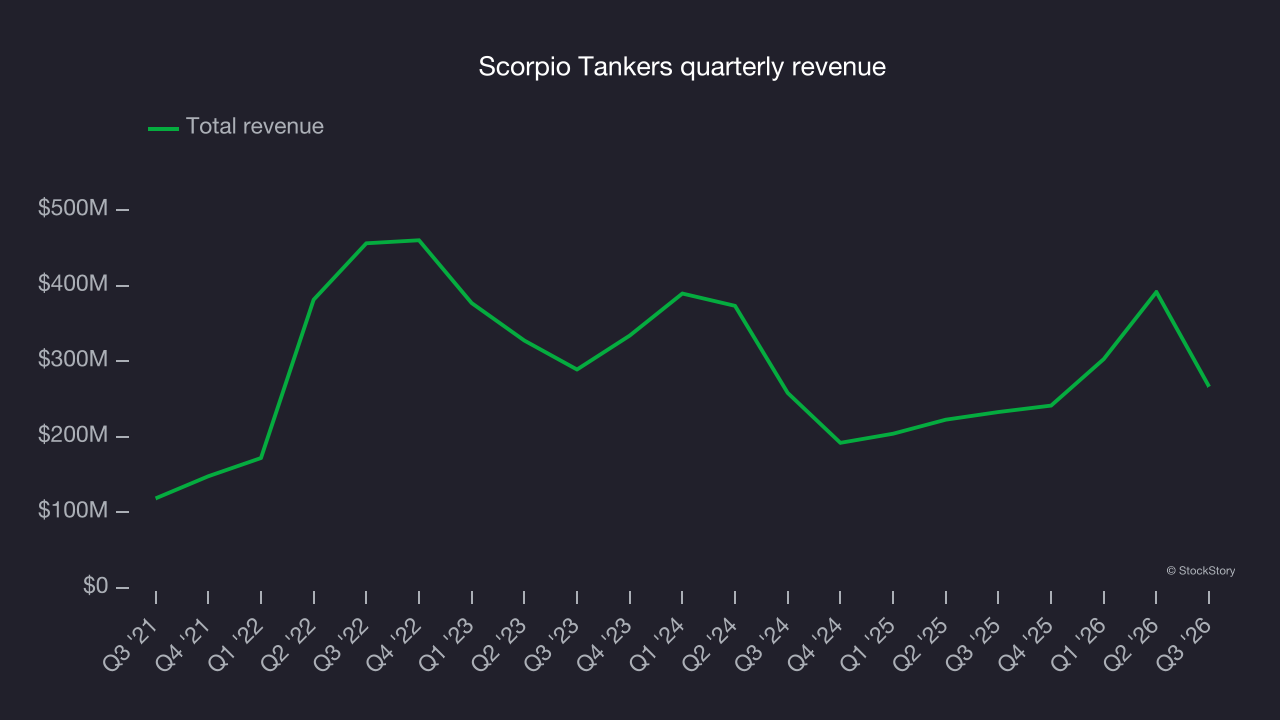
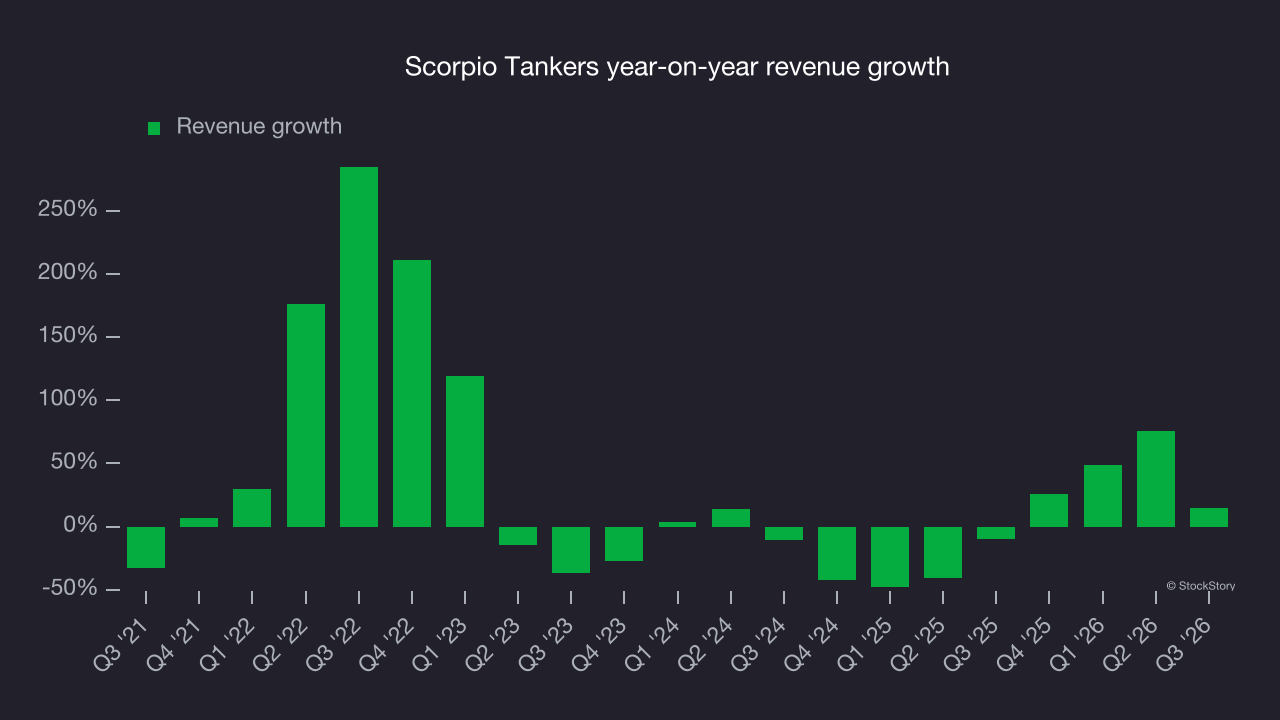
This quarter, Scorpio Tankers reported year-on-year revenue growth of 14.4%, and its $266.5 million of revenue exceeded Wall Street’s consensus estimates by 9.7%.
Looking ahead, sell-side analysts expect revenue to decline by 16.4% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Scorpio Tankers has performed well over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 58.1%. This result is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Scorpio Tankers’s operating margin rose by 43.5 percentage points over the last five years, as its revenue growth provided operating leverage. Its expansion was impressive, especially considering most marine transportation peers saw their margins decline.
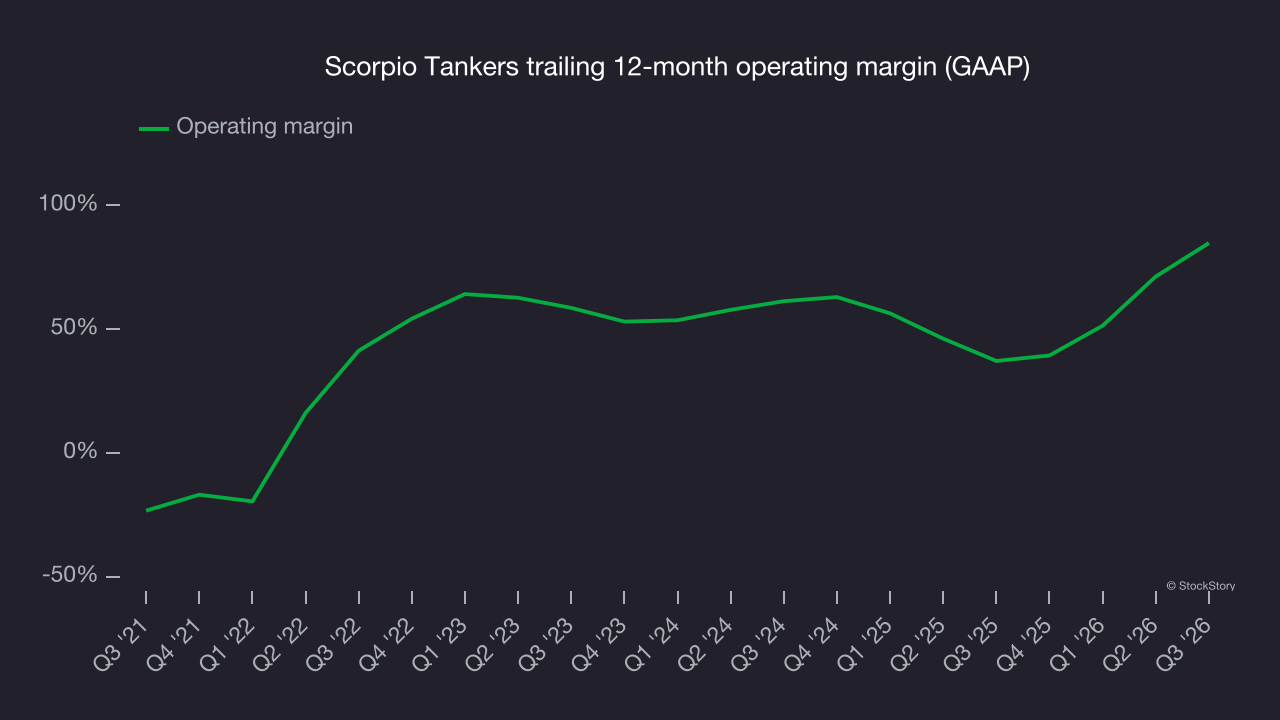
This quarter, Scorpio Tankers generated an operating margin of 101%, up 65.5 percentage points year on year. The increase was solid and shows its expenses recently grew more slowly than its revenue, leading to higher efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Scorpio Tankers’s full-year EPS flipped from negative to positive over the last five years. This is a positive development and marks a critical point for the company.
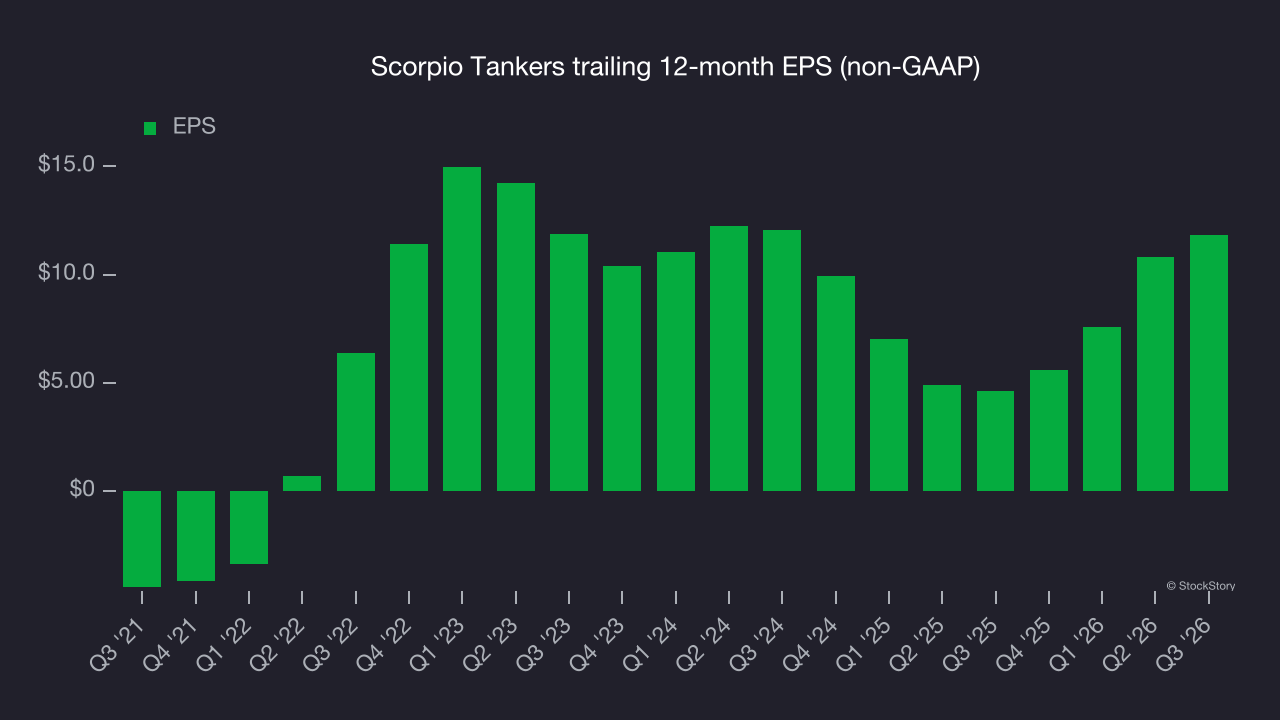
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Scorpio Tankers’s EPS and revenue declined by 1.1% and 5.8% annually over the last two years. Diminishing earnings warrant close attention, as they could imply changing secular trends and preferences. If the tide turns unexpectedly, Scorpio Tankers’s low margin of safety could leave its stock price susceptible to large downswings.
In Q3, Scorpio Tankers reported adjusted EPS of $2.49, up from $1.49 in the same quarter last year. This result came in well above analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Scorpio Tankers’s full-year EPS to shrink by 31.2% from $11.81 to $8.12, according to S&P.
Key takeaways from Scorpio Tankers’s Q3 results
Scorpio Tankers delivered a solid quarter, beating consensus estimates by a wide margin on both EBITDA and revenue. Shares rose 4.3% to $88.99 immediately after the report.
Scorpio Tankers may have had a good quarter, but that alone doesn’t make it a good investment. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Scorpio Tankers, read our full research report here (it’s free).