Kennametal’s stock price has taken a beating over the past six months, shedding 24.8% of its value and falling to $29.81 per share. This might have investors contemplating their next move.
Following the pullback, is this a buying opportunity for KMT? Find out in our full research report, it’s free.
Why does Kennametal spark debate?
Involved in manufacturing hard tips of anti-tank projectiles in World War II, Kennametal (NYSE: KMT) is a provider of industrial materials and tools for various sectors.
Two positive attributes:
1. Operating margin rising, profits up
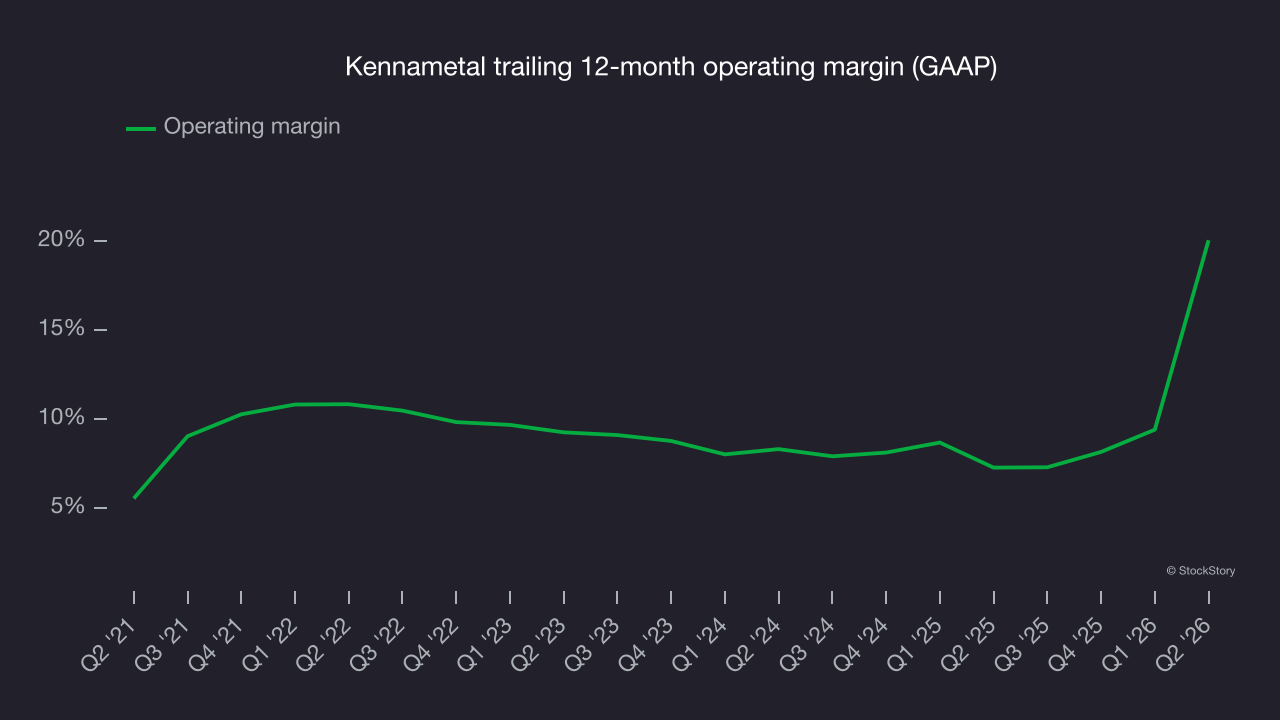
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Analyzing the trend in its profitability, Kennametal’s operating margin rose by 9.2 percentage points over the last five years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 20.1%.
2. Outstanding long-term EPS growth
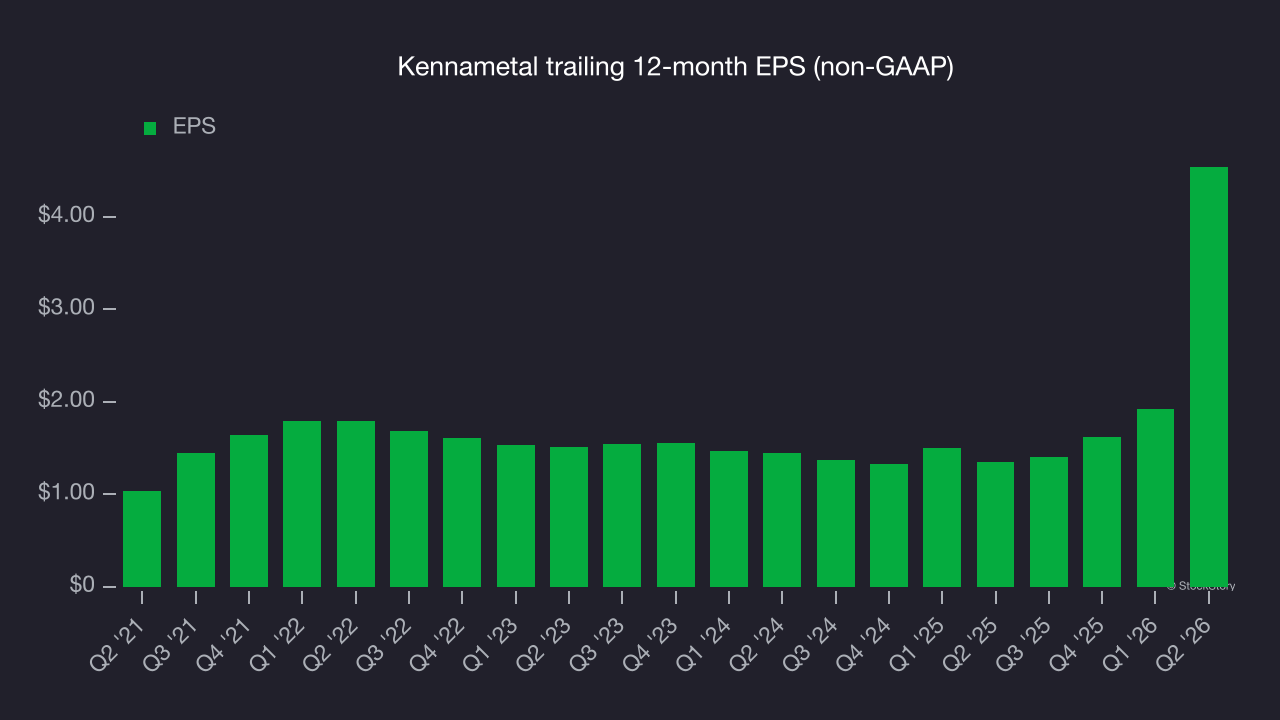
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Kennametal’s EPS grew at 34.3% compounded annual growth rate over the last five years, higher than its 5.1% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
One reason to be careful:
Slow organic growth suggests waning demand in core business
Investors interested in professional tools and equipment companies should track organic revenue in addition to reported revenue. This metric gives visibility into Kennametal’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Kennametal’s organic revenue averaged 7.2% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 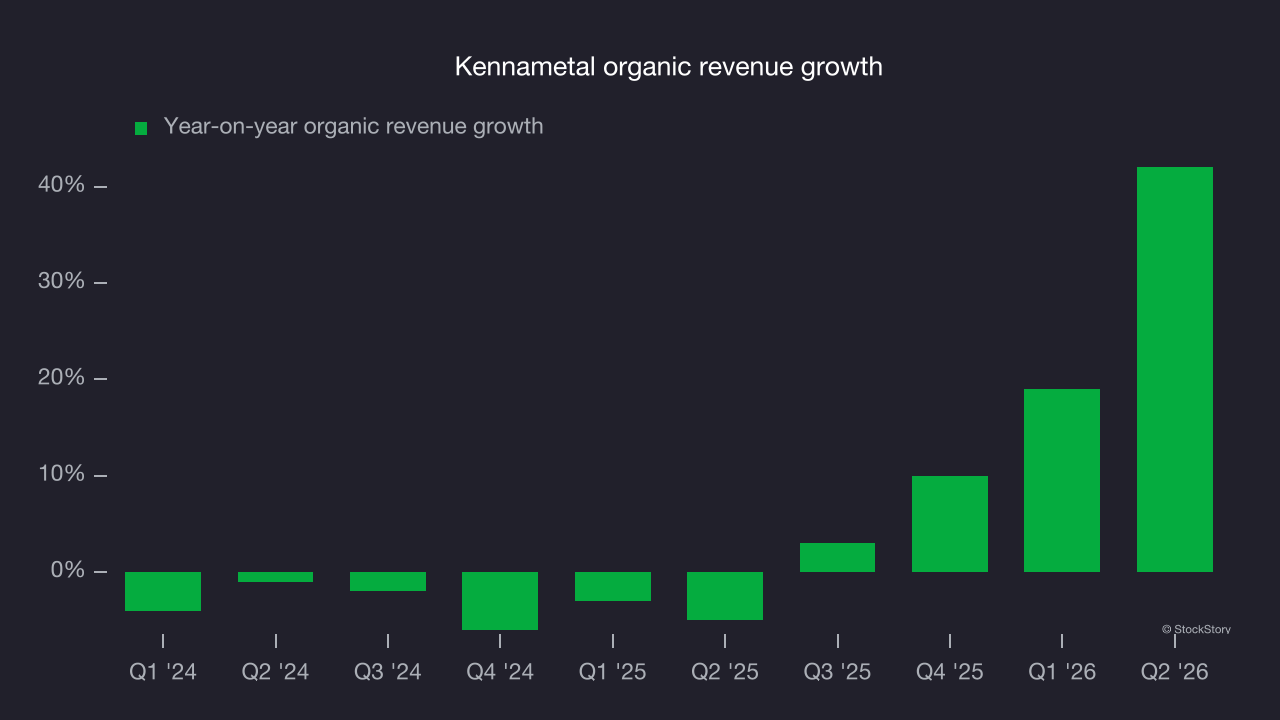
Final judgment
Kennametal has huge potential even though it has some open questions. With the recent decline, the stock trades at 5.9× forward P/E (or $29.81 per share). Is now a good time to buy? See for yourself in our in-depth research report, it’s free.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.