Shareholders of EVgo would probably like to forget the past six months even happened. The stock dropped 51.3% and now trades at $1.04. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy EVgo, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is EVgo not exciting?
Even with the cheaper entry price, we’re cautious about EVgo. Here are three reasons why EVGO doesn’t excite us, plus one stock we’d rather own.
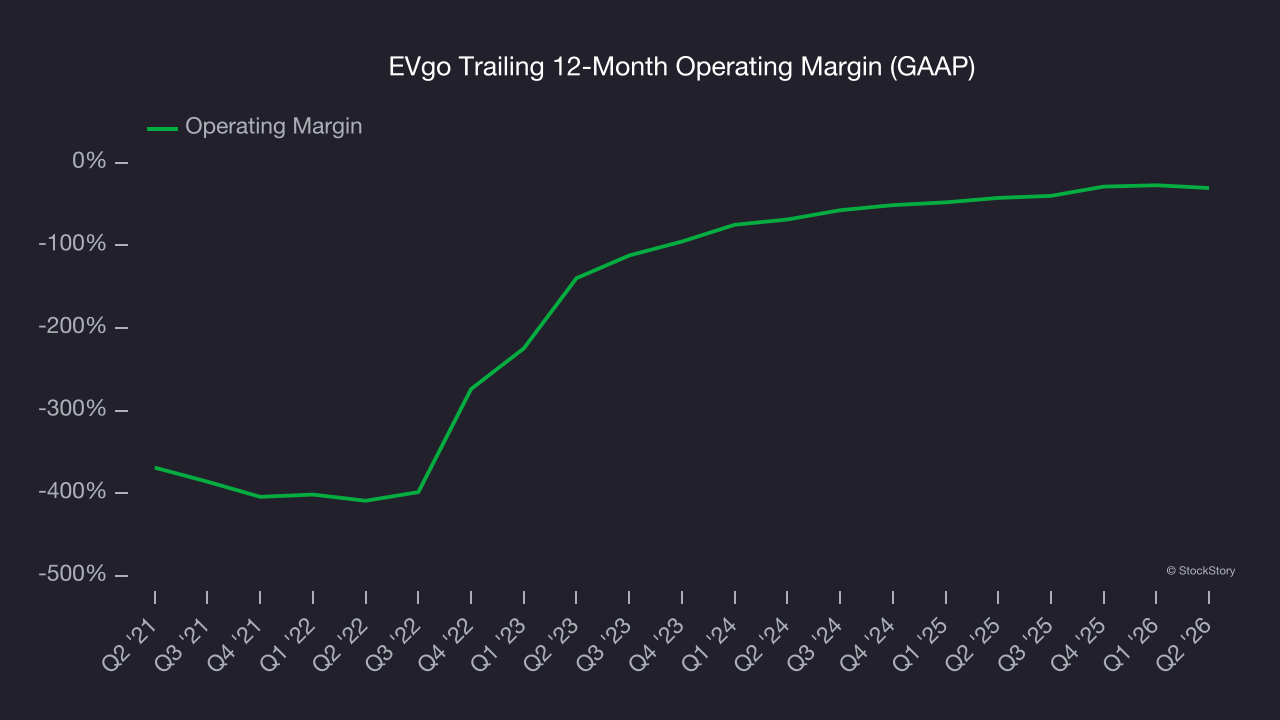
1. Operating losses sound the alarm
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
EVgo’s high expenses have contributed to an average operating margin of negative 63.8% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out. It’s hard to trust that the business can endure a full cycle.
2. Cash burn ignites concerns
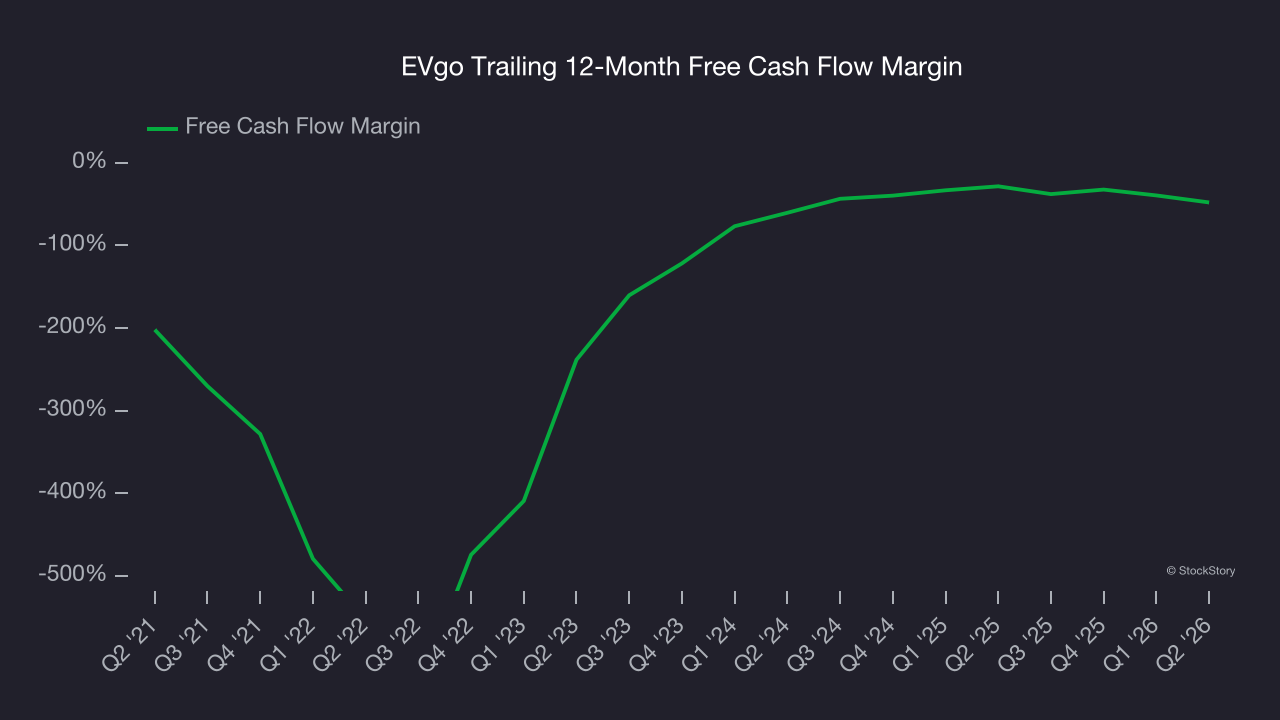
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
EVgo’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 79.4%, meaning it lit $79.42 of cash on fire for every $100 in revenue.
3. Short cash runway exposes shareholders to potential dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
EVgo burned through $193.3 million of cash over the last year. With $183.5 million of cash on its balance sheet, the company has around 11 months of runway left (assuming its $100.1 million of debt isn’t due right away).
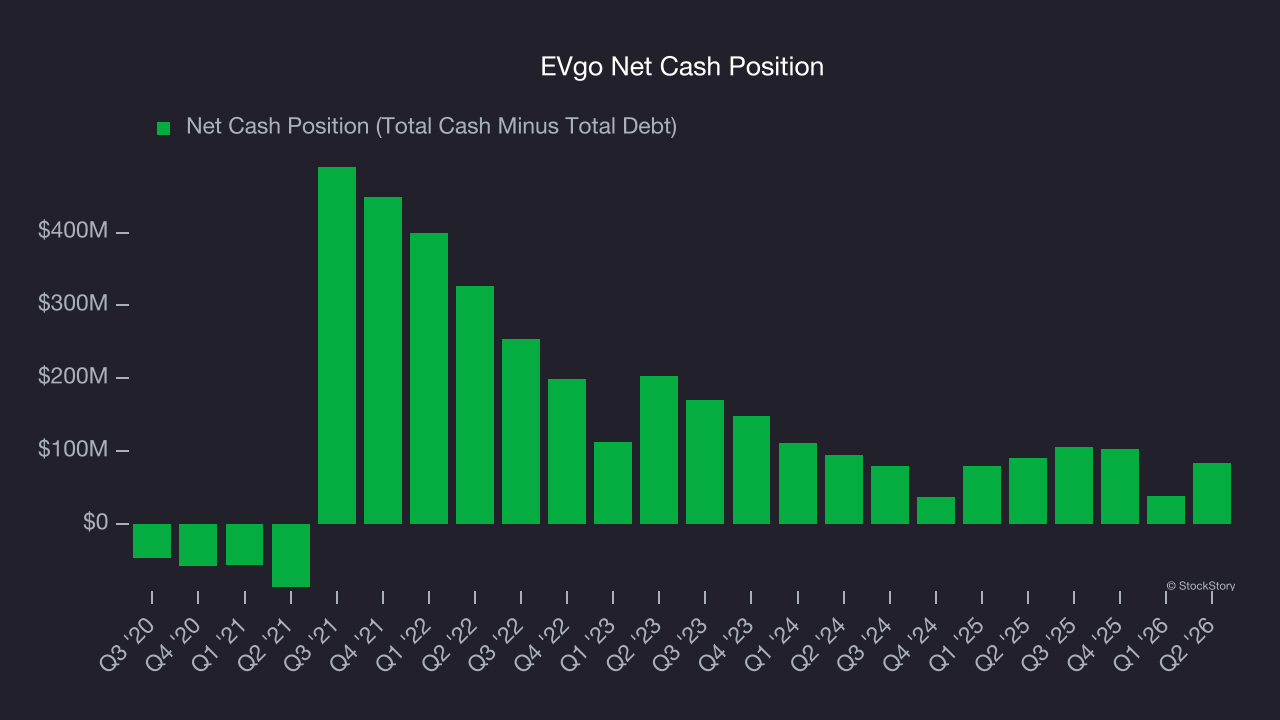
Unless the EVgo’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of EVgo until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final judgment
EVgo isn’t a terrible business, but it doesn’t pass our bar. After the recent drawdown, the stock trades at $1.04 per share (or a forward price-to-sales ratio of 0.3×). The market typically values companies like EVgo based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. Let us point you toward the most dominant software business in the world.
Stocks we would buy instead of EVgo
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.