Autodesk currently trades at $243.84 per share and has shown little upside over the past six months, posting a small loss of 1.5%. The stock also fell short of the S&P 500’s 8.1% gain during that period.
Is now the time to buy Autodesk, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why is Autodesk not exciting?
We’re passing on Autodesk for now. Here are three reasons we avoid ADSK, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
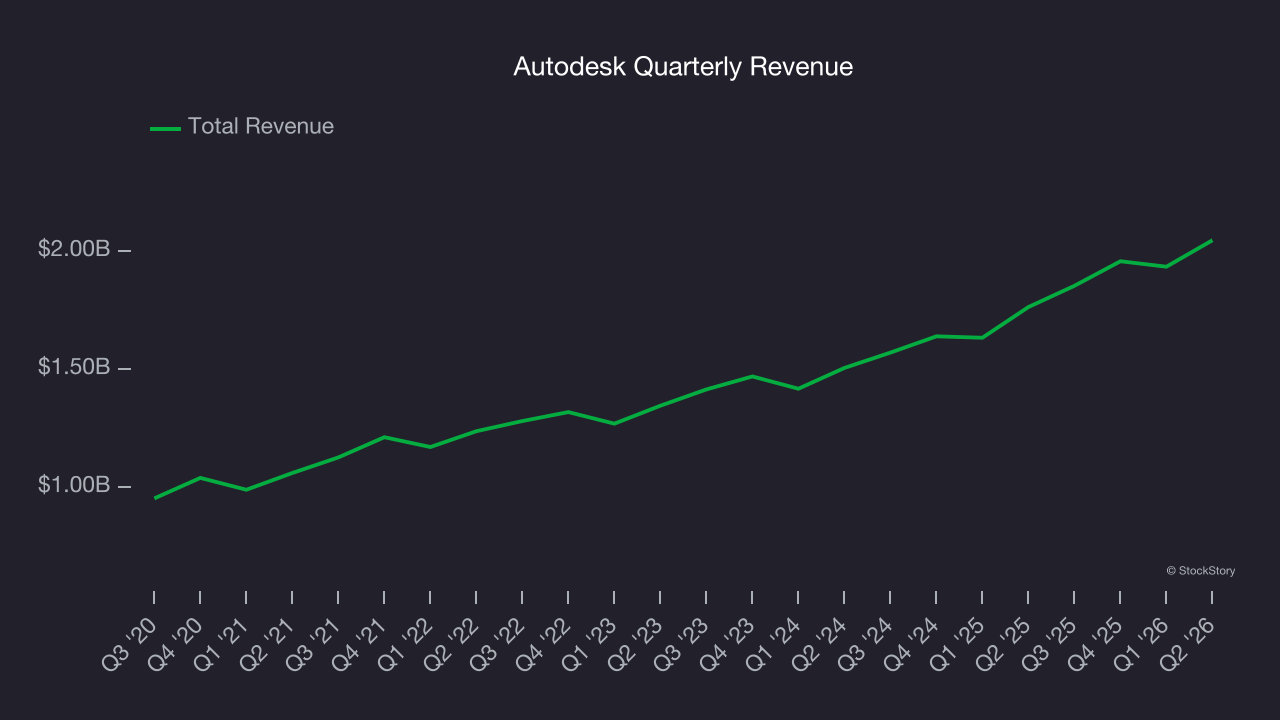
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Autodesk grew its sales at a 14% annual rate. Although this growth is acceptable on an absolute basis, it fell short of our standards for the software sector, which enjoys a number of secular tailwinds.
2. Long payback periods delay returns
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
Autodesk’s recent customer acquisition efforts haven’t yielded returns as its CAC payback period was negative this quarter, meaning its incremental sales and marketing investments outpaced its revenue. The company’s inefficiency indicates it operates in a competitive market and must continue investing to grow.
3. Cash flow margin set to decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Autodesk’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 36.4% for the last 12 months will decrease to 32.7%.
Final judgment
Autodesk isn’t a terrible business, but it doesn’t pass our quality test. With its shares underperforming the market lately, the stock trades at 5.9× forward price-to-sales (or $243.84 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks we like more than Autodesk
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.