
While the S&P 500 is up 16.6% since April 2026, Allegion (currently trading at $153.33 per share) has lagged behind, posting a return of 6.4%. This might have investors contemplating their next move.
Is ALLE a buy right now? Or is its underperformance reflective of its business quality?
Why Does ALLE Stock Spark Debate?
Allegion plc (NYSE: ALLE) is a provider of security products and solutions that keep people and assets safe and secure in various environments.
Two Positive Attributes:
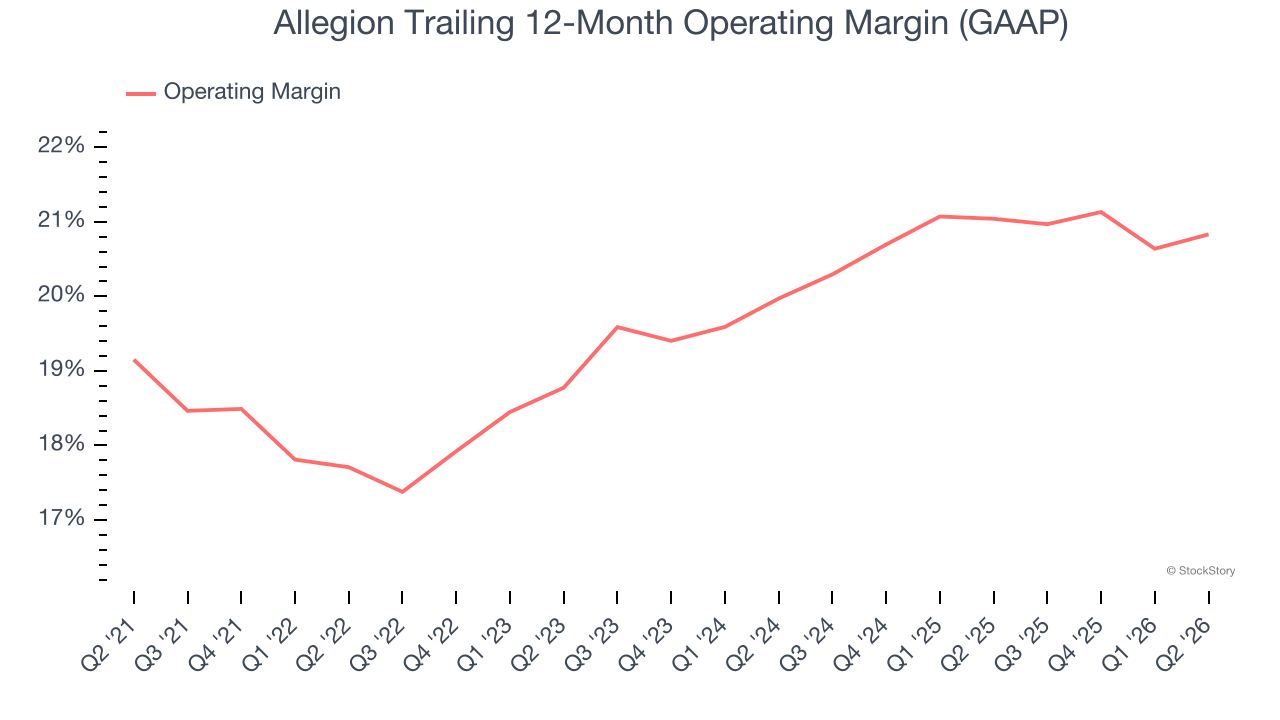
1. Operating Margin Reveals a Well-Run Organization
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Allegion has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 19.8%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
2. Increasing Free Cash Flow Margin Juices Financials
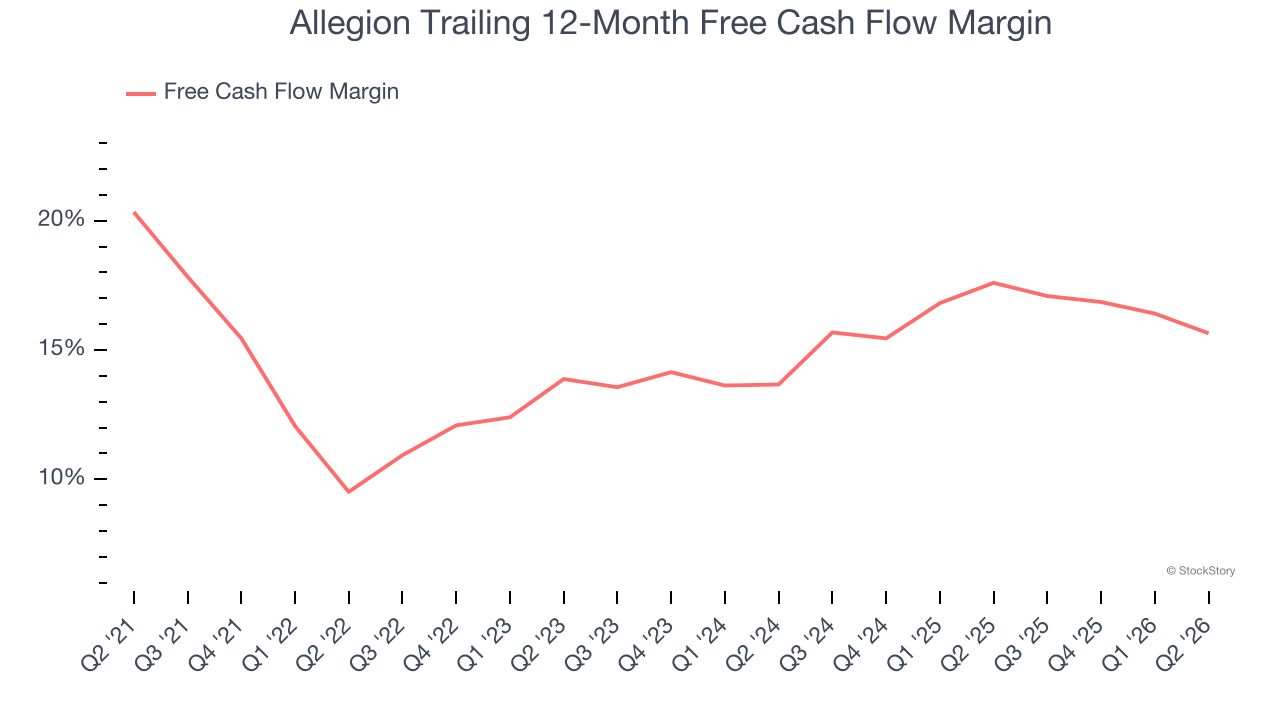
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Allegion’s margin expanded by 6.1 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Allegion’s free cash flow margin for the trailing 12 months was 15.6%.
One Reason to Be Careful:
Slow Organic Growth Suggests Waning Demand In Core Business
We can better understand Electrical Systems companies by analyzing their organic revenue. This metric gives visibility into Allegion’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Allegion’s organic revenue averaged 4.1% year-on-year growth. This performance was underwhelming and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 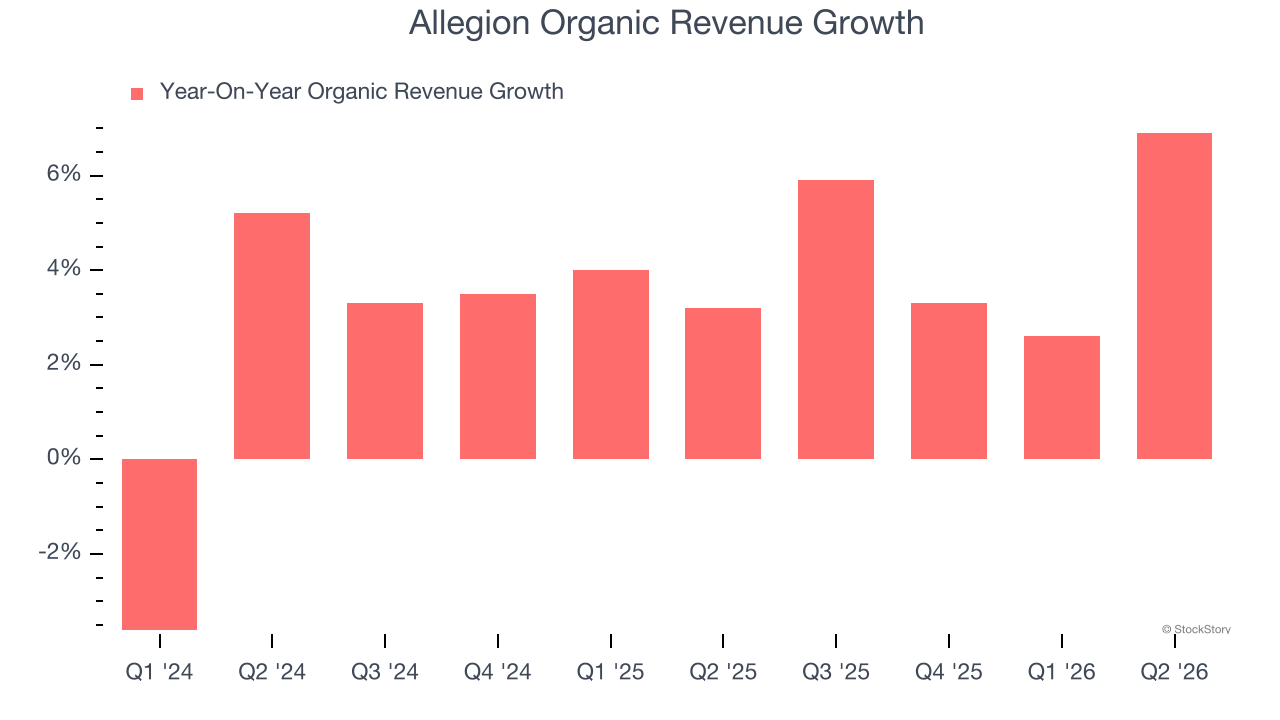
Final Judgment
Allegion’s merits more than compensate for its flaws. With its shares trailing the market in recent months, the stock trades at 16.5× forward P/E (or $153.33 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Allegion
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.