United Natural Foods has been treading water for the past six months, recording a small loss of 2.6% while holding steady at $46.87. The stock also fell short of the S&P 500’s 6.8% gain during that period.
Is now the time to buy United Natural Foods, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why do we think United Natural Foods will underperform?
We’re cautious about United Natural Foods. Here are three reasons you should be careful with UNFI, plus one stock we’d rather own.
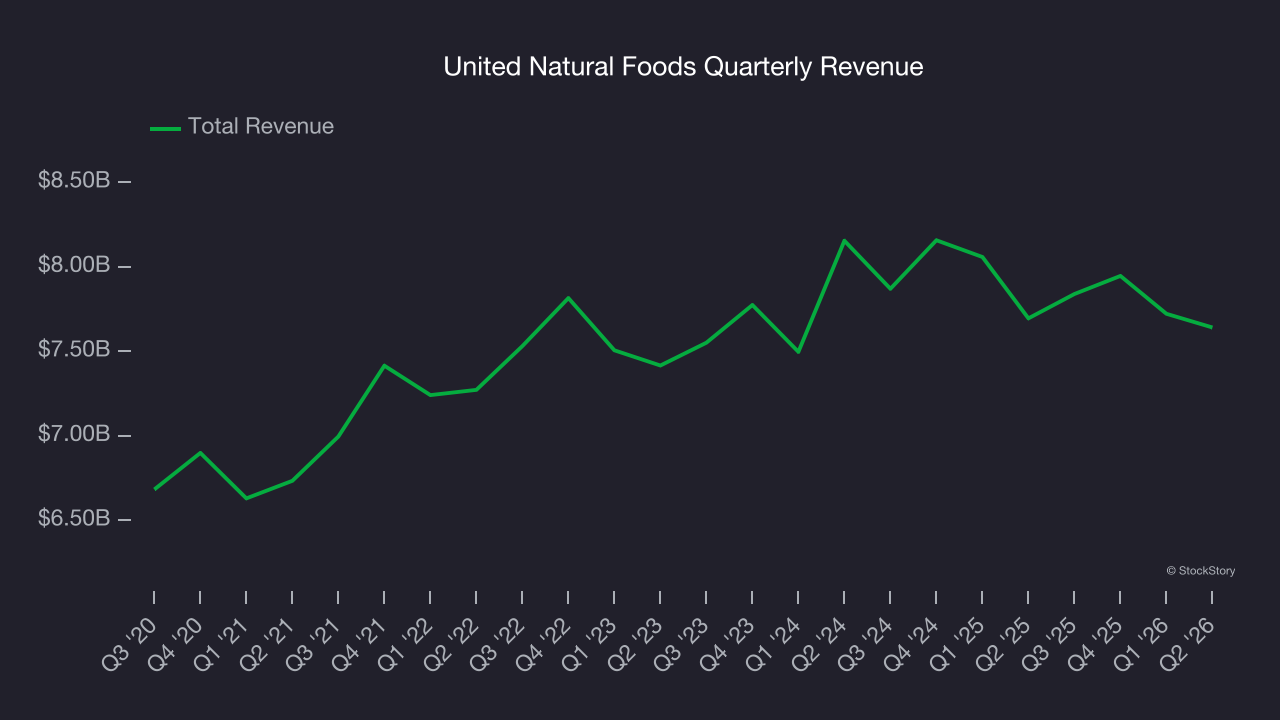
1. Long-term revenue growth flatter than a pancake
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, United Natural Foods struggled to consistently increase demand as its $31.15 billion of sales for the trailing 12 months was close to its revenue three years ago. This was below our standards and signals it’s a low quality business.
2. Low gross margin reveals weak structural profitability
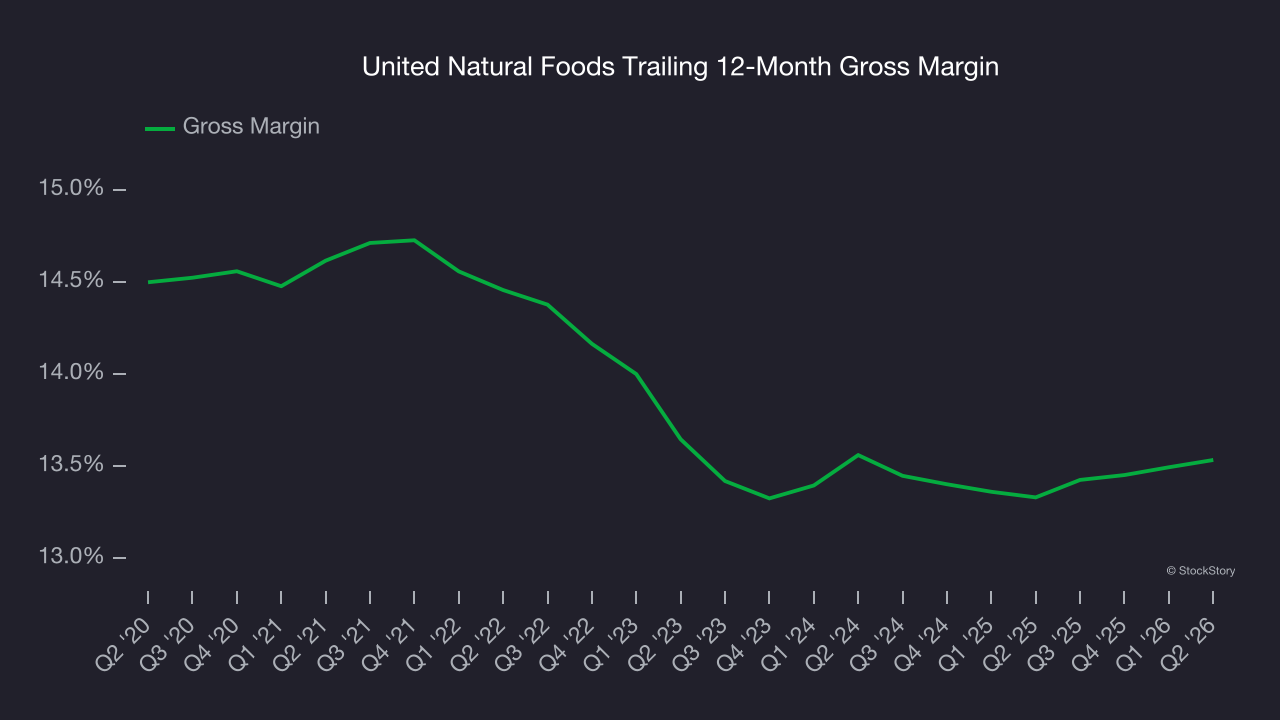
At StockStory, we prefer high gross margin businesses because they indicate pricing power or differentiated products, giving the company a chance to generate higher operating profits.
United Natural Foods has bad unit economics for a consumer staples company, signaling it operates in a competitive market and lacks pricing power because its products can be substituted. As you can see below, it averaged a 13.4% gross margin over the last two years. Said differently, for every $100 in revenue, a chunky $86.57 went towards paying for raw materials, production of goods, transportation, and distribution.
3. Previous growth initiatives haven’t impressed
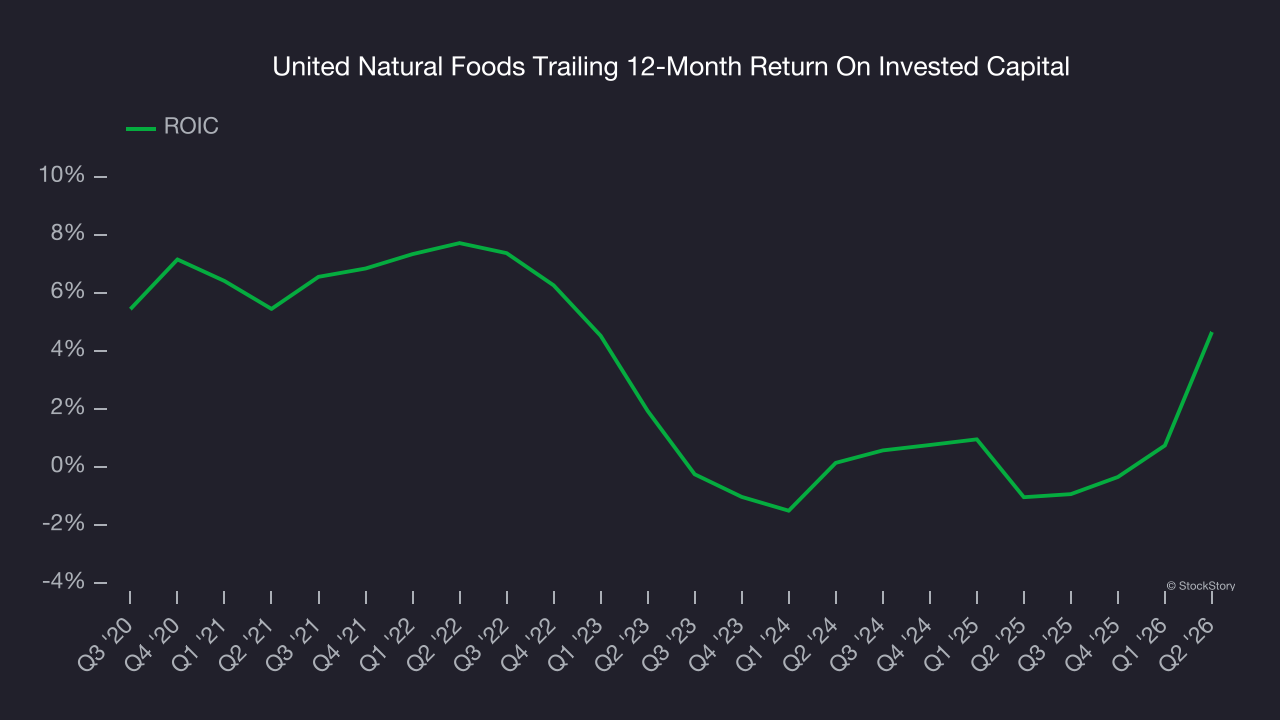
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
United Natural Foods historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 2.7%, lower than the typical cost of capital (how much it costs to raise money) for consumer staples companies.
Final judgment
We see the value of companies helping consumers, but in the case of United Natural Foods, we’re out. With its shares underperforming the market lately, the stock trades at 14.2× forward P/E (or $46.87 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. There are superior stocks to buy right now. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks we like more than United Natural Foods
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.