Financial services company Pathward Financial (NASDAQ: CASH) reported calendar Q3 2026 (fiscal Q4 2026) results beating Wall Street’s revenue expectations, but sales fell by 2.7% year on year to $183.1 million. Its GAAP profit of $1.85 per share was 13.8% above analysts’ consensus estimates.
Is now the time to buy Pathward Financial? Find out by accessing our full research report, it’s free.
Pathward Financial (CASH) Q3 CY2026 highlights:
- Net Interest Income: $117.6 million vs analyst estimates of $118.3 million (8.1% year-on-year decline, 0.6% miss)
- Net Interest Margin: 6.8% vs analyst estimates of 6.7% (12.5 basis point beat)
- Revenue: $183.1 million vs analyst estimates of $179.1 million (2.7% year-on-year decline, 2.2% beat)
- EPS (GAAP): $1.85 vs analyst estimates of $1.63 (13.8% beat)
- Tangible Book Value per Share: $24.73 vs analyst estimates of $27 (2.8% year-on-year growth, 8.4% miss)
- Market Capitalization: $1.54 billion
Chief Executive Officer Brett Pharr said, "Fiscal 2026 was another important year of execution for Pathward. We successfully advanced the strategic priorities we set out to accomplish last year, and this was no small feat. We had some major wins across each area, and are very proud of the results the team delivered. While we continue to track and manage some of the credit items we mentioned last quarter, all other areas of the business yielded positive results. We extended contracts with partners, grew noninterest income, and grew net interest income in commercial finance."
Company overview
Formerly known as Meta Financial until its 2022 rebranding, Pathward Financial (NASDAQ: CASH) provides banking-as-a-service solutions and commercial finance products, enabling partners to offer financial services like prepaid cards, payment processing, and lending options.
Sales growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities. Unfortunately, Pathward Financial’s 8.5% annualized revenue growth over the last five years was mediocre. This wasn’t a great result compared to the rest of the banking sector, but there are still things to like about Pathward Financial.
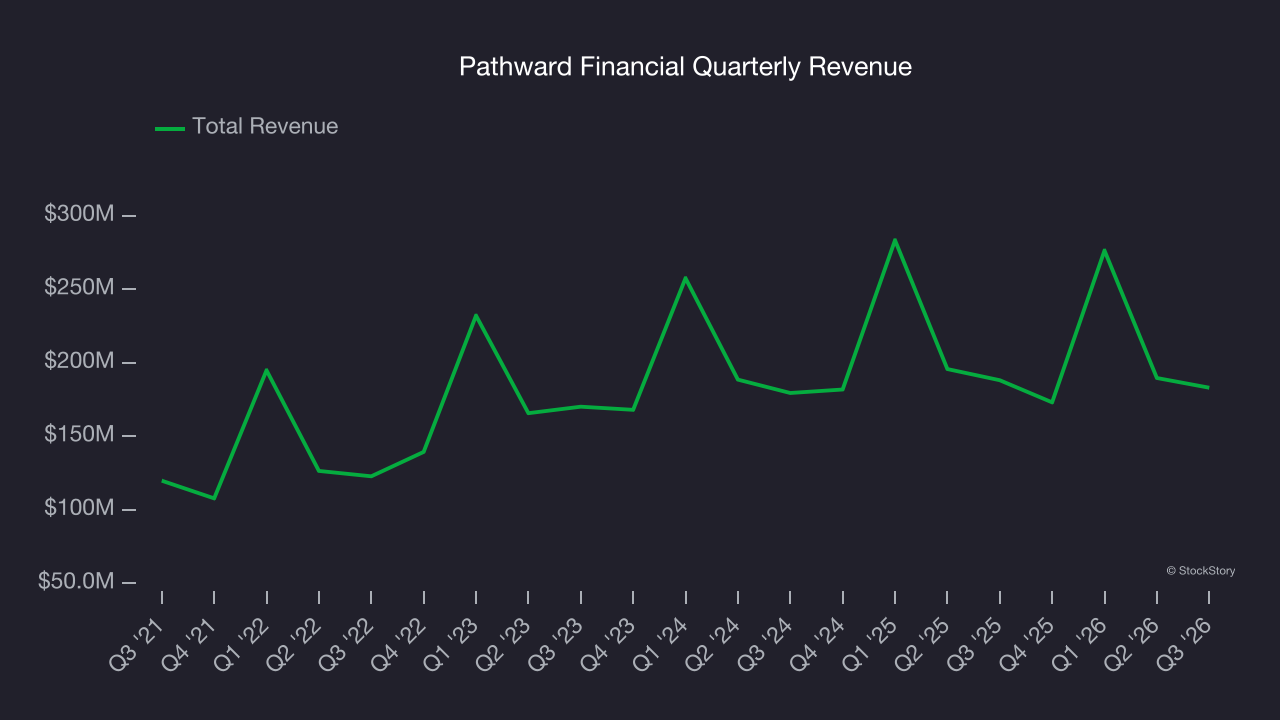
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Pathward Financial’s recent performance shows its demand has slowed as its annualized revenue growth of 1.8% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 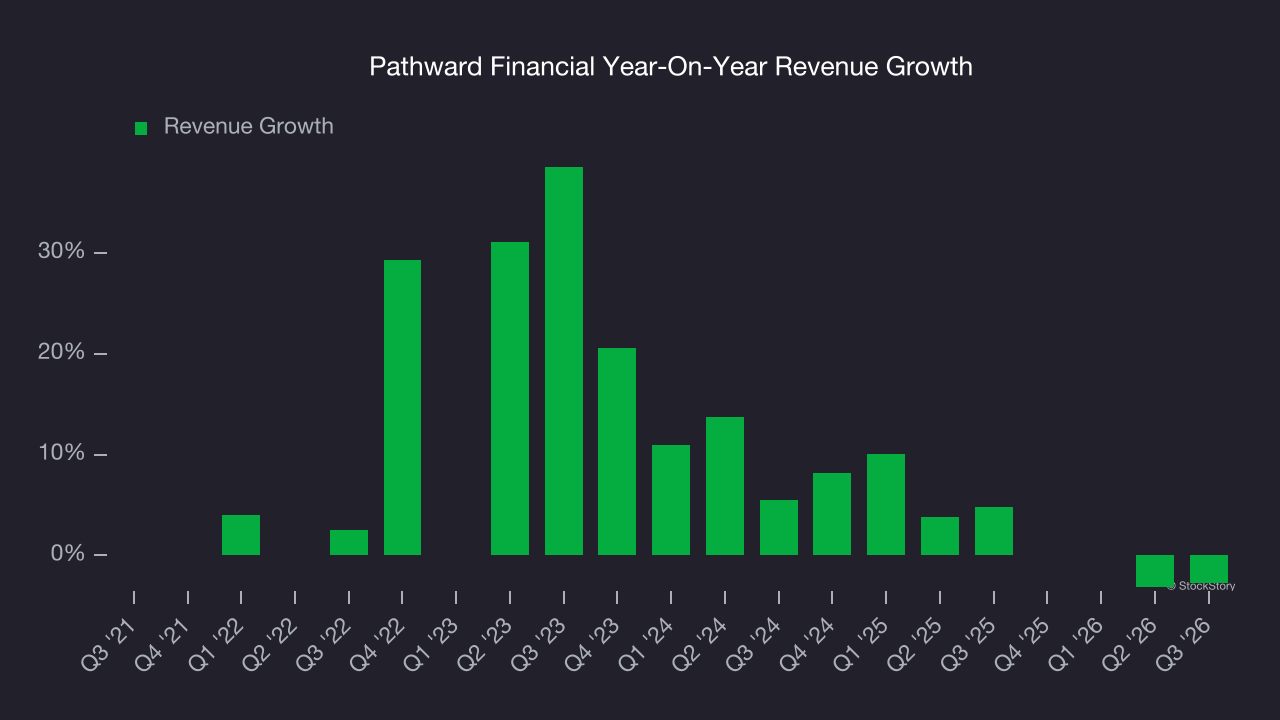 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Pathward Financial’s revenue fell by 2.7% year on year to $183.1 million but beat Wall Street’s estimates by 2.2%.
Net interest income made up 59.8% of the company’s total revenue during the last five years, meaning Pathward Financial’s growth drivers strike a balance between lending and non-lending activities.
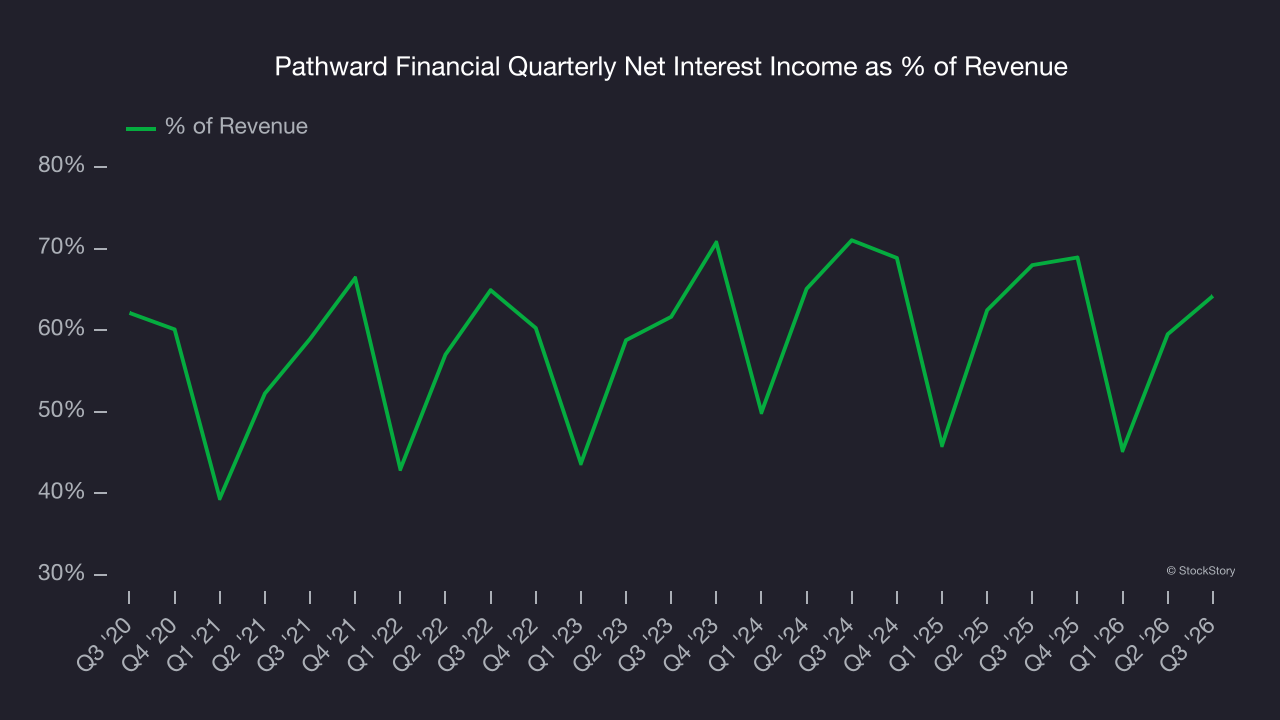
Markets consistently prioritize net interest income growth over fee-based revenue, recognizing its superior quality and recurring nature compared to the more unpredictable non-interest income streams.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Tangible book value per share (TBVPS)
Banks operate as balance sheet businesses, with profits generated through borrowing and lending activities. Valuations reflect this reality, emphasizing balance sheet strength and long-term book value compounding ability.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value by removing intangible assets of debatable liquidation worth. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
Pathward Financial’s TBVPS grew at an excellent 8.2% annual clip over the last five years. TBVPS growth has also accelerated recently, growing by 11.3% annually over the last two years from $19.98 to $24.73 per share.
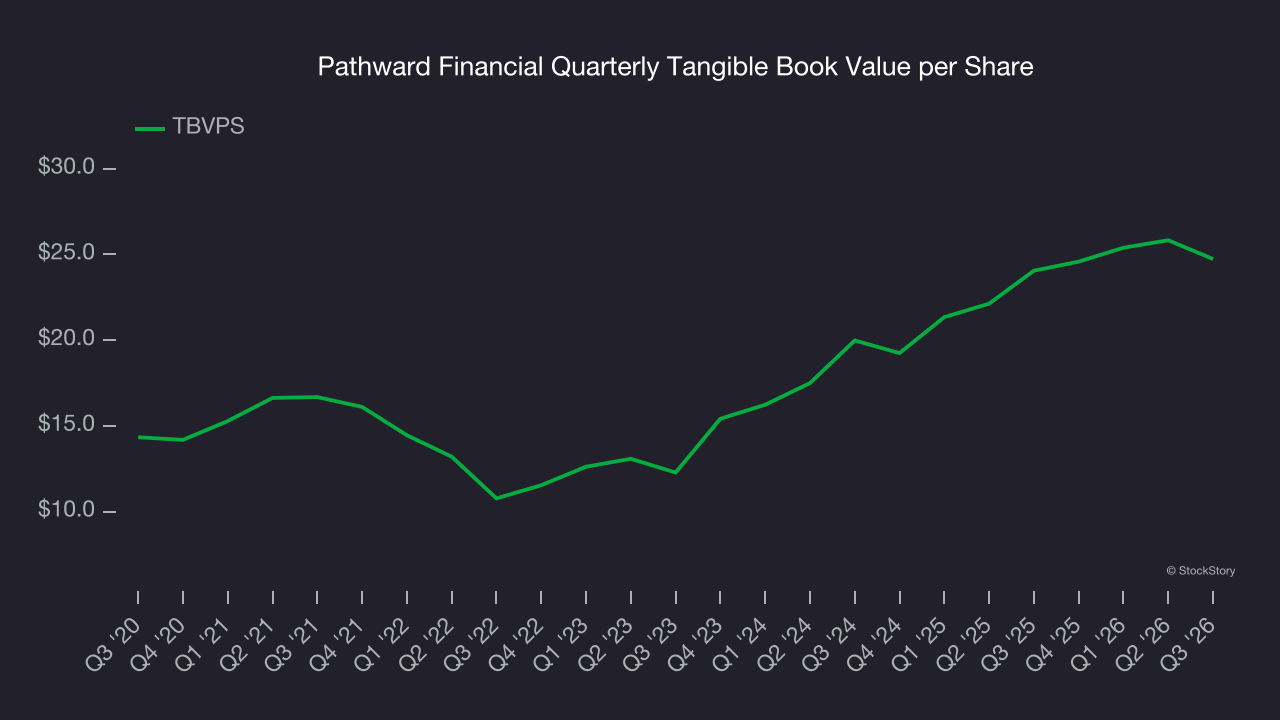
Over the next 12 months, Consensus estimates call for Pathward Financial’s TBVPS to grow by 30.9% to $32.36, elite growth rate.
Key takeaways from Pathward Financial’s Q3 results
It was good to see Pathward Financial beat analysts’ EPS expectations this quarter. We were also happy its revenue outperformed Wall Street’s estimates. On the other hand, its tangible book value per share missed and its net interest income fell slightly short of Wall Street’s estimates. Zooming out, we think this was a mixed quarter. The stock traded up 2% to $75.74 immediately following the results.
So do we think Pathward Financial is an attractive buy at the current price? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).