Office furniture manufacturer MillerKnoll (NASDAQ: MLKN) fell short of the market’s revenue expectations in Q3 CY2026, with sales falling 3.4% year on year to $923.4 million. Next quarter’s revenue guidance of $992 million underwhelmed, coming in 1.8% below analysts’ estimates. Its non-GAAP profit of $0.53 per share was 49.3% above analysts’ consensus estimates.
Is now the time to buy MillerKnoll? Find out by accessing our full research report, it’s free.
MillerKnoll (MLKN) Q3 CY2026 Highlights:
- Revenue: $923.4 million vs analyst estimates of $943.3 million (3.4% year-on-year decline, 2.1% miss)
- Adjusted EPS: $0.53 vs analyst estimates of $0.36 (49.3% beat)
- Adjusted Operating Income: $65.7 million vs analyst estimates of $49.87 million (7.1% margin, 31.7% beat)
- The company dropped its revenue guidance for the full year to $3.96 billion at the midpoint from $4.03 billion, a 1.9% decrease
- Management reiterated its full-year Adjusted EPS guidance of $2 at the midpoint
- Operating Margin: 5.6%, in line with the same quarter last year
- Backlog: $669.2 million at quarter end, down 3.1% year on year
- Market Capitalization: $1.38 billion
Company Overview
Created through the 2021 merger of industry icons Herman Miller and Knoll, MillerKnoll (NASDAQ: MLKN) designs, manufactures, and distributes interior furnishings for offices, healthcare facilities, educational settings, and homes worldwide.
Revenue Growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $3.81 billion in revenue over the past 12 months, MillerKnoll is one of the larger companies in the business services industry and benefits from a well-known brand that influences purchasing decisions.
As you can see below, MillerKnoll’s sales grew at a solid 7.7% compounded annual growth rate over the last five years. This shows it had high demand, a useful starting point for our analysis.
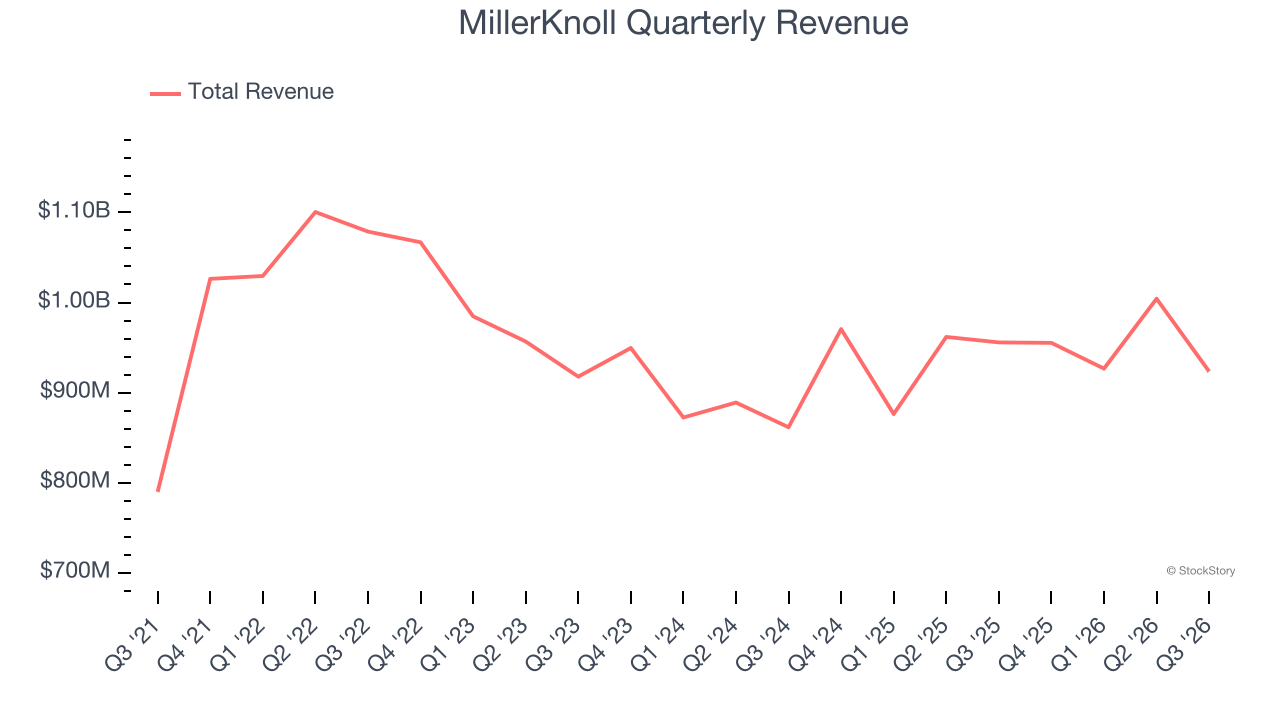
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. MillerKnoll’s recent performance shows its demand has slowed as its annualized revenue growth of 3.3% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 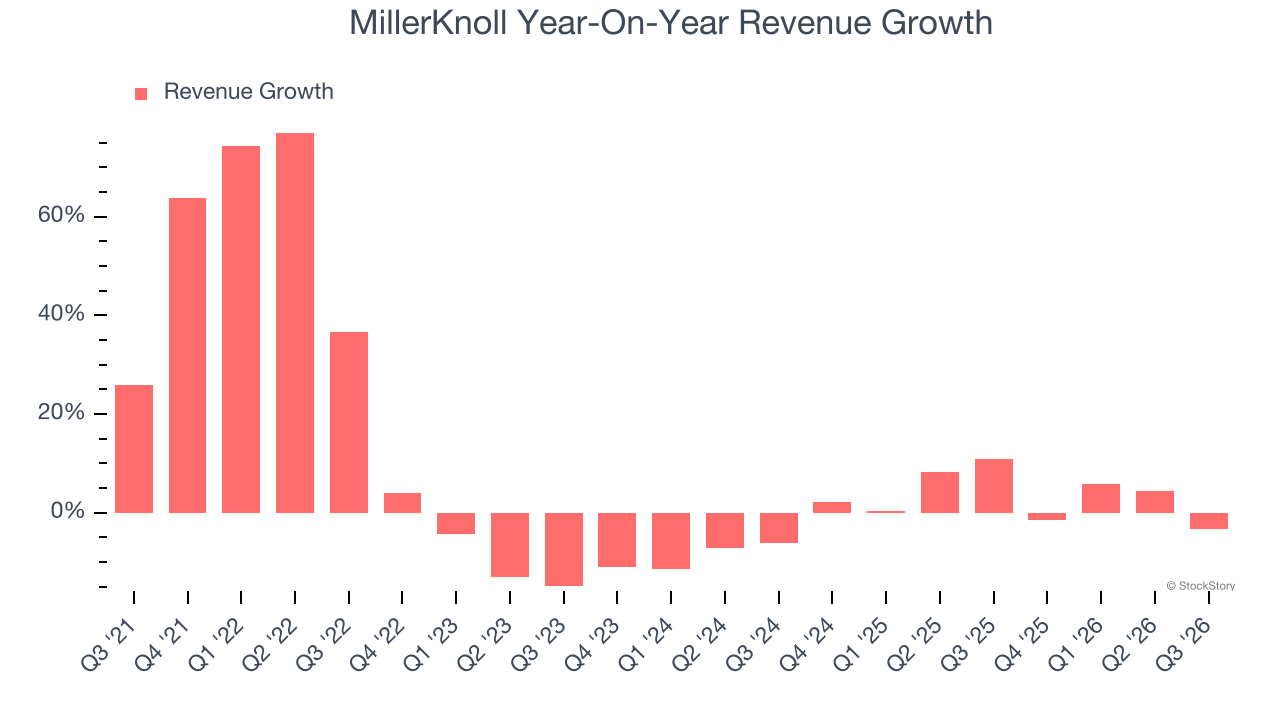
This quarter, MillerKnoll missed Wall Street’s estimates and reported a rather uninspiring 3.4% year-on-year revenue decline, generating $923.4 million of revenue. Company management is currently guiding for a 3.9% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 6.5% over the next 12 months, an improvement versus the last two years. This projection is above the sector average and indicates its newer products and services will fuel better top-line performance.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted Operating Margin
MillerKnoll’s adjusted operating margin has generally stayed the same over the last 12 months, averaging 6.5% over the last five years. This profitability was paltry for a business services business and caused by its suboptimal cost structure.
Analyzing the trend in its profitability, MillerKnoll’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
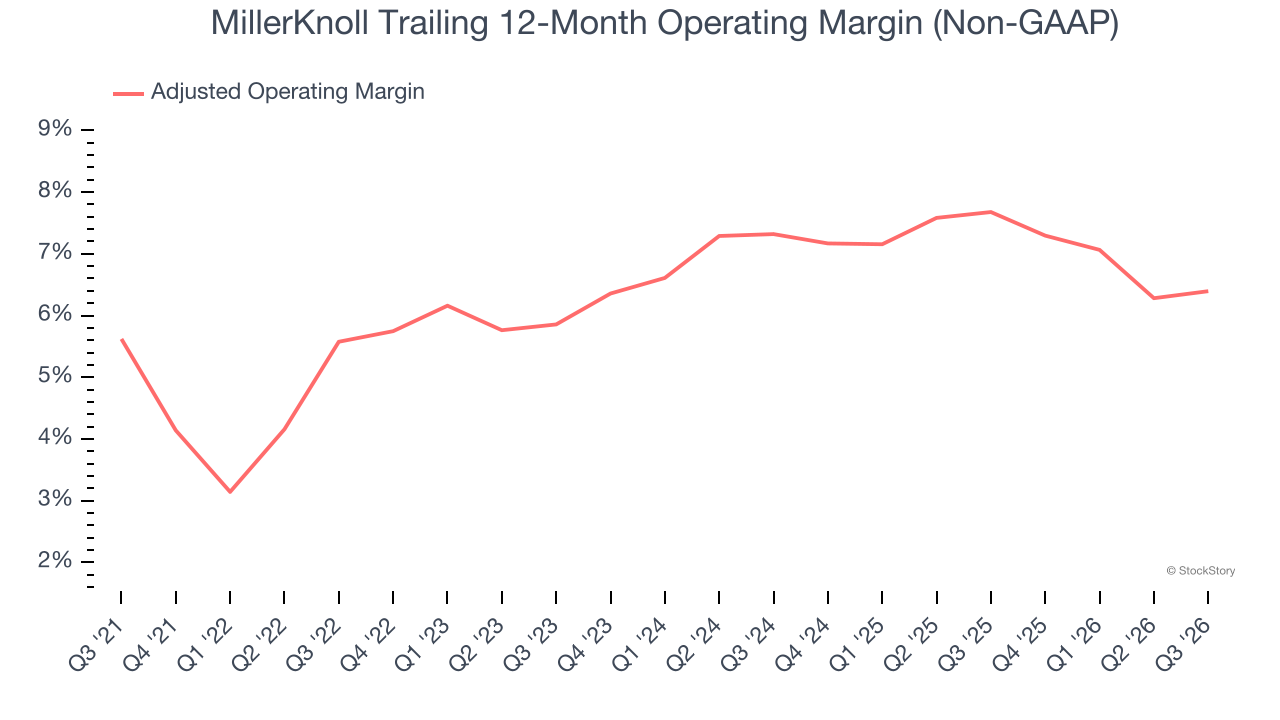
This quarter, MillerKnoll generated an adjusted operating margin profit margin of 7.1%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for MillerKnoll, its EPS declined by 5.6% annually over the last five years while its revenue grew by 7.7%. However, its adjusted operating margin actually improved during this time, telling us that non-fundamental factors such as interest expenses and taxes affected its ultimate earnings.
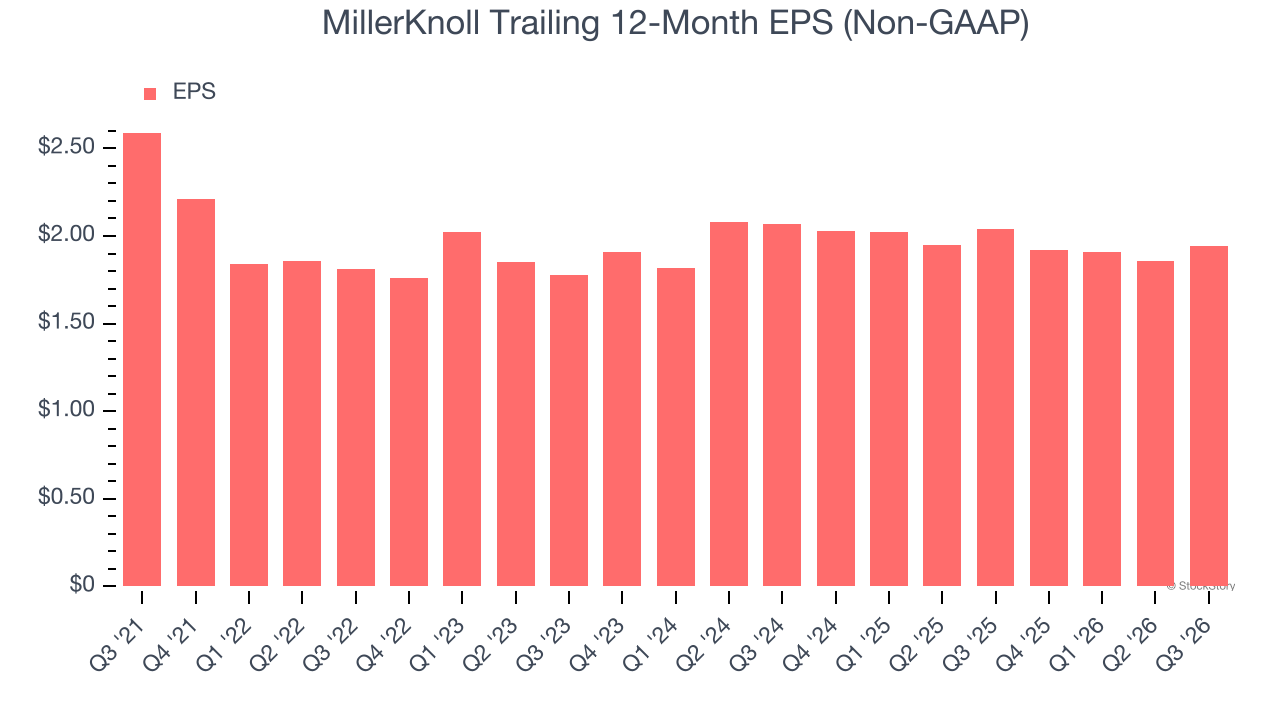
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For MillerKnoll, its two-year annual EPS declines of 3.2% show it’s still underperforming. These results were bad no matter how you slice the data.
In Q3, MillerKnoll reported adjusted EPS of $0.53, up from $0.45 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects MillerKnoll’s full-year EPS to grow 10.2% from $1.94 to $2.14.
Key Takeaways from MillerKnoll’s Q3 Results
It was good to see MillerKnoll beat analysts’ EPS expectations this quarter. We were also happy its EPS guidance for next quarter narrowly outperformed Wall Street’s estimates. On the other hand, its revenue missed and its revenue guidance for next quarter fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock traded down 3% to $19.80 immediately following the results.
MillerKnoll may have had a tough quarter, but does that actually create an opportunity to invest right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).