Cable news and media network Fox (NASDAQ: FOXA) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q1 2027), with revenue up 22.3% year on year to $4.57 billion. Its non-GAAP profit of $2.54 per share was 25.6% above analysts’ consensus estimates.
For more on FOX, read our free full research report.
FOX (FOXA) Q3 CY2026 highlights:
- Revenue $4.57 billion vs S&P analysts’ consensus estimates of $4.29 billion (22.3% year-on-year growth, 6.5% beat)
- Adjusted EPS $2.54 vs S&P analysts’ consensus estimates of $2.02 (25.6% beat)
- Adjusted EBITDA $1.64 billion vs analysts’ consensus estimates of $1.33 billion (35.9% margin, 23.1% beat)
- Operating margin 35.9%, up from 25.9% in the same quarter last year
- Free cash flow $503 million, up from -$234 million in the same quarter last year
- Market capitalization $25.12 billion
"FOX has had an outstanding start to fiscal 2027 with first-quarter records for revenue and Adjusted EBITDA underpinned by robust growth in both advertising and distribution revenue. We commenced the year with the stellar performance of the FIFA Men's World Cup, the kickoff of the college football and NFL seasons, and an active election cycle at the national and local levels. These events supported strong contributions from across the company, reflecting the focused strategy we are executing and the strength of our content and brands. These record results coupled with the strong momentum we are continuing to see across our business gives us confidence in delivering value for shareholders in a thoughtful and disciplined manner."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. FOX’s revenue grew at a weak 6.3% compounded annual growth rate over the last five years, falling short of our standard for the consumer discretionary sector.
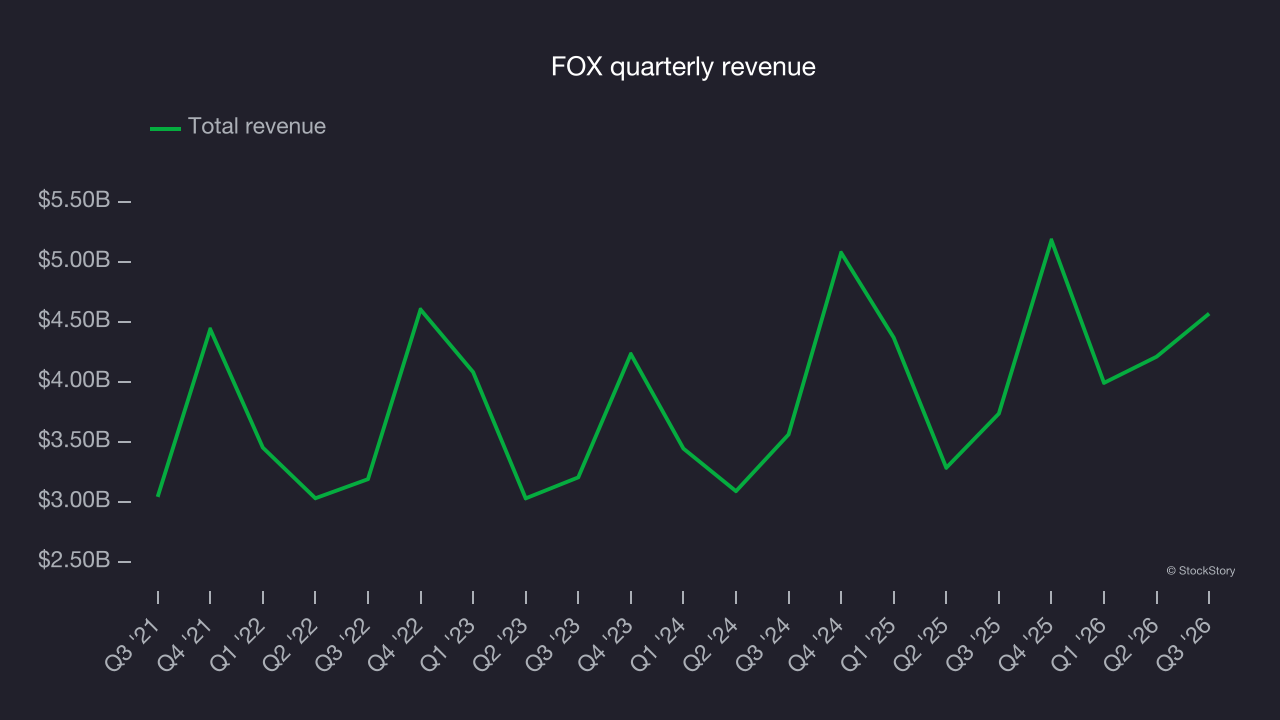
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. FOX’s annualized revenue growth of 11.9% over the last two years is above its five-year trend, a positive sign. 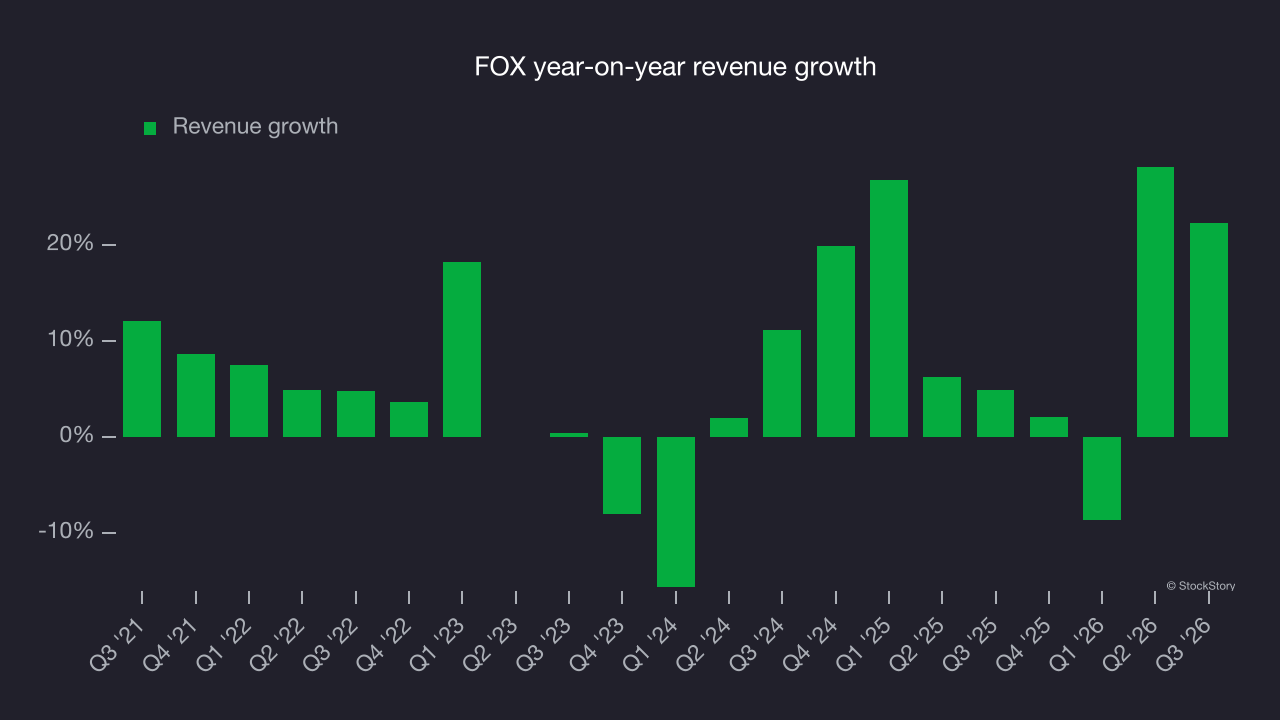
FOX’s most important segments are Advertising and Affiliate, which account for 45.5% and 45.6% of revenue, respectively. Over the last two years, FOX’s Advertising revenue (marketing services) averaged 28.4% year-on-year growth while its Affiliate revenue (licensing and retransmission fees) averaged 1.3% growth. 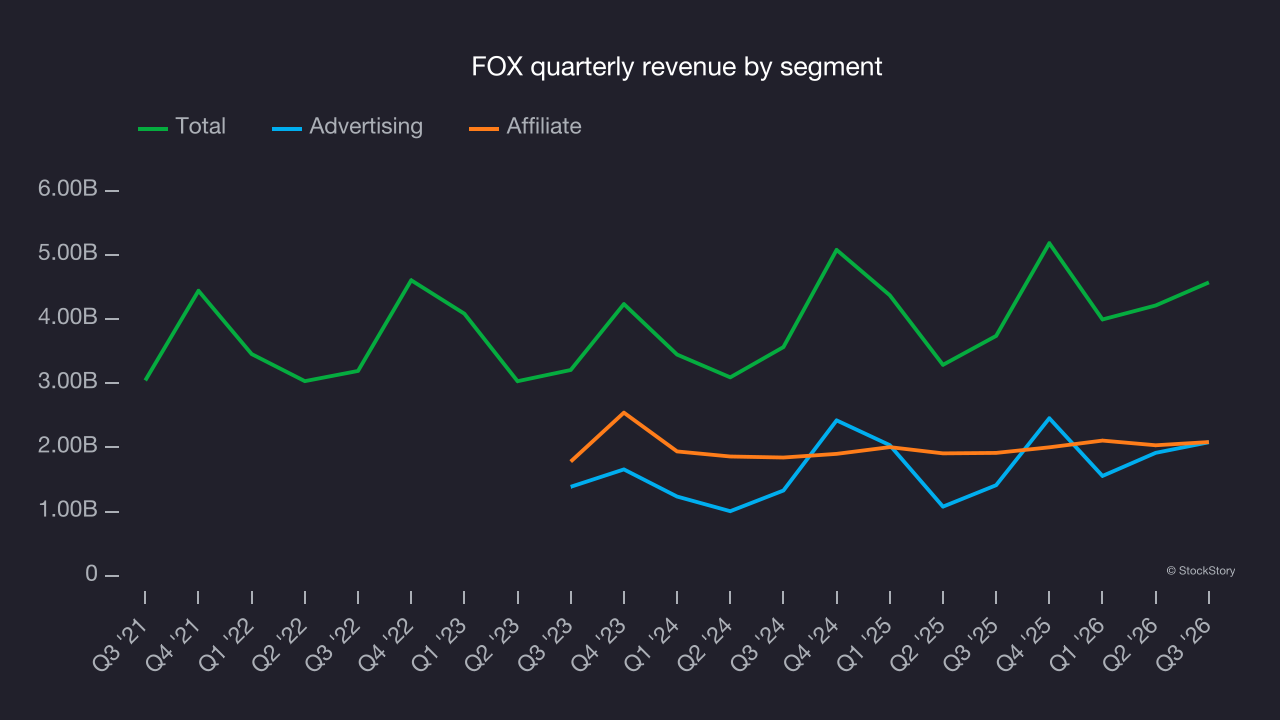
This quarter, FOX reported strong year-on-year revenue growth of 22.3%, and its $4.57 billion in revenue topped Wall Street’s consensus estimates by 6.5%.
Looking ahead, sell-side analysts expect revenue to decline by 3% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
FOX’s operating margin has been trending up over the last 12 months and averaged 21.5% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means profitability remains poor for a consumer discretionary business.
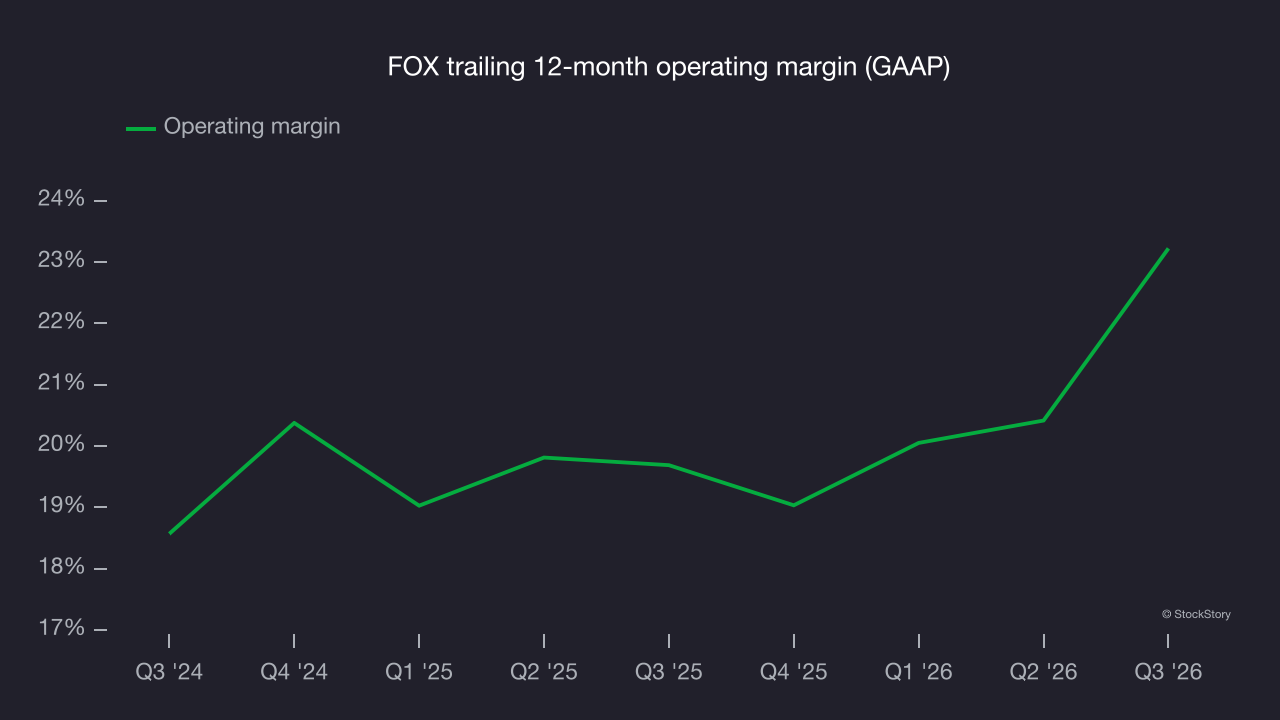
This quarter, FOX generated an operating margin of 35.9%, up 10 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason we track long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
FOX’s EPS grew at an 18.2% compounded annual growth rate over the last five years. On the positive side, this outpaced its 6.3% annualized revenue growth, indicating that the company became more profitable on a per-share basis as it expanded.
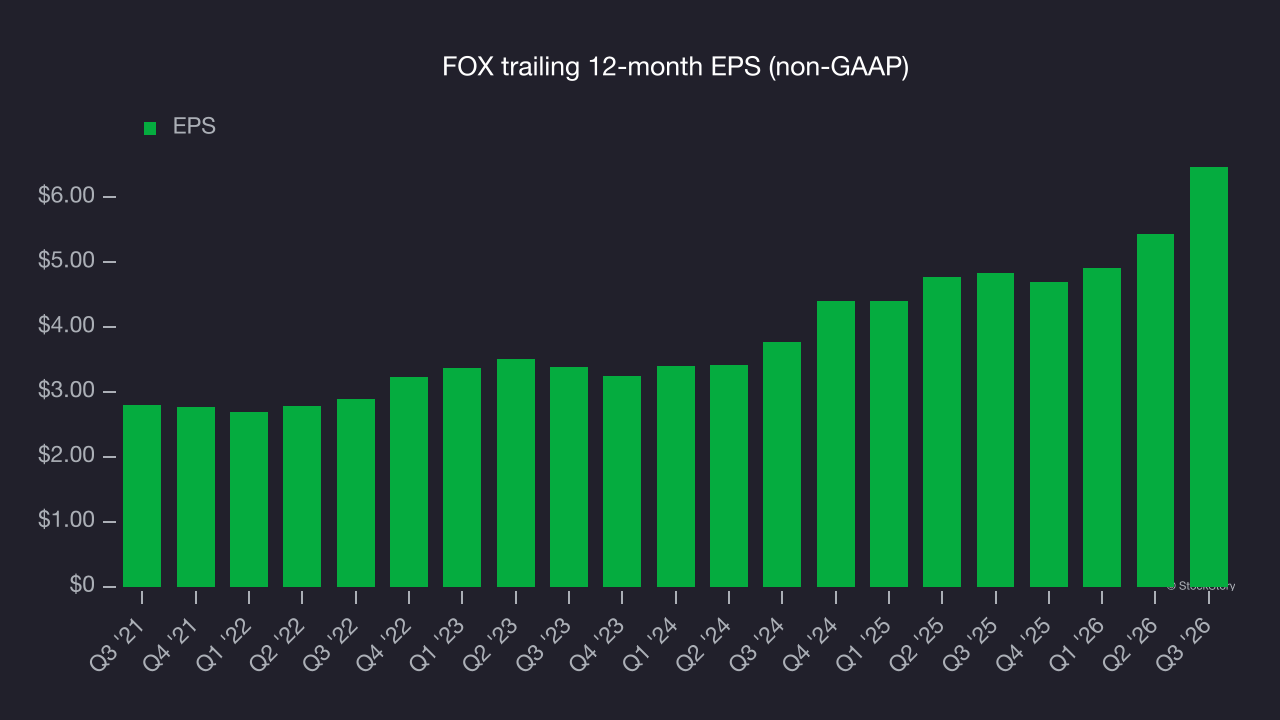
In Q3, FOX reported adjusted EPS of $2.54, up from $1.51 in the same quarter last year. This result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects FOX’s full-year EPS to shrink by 11.9% from $6.47 to $5.70, according to S&P.
Key takeaways from FOX’s Q3 results
FOX delivered a solid quarter, with EBITDA beating analysts’ consensus estimates and EPS also topping Wall Street’s estimates. Shares rose 2.5% to $64.82 immediately after the results.
FOX may have had a good quarter, but that alone does not determine whether the stock is a buy. The latest quarter matters far less than longer-term fundamentals and valuation when making that decision. Read the full research report here (it’s free).