Over the past six months, 1-800-FLOWERS’s shares (currently trading at $2.65) have posted a disappointing 19.6% loss, well below the S&P 500’s 15.2% gain. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in 1-800-FLOWERS, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think 1-800-FLOWERS Will Underperform?
Despite the more favorable entry price, we’re cautious about 1-800-FLOWERS. Here are three reasons why there are better opportunities than FLWS, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
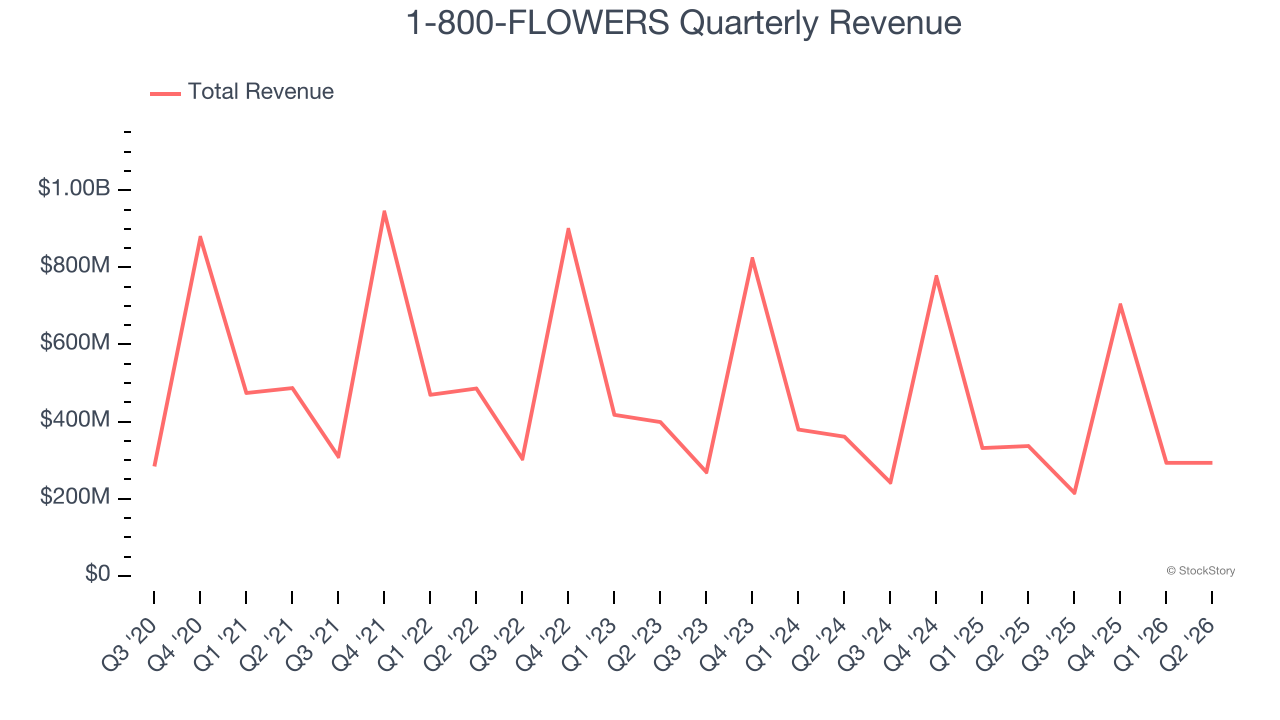
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, 1-800-FLOWERS’s demand was weak and its revenue declined by 6.7% per year. This wasn’t a great result and is a sign of poor business quality.
2. New Investments Fail to Bear Fruit as ROIC Declines
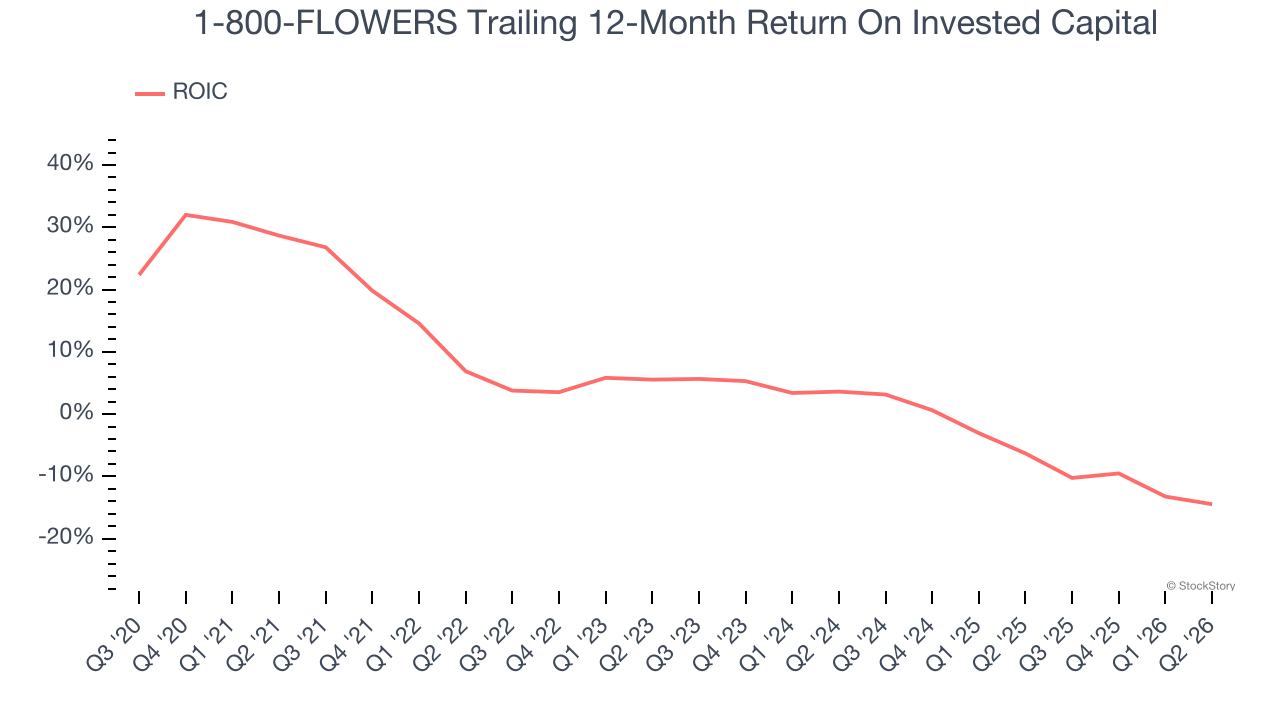
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, 1-800-FLOWERS’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
3. Short Cash Runway Exposes Shareholders to Potential Dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
1-800-FLOWERS burned through $12.97 million of cash over the last year, and its $248.9 million of debt exceeds the $11.37 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
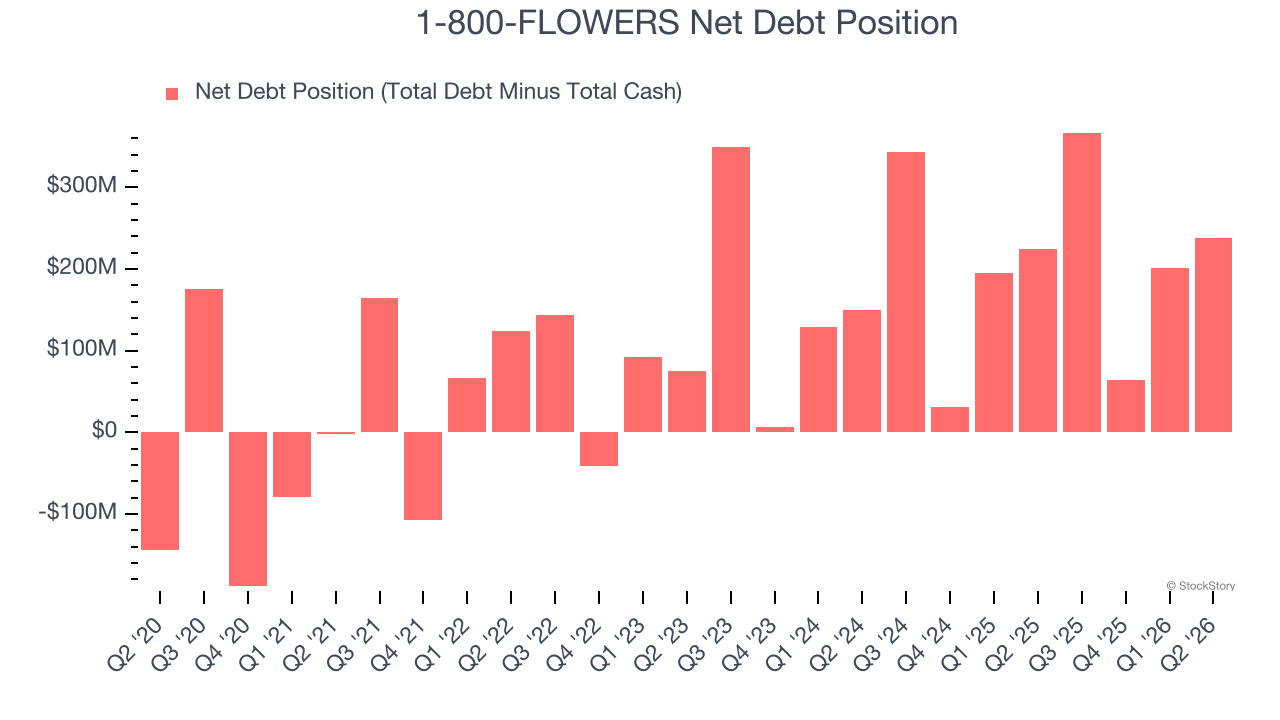
Unless the 1-800-FLOWERS’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of 1-800-FLOWERS until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final Judgment
We see the value of companies helping consumers, but in the case of 1-800-FLOWERS, we’re out. After the recent drawdown, the stock trades at 29.1× forward EV-to-EBITDA (or $2.65 per share). This multiple tells us a lot of good news is priced in - we think there are better opportunities elsewhere. We’d suggest looking at one of our top software and edge computing picks.
Stocks We Would Buy Instead of 1-800-FLOWERS
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.