Digital infrastructure provider Applied Digital (NASDAQ: APLD) reported calendar Q3 2026 (fiscal Q1 2027) results beating Wall Street’s revenue expectations, with sales up 322% year on year to $341.9 million. Its non-GAAP loss of $0.01 per share was 96.7% above analysts’ consensus estimates.
Is now the time to buy Applied Digital? Find out by accessing our full research report, it’s free.
Applied Digital (APLD) Q3 CY2026 Highlights:
- Revenue: $341.9 million vs analyst estimates of $135.3 million (322% year-on-year growth, 153% beat)
- Adjusted EPS: -$0.01 vs analyst estimates of -$0.30 (96.7% beat)
- Adjusted EBITDA: $64.41 million vs analyst estimates of $39.79 million (18.8% margin, 61.9% beat)
- Operating Margin: -18.2%
- Free Cash Flow was -$2.01 billion compared to -$331.4 million in the same quarter last year
- Market Capitalization: $7.39 billion
“Our goal is to establish Applied Digital as the category leader in the design, construction, deployment, and operation of purpose-built AI factories,” said Wes Cummins, Chairman and Chief Executive Officer of Applied Digital. “We are building for the long term, with a clear focus on developing large-scale, sustainable AI factory campuses and securing durable, high-quality, long-term contracts with proven, tier-one, investment grade hyperscalers that are leaders in the AI industry.”
Company Overview
Pivoting from its origins in cryptocurrency mining to become a key player in the AI infrastructure boom, Applied Digital (NASDAQ: APLD) designs and operates specialized data centers that provide high-performance computing infrastructure for artificial intelligence and blockchain applications.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $872.3 million in revenue over the past 12 months, Applied Digital is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels. On the bright side, it can grow faster because it has more room to expand.
As you can see below, Applied Digital’s 168% annualized revenue growth over the last four years was incredible. This shows it had high demand, a useful starting point for our analysis.
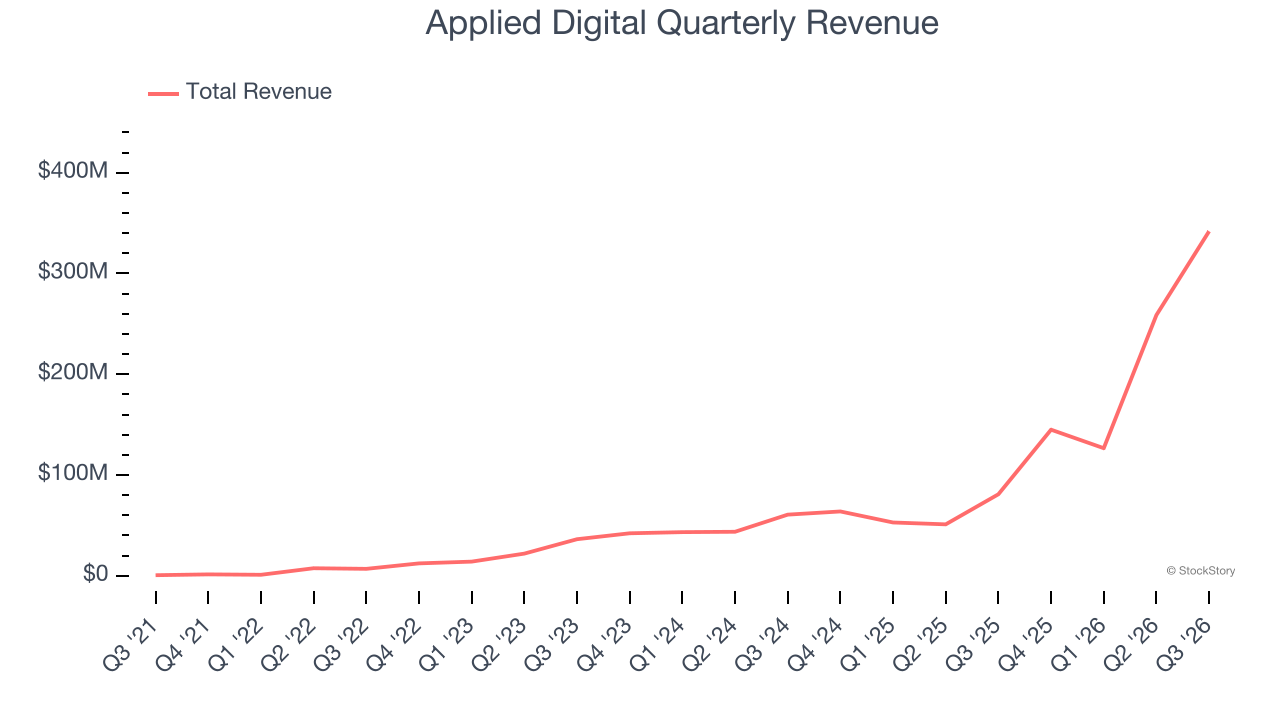
We at StockStory place the most emphasis on long-term growth, but within business services, a stretched historical view may miss recent innovations or disruptive industry trends. Applied Digital’s annualized revenue growth of 114% over the last two years is below its four-year trend, but we still think the results suggest healthy demand. 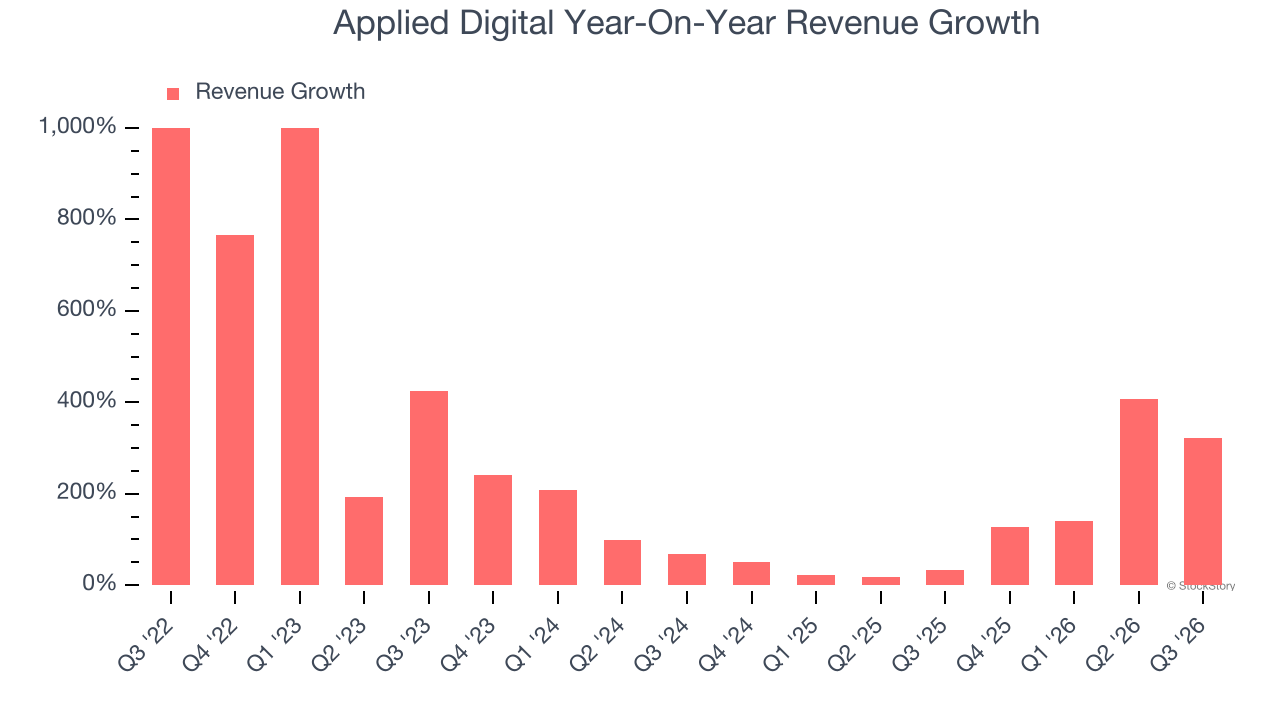
This quarter, Applied Digital reported magnificent year-on-year revenue growth of 322%, and its $341.9 million of revenue beat Wall Street’s estimates by 153%.
Looking ahead, sell-side analysts expect revenue to grow 46% over the next 12 months, a deceleration versus the last two years. Still, this projection is healthy and implies the market is forecasting success for its products and services.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted Operating Margin
Applied Digital was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 1.6% was weak for a business services business.
On the plus side, Applied Digital’s adjusted operating margin rose by 66.6 percentage points over the last five years, as its sales growth gave it immense operating leverage.
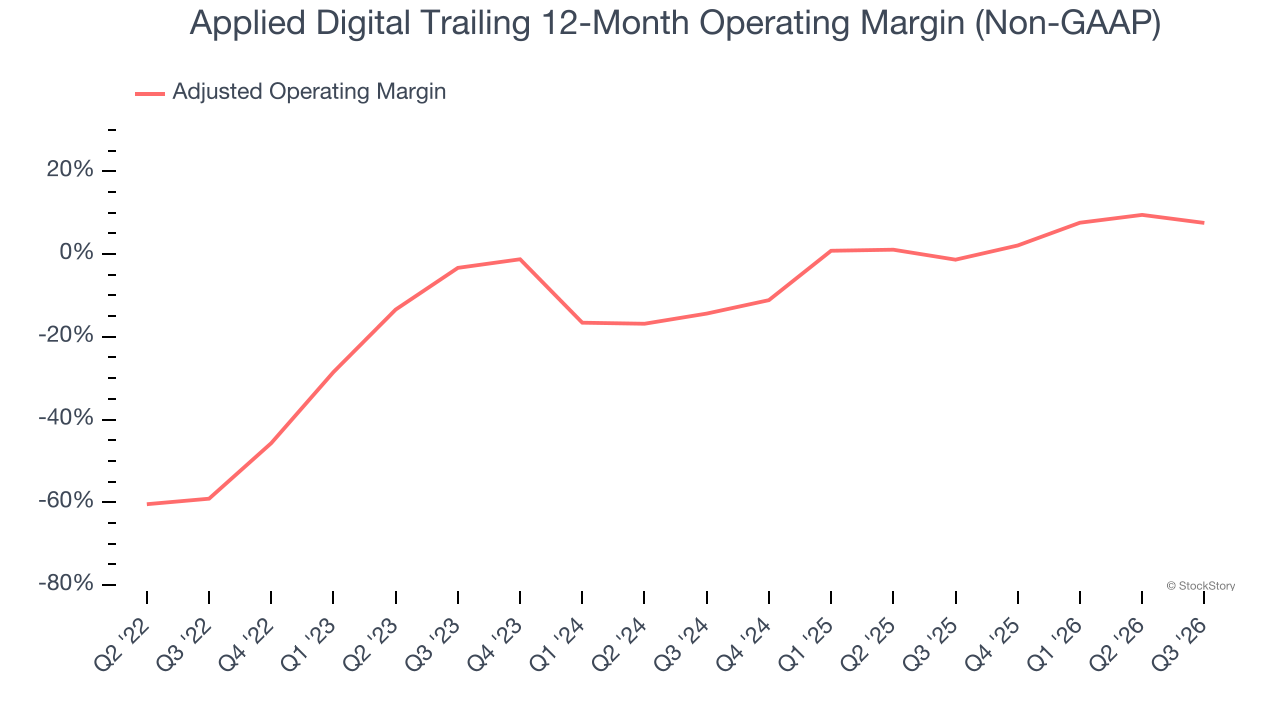
This quarter, Applied Digital generated an adjusted operating margin profit margin of 1.2%.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Applied Digital’s full-year EPS flipped from negative to positive over the last four years. This is a good sign and shows it’s at an inflection point.
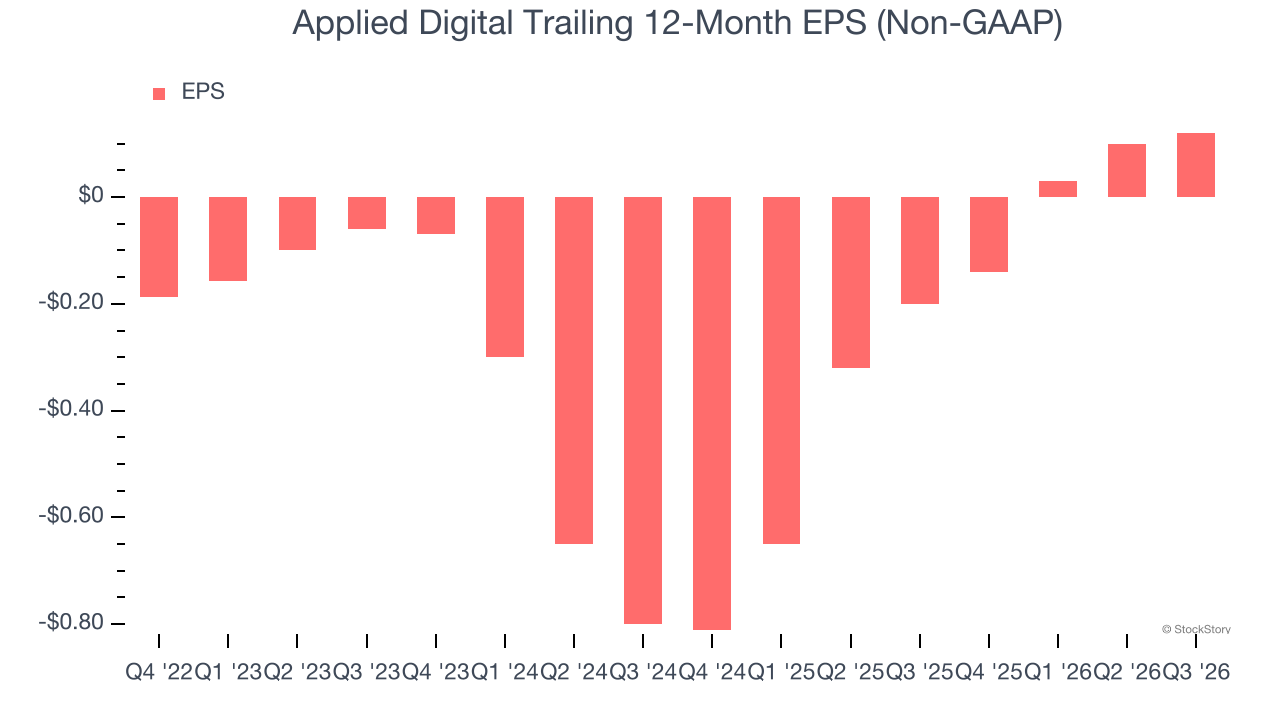
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Applied Digital, its two-year annual EPS growth of 46.6% was higher than its four-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, Applied Digital reported adjusted EPS of negative $0.01, up from negative $0.03 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Applied Digital to perform poorly. Analysts forecast its full-year EPS will invert from $0.12 to negative $0.98. This is unusual as its revenue and operating margin are anticipated to increase, signaling the fall likely stems from “below-the-line” items such as taxes.
Key Takeaways from Applied Digital’s Q3 Results
It was good to see Applied Digital beat analysts’ EPS expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The stock traded up 1.6% to $24.30 immediately following the results.
Sure, Applied Digital had a solid quarter, but if we look at the bigger picture, is this stock a buy? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).