Manufacturing services provider Proto Labs (NYSE: PRLB) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 14% year on year to $154.3 million. Guidance for next quarter’s revenue was better than expected at $147 million at the midpoint, 1.6% above analysts’ consensus estimates. Its non-GAAP profit of $0.63 per share was 5.7% above analysts’ consensus estimates.
For more on Proto Labs, read our free full research report.
Proto Labs (PRLB) Q3 2026 highlights:
- Revenue $154.3 million vs S&P analysts’ consensus estimates of $149 million (14% year-on-year growth, 3.6% beat)
- Adjusted EPS $0.63 vs S&P analysts’ consensus estimates of $0.60 (5.7% beat)
- Revenue guidance $147 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $144.7 million
- Adjusted EPS guidance $0.50 at the midpoint for Q4 2026, above analysts’ consensus estimates of $0.48
- Operating margin 9.4%, up from 6.5% in the same quarter last year
- Free cash flow margin 11%, down from 18.5% in the same quarter last year
- Market capitalization $2.17 billion
"Protolabs delivered another record quarter, with double-digit revenue growth for the fourth consecutive quarter," said Suresh Krishna, President and Chief Executive Officer. "Our momentum reflects strong execution and growing demand from industries that value speed, quality, and manufacturing agility. As reindustrialization, advanced hardware innovation, and the need for resilient supply chains reshape manufacturing, our digital model enables customers to move quickly from idea to production — positioning us to deliver sustained profitable growth and long-term shareholder value."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Proto Labs’s revenue grew at a sluggish 4.3% annualized rate over the last five years, falling short of the industrials sector benchmark.
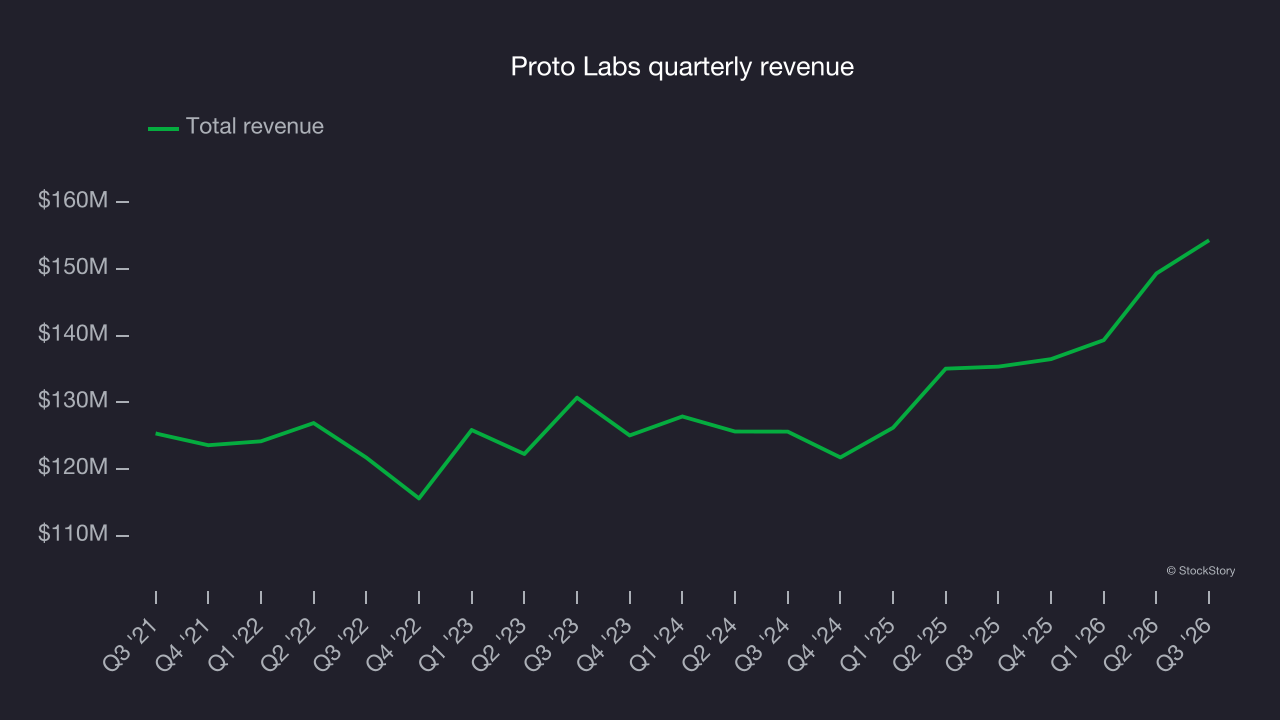
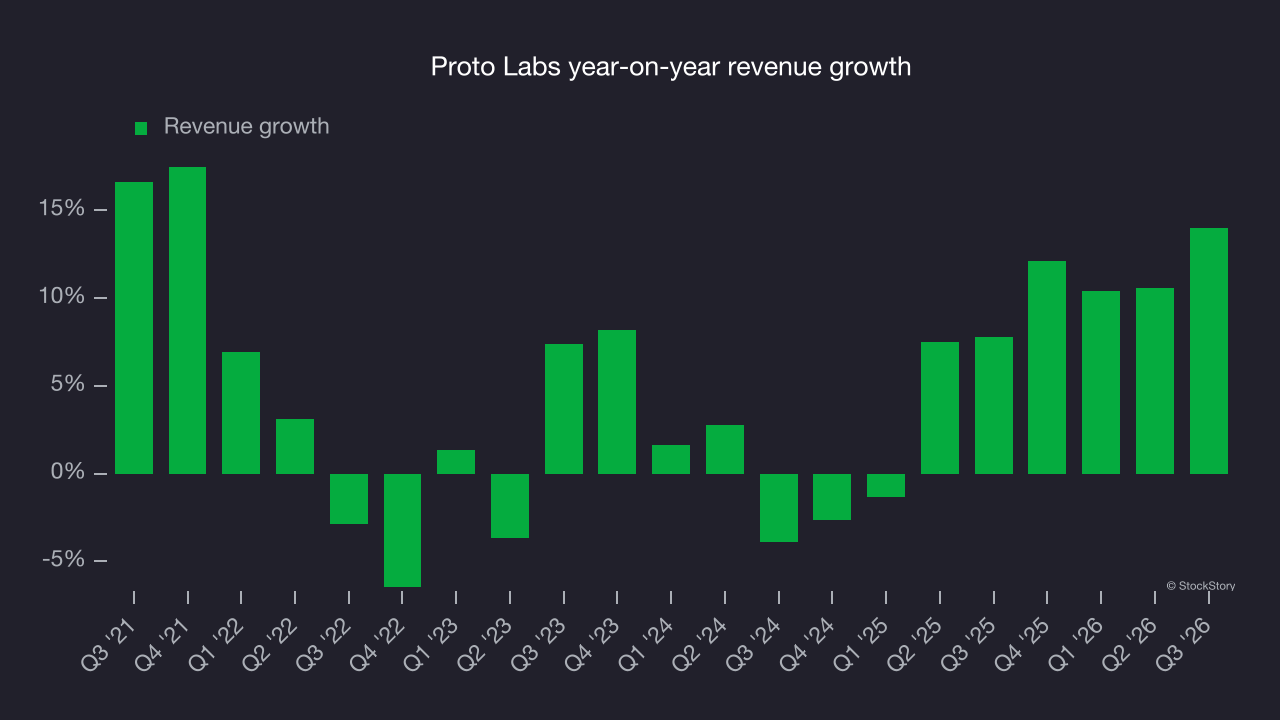
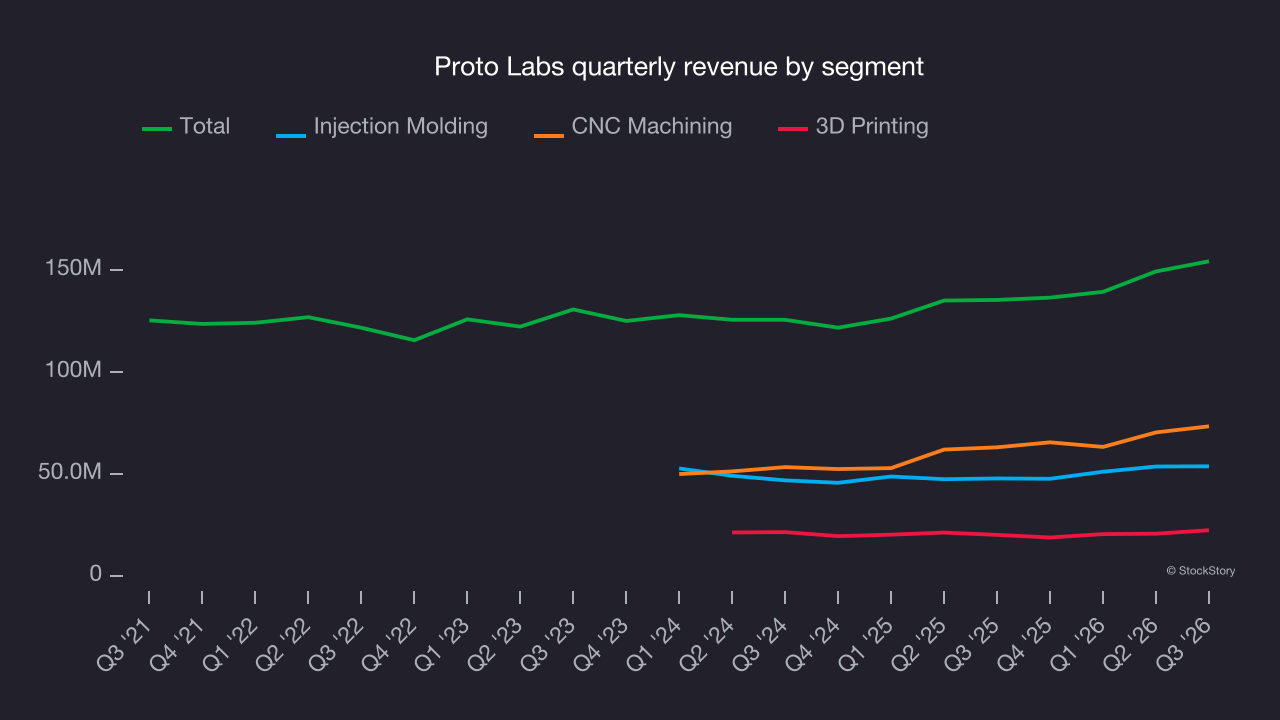
This quarter, Proto Labs reported year-on-year revenue growth of 14%, and its $154.3 million of revenue exceeded Wall Street’s consensus estimates by 3.6%. Company management is currently guiding for a 7.7% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 7.5% over the next 12 months, according to S&P, similar to its two-year rate. This underwhelming projection implies its newer products and services will not lead to better top-line performance yet.
Operating margin
Proto Labs’s operating margin has been trending up over the last 12 months, leading to breakeven profits over the last five years. However, its large expense base and inefficient cost structure mean it still has inadequate profitability for an industrials business. This result is surprising given its high gross margin baseline.
Looking at the trend in its profitability, Proto Labs’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
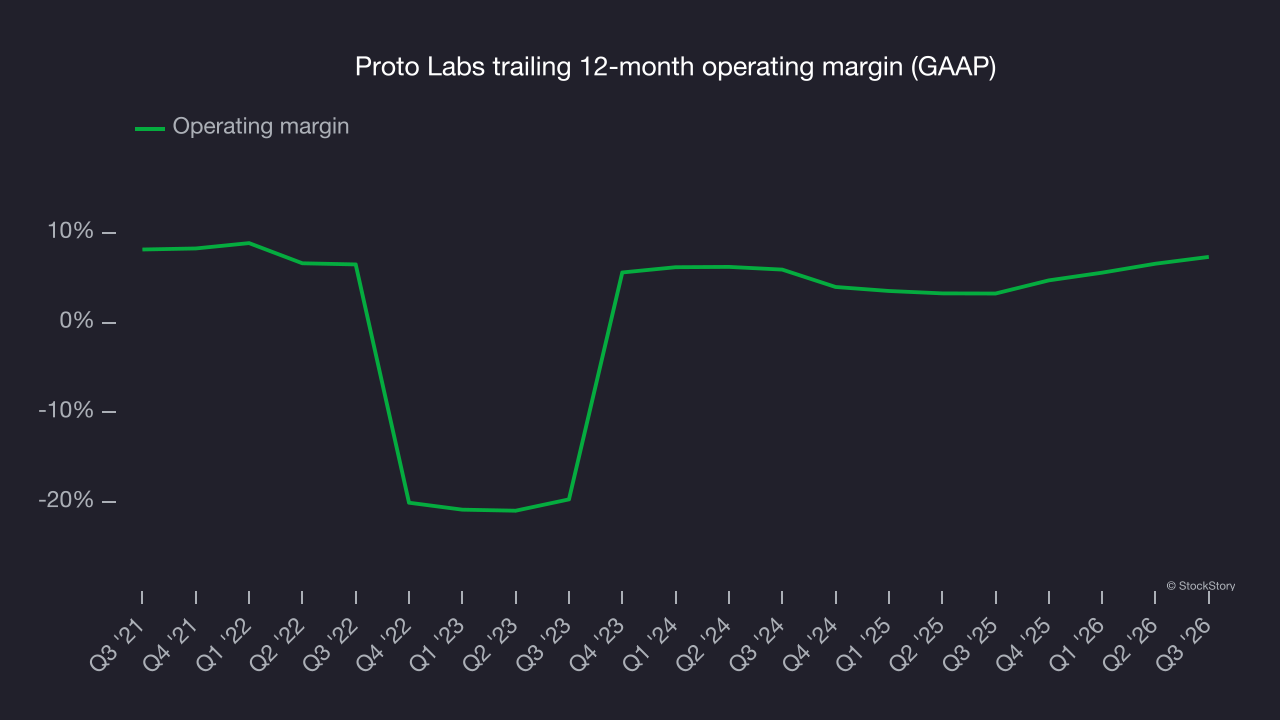
This quarter, Proto Labs generated an operating margin of 9.4%, up 2.8 percentage points year on year. The increase was a positive sign. Operating margin rose more than gross margin, indicating greater efficiency with expenses such as marketing, R&D and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Proto Labs’s unimpressive 6.1% annual EPS growth over the last five years aligns with its revenue performance. On the positive side, this indicates its incremental revenue was profitable.
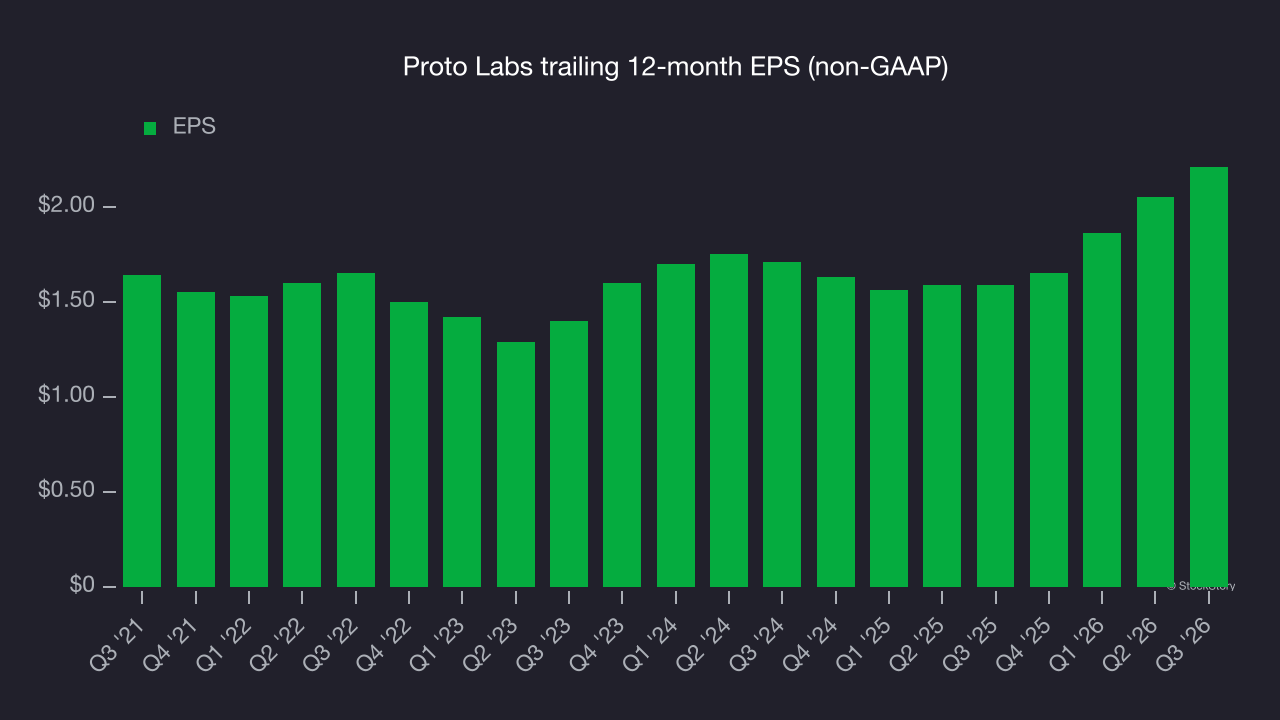
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Proto Labs’s two-year annual EPS growth of 13.7% was strong and topped its 7.2% two-year revenue growth.
We can take a deeper look into Proto Labs’s earnings to better understand the drivers of its performance. Proto Labs’s operating margin has expanded over the last two years while its share count has shrunk 2.3%. Improving profitability and share buybacks are positive signs for shareholders as they boost EPS growth relative to revenue growth.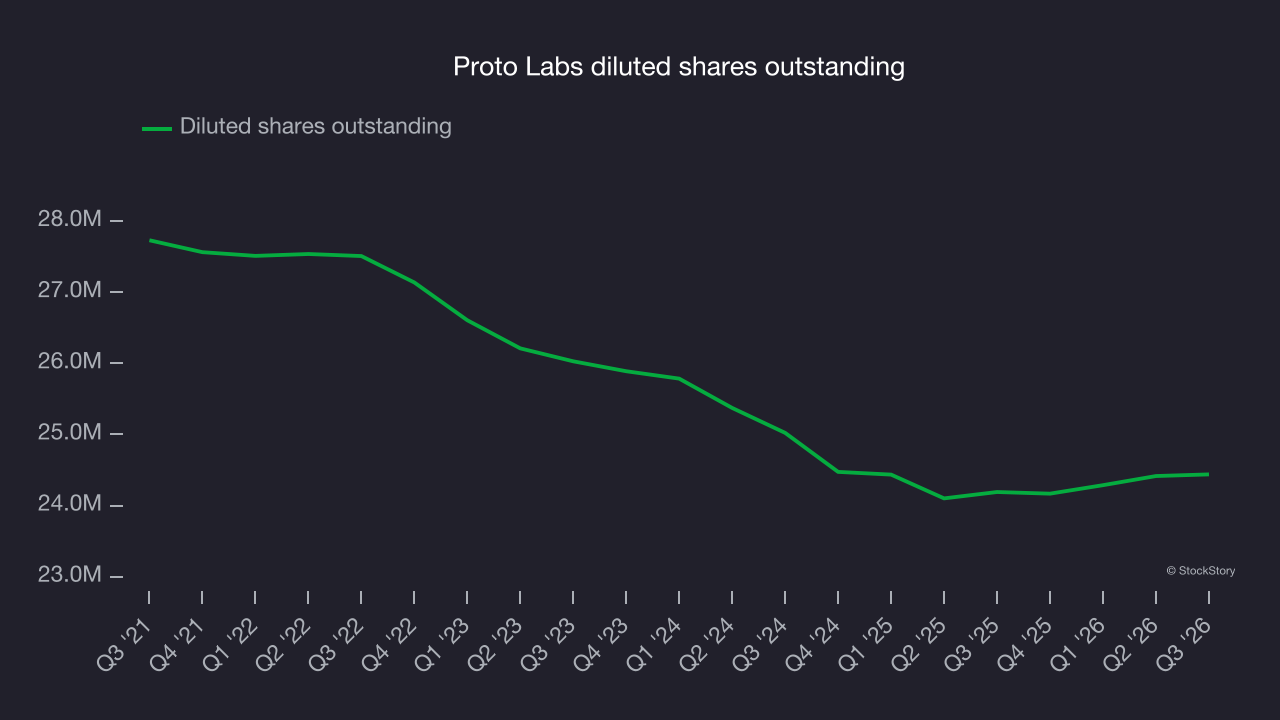
In Q3, Proto Labs reported adjusted EPS of $0.63, up from $0.47 in the same quarter last year. This result beat analysts’ consensus estimates by 5.7%. Over the next 12 months, Wall Street expects Proto Labs’s full-year EPS to grow 6.7% from $2.21 to $2.36, according to S&P.
Key takeaways from Proto Labs’s Q3 results
A sizable revenue beat and better-than-expected EPS guidance for next quarter gave Proto Labs’s results some key positives. Revenue came in well above analysts’ consensus estimates, and the EPS outlook topped Wall Street’s consensus. Shares remained flat at $90.91 immediately after the release.
To assess Proto Labs at its current price, the latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).