Lifestyle clothing conglomerate VF Corp (NYSE: VFC) beat Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue rising 1.2% year on year to $2.70 billion. Its GAAP profit of $0.71 per share was 32.5% above analysts’ consensus estimates.
For more on VF Corp, read our free full research report.
VF Corp (VFC) Q3 CY2026 highlights:
- Revenue $2.70 billion vs S&P analysts’ consensus estimates of $2.67 billion (1.2% year-on-year growth, 1.1% beat)
- EPS (GAAP) $0.71 vs analysts’ consensus estimates of $0.54 (32.5% beat)
- Operating margin 13.7%, up from 11.7% in the same quarter last year
- Free cash flow -$190.7 million compared to -$253.5 million in the same quarter last year
- Constant currency revenue fell 4% year on year
- Market capitalization $6.70 billion
Bracken Darrell, President and CEO, said: "We drove strong results in the second quarter, ahead of guidance across key metrics, as a result of great product and solid execution. The North Face® and Timberland® continued to deliver consistent growth, and Altra® grew more than 40%, all powered by bold product design and innovation and brand storytelling that are resonating with our consumers. Our plan to reignite Vans® is working – global DTC is growing again for the first time in almost five years, and strong orders from Wholesale partners continue to give us confidence of a second half improvement. We are delivering sustainable and profitable growth on our path to achieve our full-year guidance and medium-term targets, as the upside potential in our business becomes even more evident."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Over the last five years, VF Corp’s demand was weak and its revenue declined by 3.1% per year. That outcome points to poor business quality.
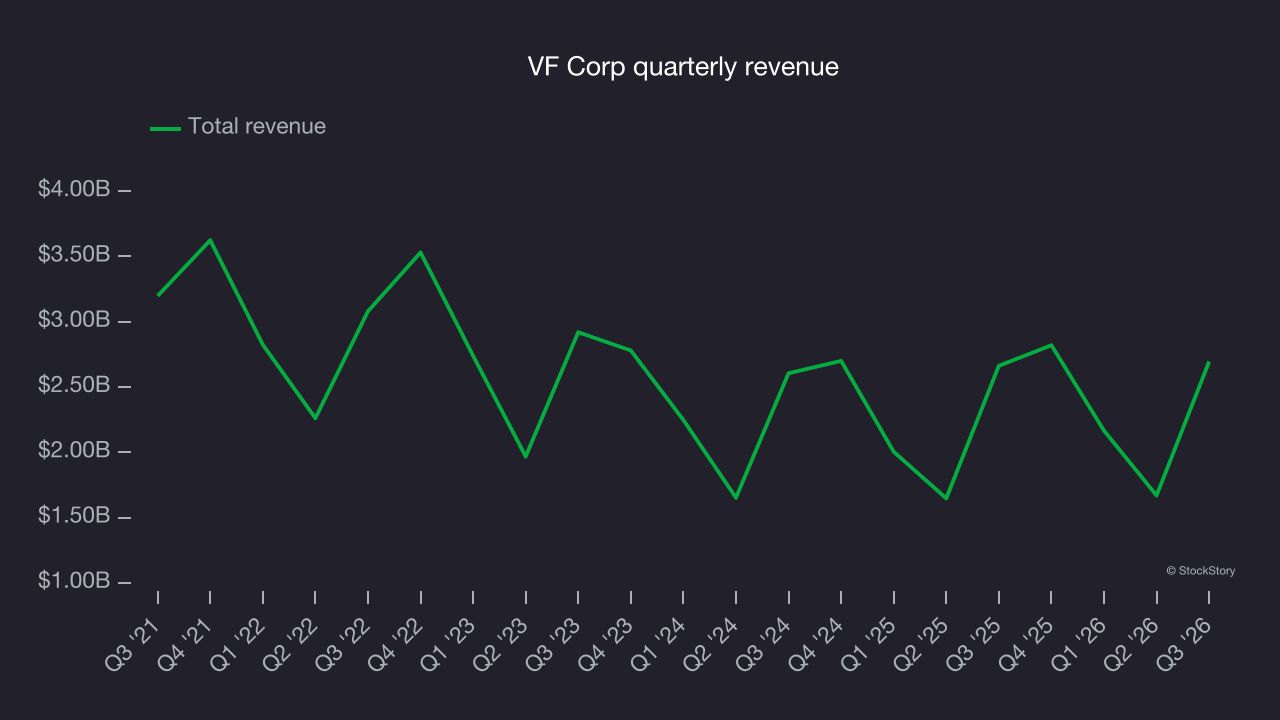
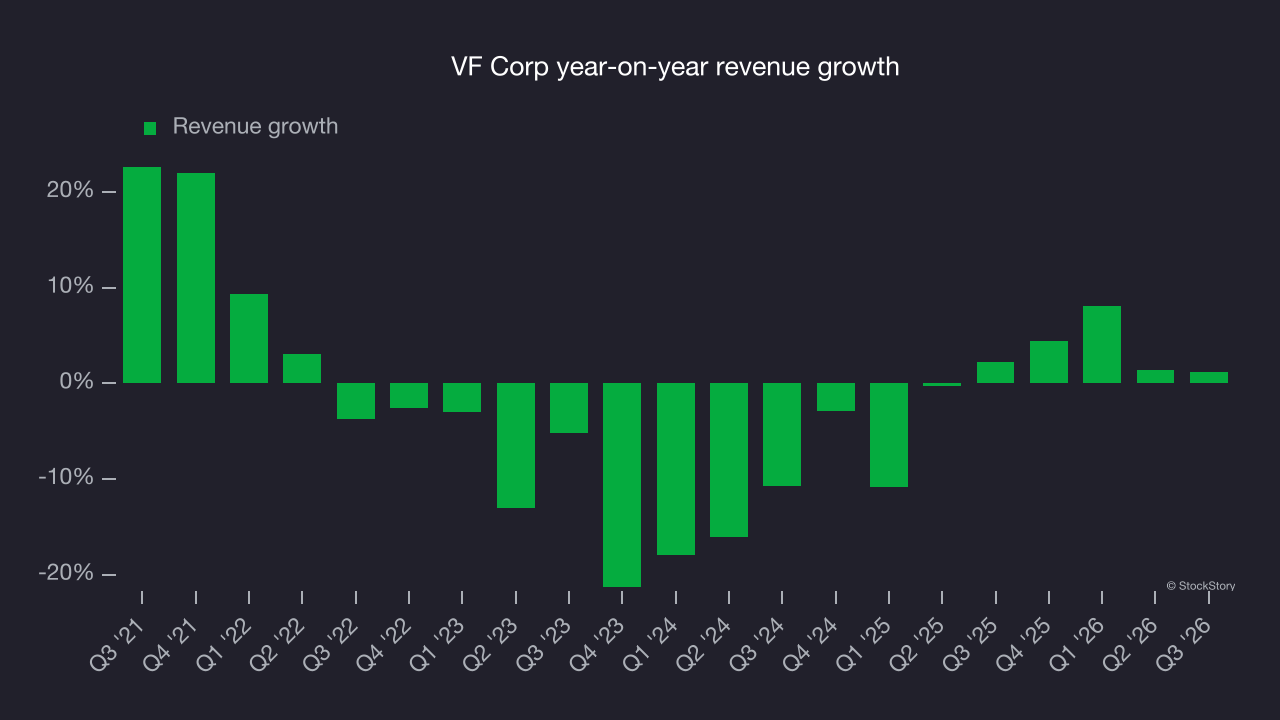
This quarter, VF Corp reported modest year-on-year revenue growth of 1.2% but beat Wall Street’s consensus estimates by 1.1%.
Looking ahead, sell-side analysts expect revenue to grow 3.1% over the next 12 months, according to S&P. Although this projection indicates its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
VF Corp’s operating margin has risen over the last 12 months and averaged 5.5% over the last two years. The company’s higher efficiency is a positive sign, but its suboptimal cost structure means profitability remains inadequate for a consumer discretionary business.
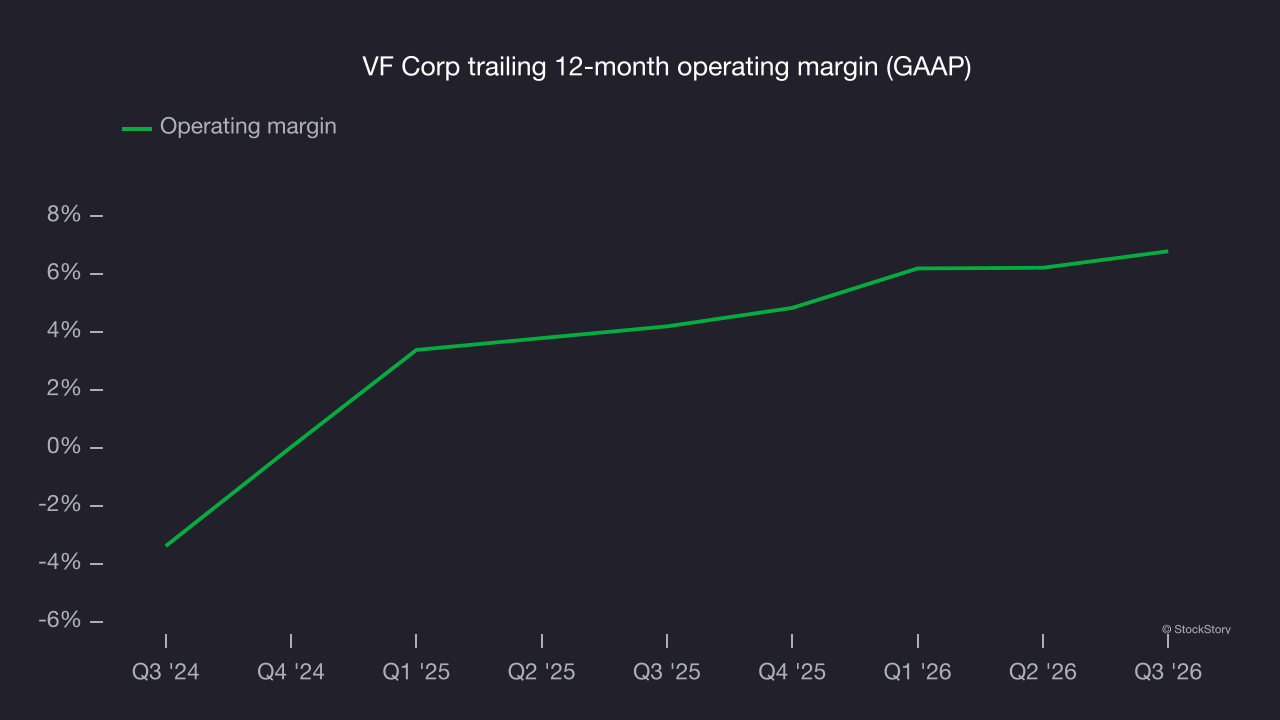
This quarter, VF Corp generated an operating margin of 13.7%, up 1.9 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
VF Corp’s EPS declined by 21.7% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
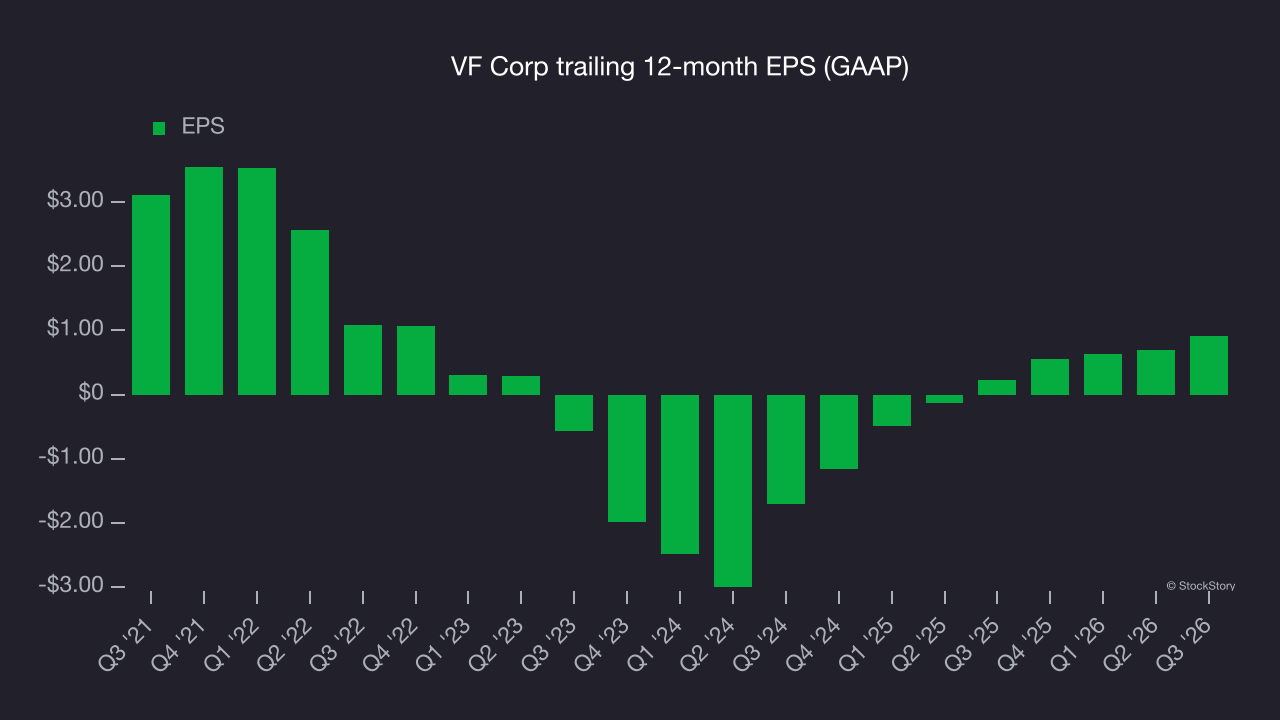
In Q3, VF Corp reported EPS of $0.71, up from $0.48 in the same quarter last year. This comfortably beat analysts’ consensus estimates. Over the next 12 months, Wall Street expects VF Corp’s full-year EPS to grow 25.8% from $0.91 to $1.15, according to S&P.
Key takeaways from VF Corp’s Q3 results
It was good to see VF Corp beat analysts’ EPS expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. However, constant currency revenue growth declined year on year. Investors were likely hoping for more, and shares traded down 3.8% to $16.38 immediately after reporting.
To assess whether VF Corp is a buy at the current price, it’s important to consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).