Regional banking company Fulton Financial (NASDAQ: FULT) beat Wall Street’s revenue expectations in Q3 2026, with sales up 9.6% year on year to $371.6 million. Its non-GAAP profit of $0.62 per share was 13% above analysts’ consensus estimates.
Is now the time to buy Fulton Financial? Find out by accessing our full research report, it’s free.
Fulton Financial (FULT) Q3 2026 highlights:
- Net Interest Income: $290 million vs analyst estimates of $291 million (9.8% year-on-year growth, in line)
- Net Interest Margin: 3.6% vs analyst estimates of 3.6% (in line)
- Revenue: $371.6 million vs analyst estimates of $367.8 million (9.6% year-on-year growth, 1% beat)
- Efficiency Ratio: 56.8% vs analyst estimates of 58.7% (192.9 basis point beat)
- Adjusted EPS: $0.62 vs analyst estimates of $0.55 (13% beat)
- Tangible Book Value per Share: $15.14 vs analyst estimates of $15.91 (5.2% year-on-year growth, 4.8% miss)
- Market Capitalization: $4.32 billion
"During the quarter, we achieved record financial results while successfully completing the Blue Foundry Bank integration and delivering solid growth in the customer base and customer funding," said Curtis J. Myers, Fulton Chairman, CEO and President. "Our ongoing strong performance reflects robust demand for our community banking model and the steadfast dedication of our team members to deliver a personalized experience. The sustained commitment to executing our strategic priorities is generating long-term value for our shareholders."
Company overview
Tracing its roots back to 1882 in the heart of Pennsylvania, Fulton Financial (NASDAQ: FULT) is a financial holding company that provides banking, lending, and wealth management services to consumers and businesses across five Mid-Atlantic states.
Sales growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income. Regrettably, Fulton Financial’s revenue grew at a mediocre 9.4% compounded annual growth rate over the last five years. This was below our standard for the banking sector and is a rough starting point for our analysis.
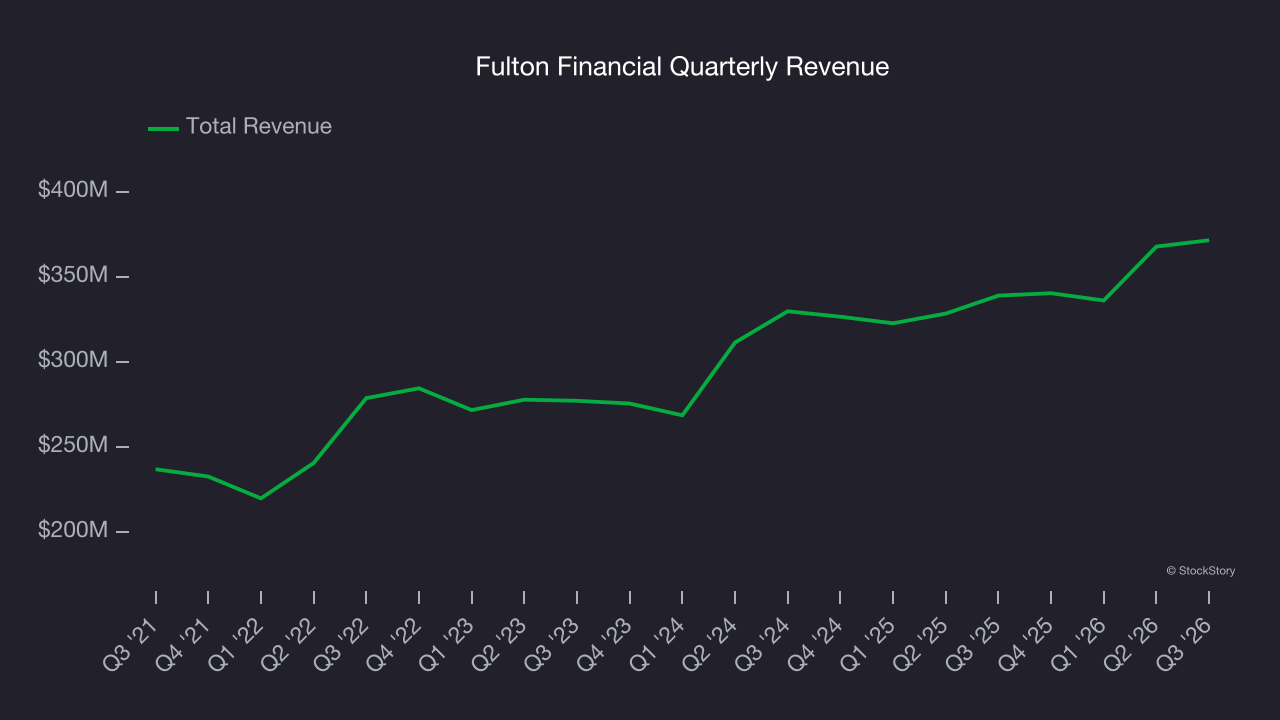
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Fulton Financial’s annualized revenue growth of 9.3% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 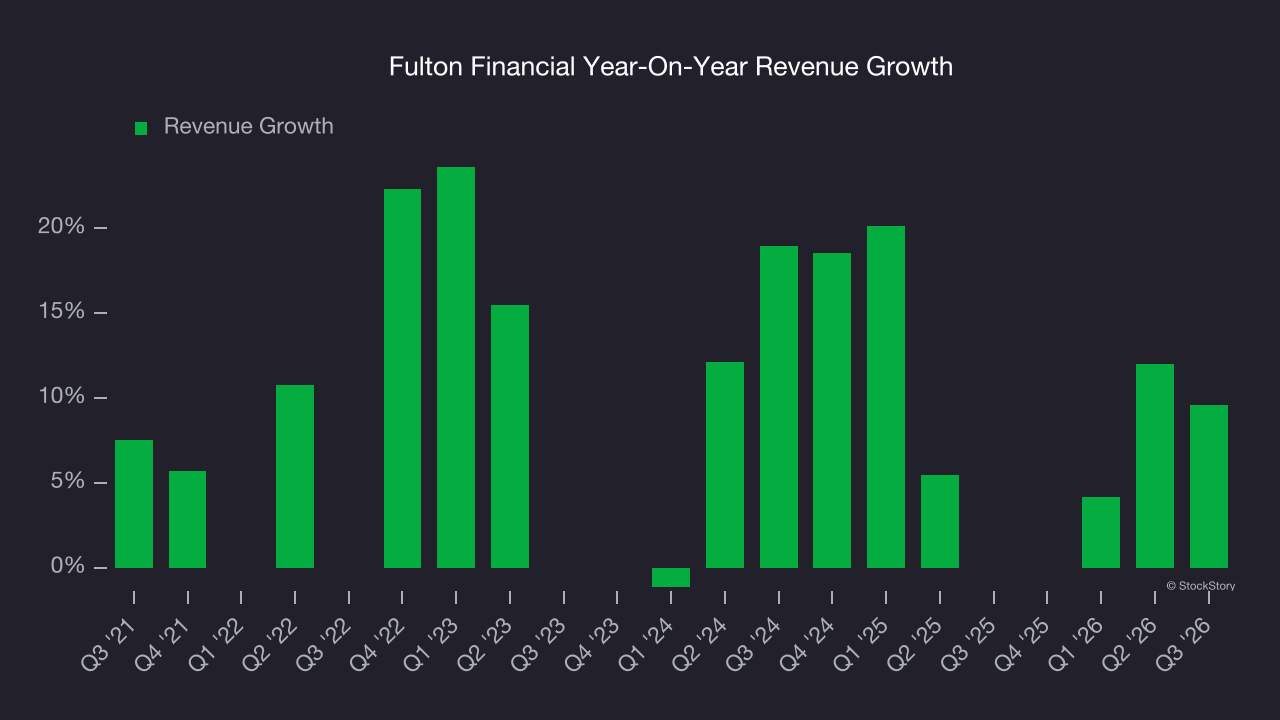 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Fulton Financial reported year-on-year revenue growth of 9.6%, and its $371.6 million of revenue exceeded Wall Street’s estimates by 1%.
Net interest income made up 77% of the company’s total revenue during the last five years, meaning lending operations are Fulton Financial’s largest source of revenue.
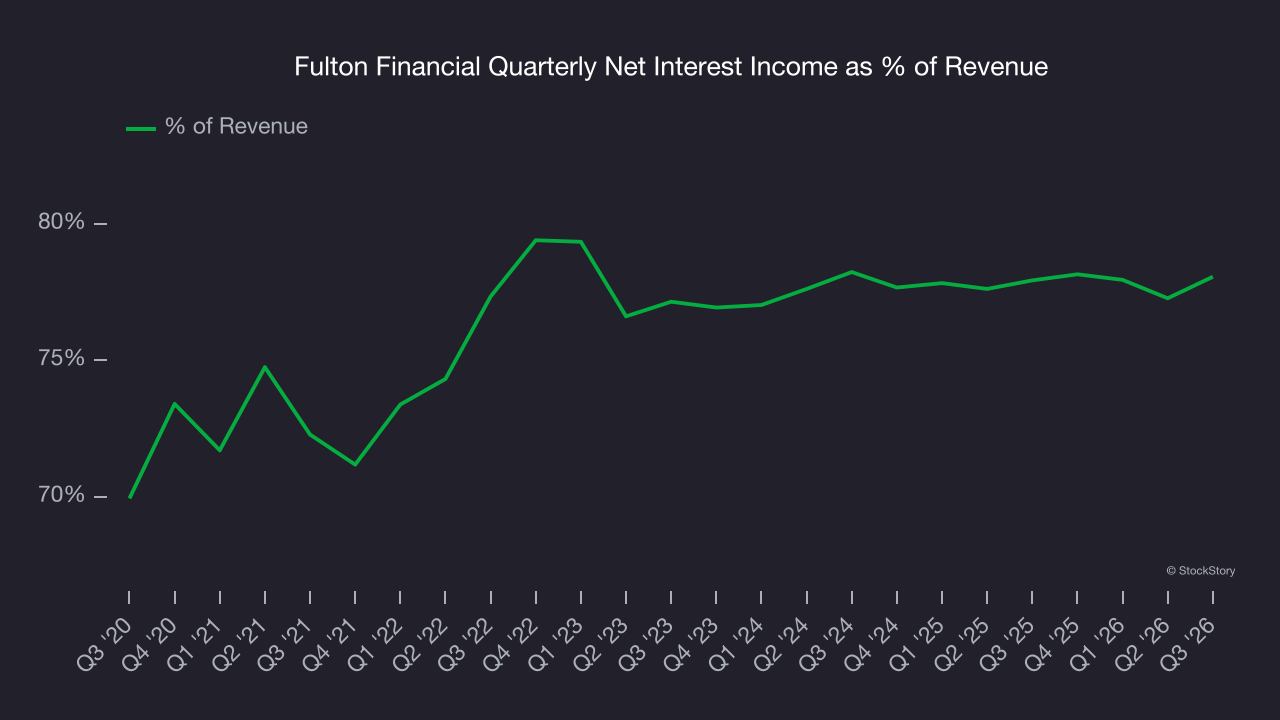
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
Fulton Financial’s TBVPS grew at a mediocre 4.4% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 10% annually over the last two years from $12.51 to $15.14 per share.
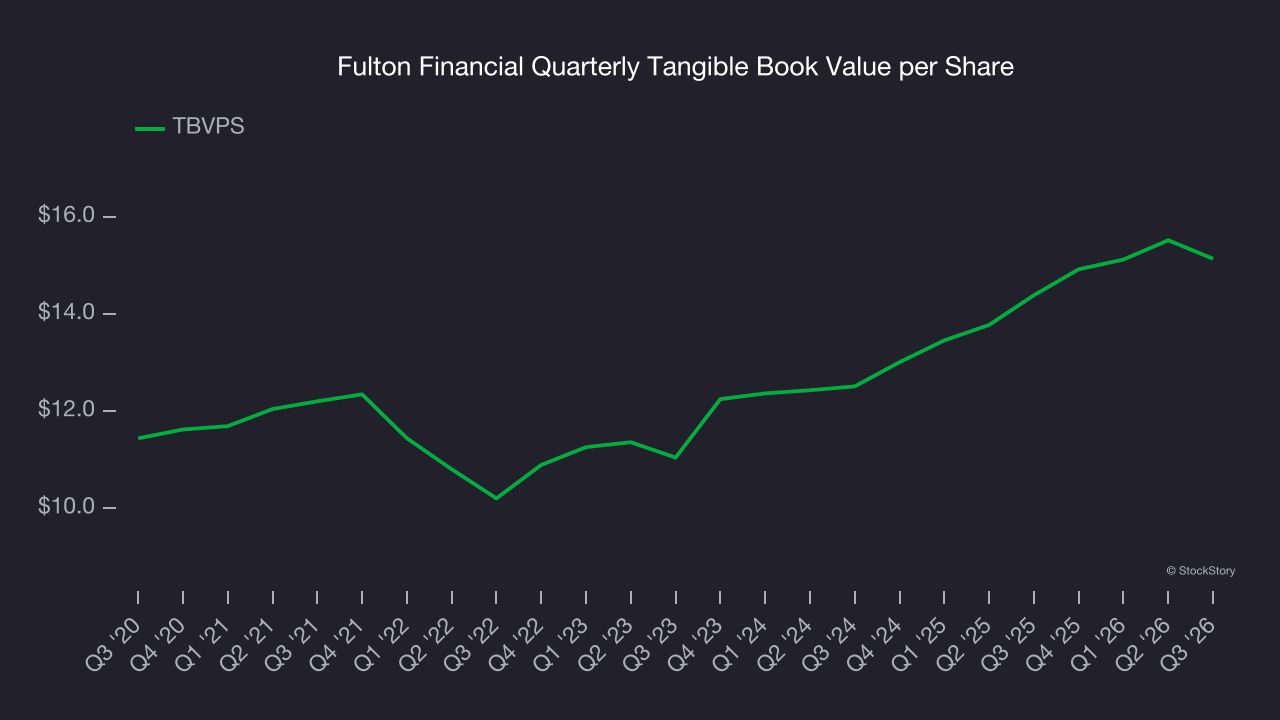
Over the next 12 months, Consensus estimates call for Fulton Financial’s TBVPS to grow by 15.5% to $17.49, solid growth rate.
Key takeaways from Fulton Financial’s Q3 results
It was good to see Fulton Financial beat analysts’ EPS expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. On the other hand, its tangible book value per share missed and its net interest income was in line with Wall Street’s estimates. Zooming out, we think this was a mixed quarter. The stock remained flat at $22.51 immediately following the results.
Should you buy the stock or not? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).