Over the last six months, Old Republic International’s shares have sunk to $38.41, producing a disappointing 6.8% loss - a stark contrast to the S&P 500’s 11.2% gain. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Old Republic International, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Old Republic International Will Underperform?
Even though the stock has become cheaper, we don’t have much confidence in Old Republic International. Here are three reasons why there are better opportunities than ORI, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Insurers earn revenue three ways. The core insurance business itself, often called underwriting and represented in the income statement as premiums earned, is one way. Investment income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities is the second way. Fees from various sources such as policy administration, annuities, or other value-added services are the third.
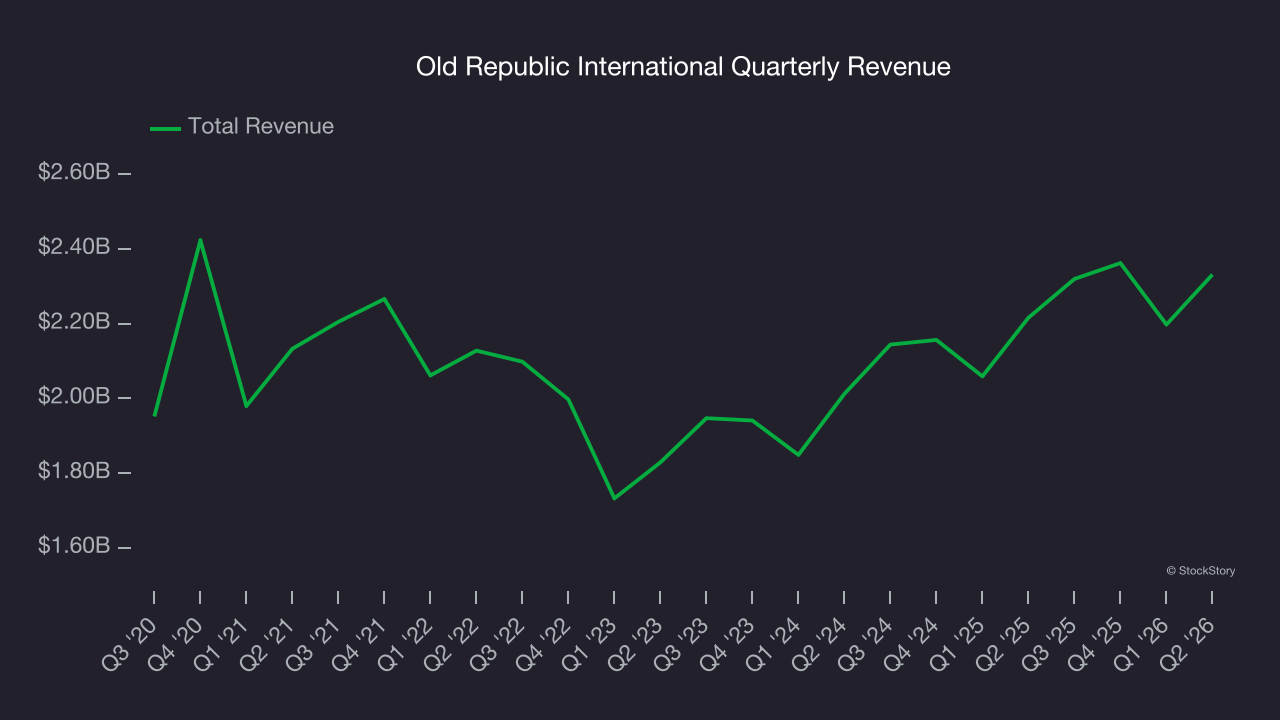
Regrettably, Old Republic International’s revenue grew at a sluggish 1.6% compounded annual growth rate over the last five years. This was below our standards.
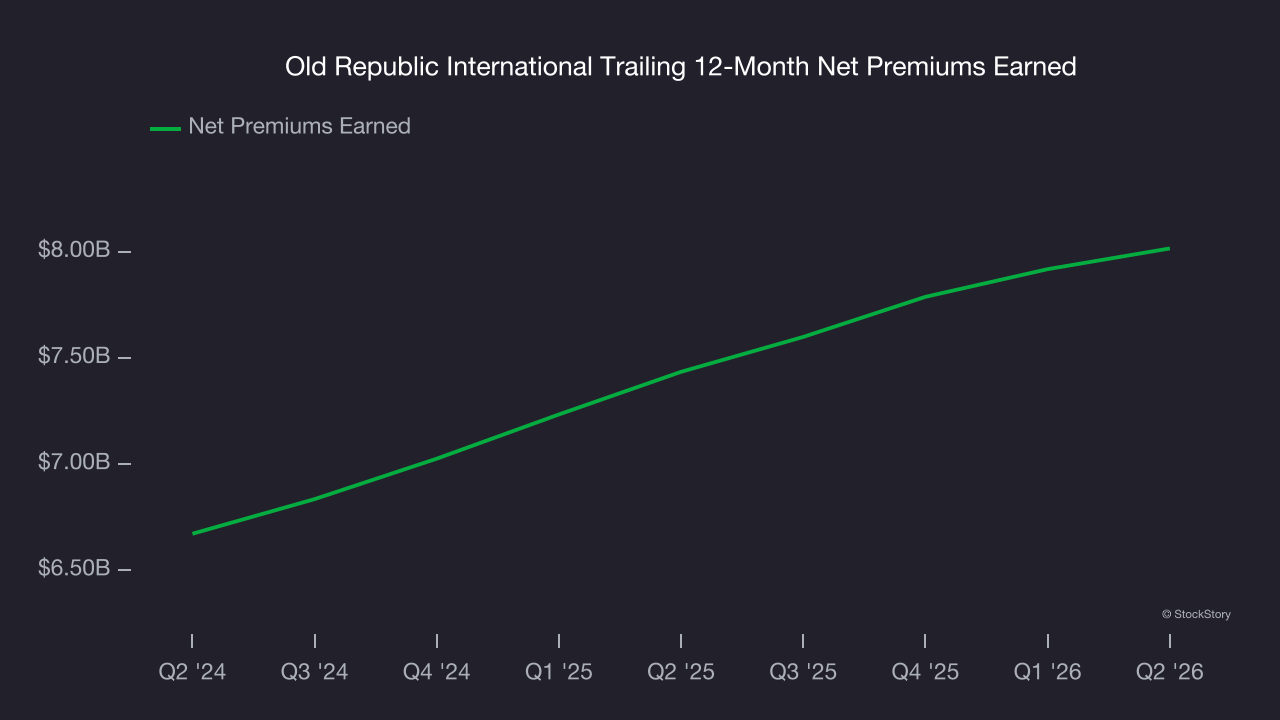
2. Net Premiums Earned Point to Soft Demand
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore gross premiums less what’s ceded to reinsurers as a risk mitigation and transfer strategy.
Old Republic International’s net premiums earned has grown at a 2.7% annualized rate over the last five years, much worse than the broader insurance industry.
3. EPS Barely Growing
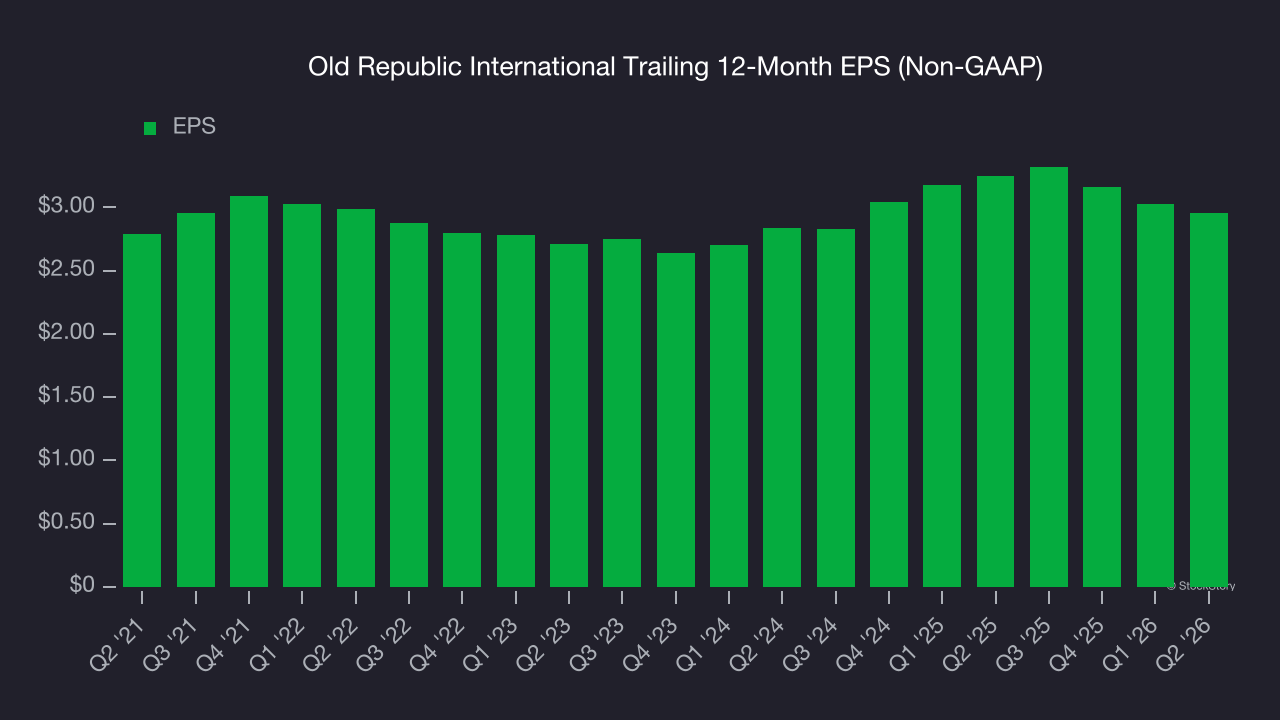
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Old Republic International’s weak 1.2% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
Final Judgment
Old Republic International doesn’t pass our quality test. Following the recent decline, the stock trades at 1.5× forward P/B (or $38.41 per share). This valuation tells us a lot of optimism is priced in - we think other companies feature superior fundamentals at the moment. Let us point you toward one of our top digital advertising picks.
Stocks We Would Buy Instead of Old Republic International
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.