Financial services giant Bank of America (NYSE: BAC) fell short of the market’s revenue expectations in Q3 2026 as sales rose 2.6% year on year to $29.96 billion. Its GAAP profit of $0.91 per share was 17.6% below analysts’ consensus estimates.
Is now the time to buy Bank of America? Find out by accessing our full research report, it’s free.
Bank of America (BAC) Q3 2026 Highlights:
- Net Interest Income: $16.45 billion vs analyst estimates of $16.52 billion (8% year-on-year growth, in line)
- Net Interest Margin: 2.2% vs analyst estimates of 2.1% (4.8 basis point beat)
- Revenue: $29.96 billion vs analyst estimates of $30.56 billion (2.6% year-on-year growth, 2% miss)
- Efficiency Ratio: 65.8% vs analyst estimates of 61.1% (477.3 basis point miss)
- EPS (GAAP): $0.91 vs analyst expectations of $1.10 (17.6% miss)
- Tangible Book Value per Share: $29.14 vs analyst estimates of $29.62 (2.1% year-on-year growth, 1.6% miss)
- Market Capitalization: $377.3 billion
Company Overview
Tracing its roots back to 1784 and now serving approximately 67 million consumer and small business clients, Bank of America (NYSE: BAC) is a global financial institution that provides banking, investing, asset management, and risk management products and services to individuals, businesses, and governments.
Sales Growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Regrettably, Bank of America’s revenue grew at a tepid 6.6% compounded annual growth rate over the last five years. This fell short of our benchmark for the banking sector and is a rough starting point for our analysis.
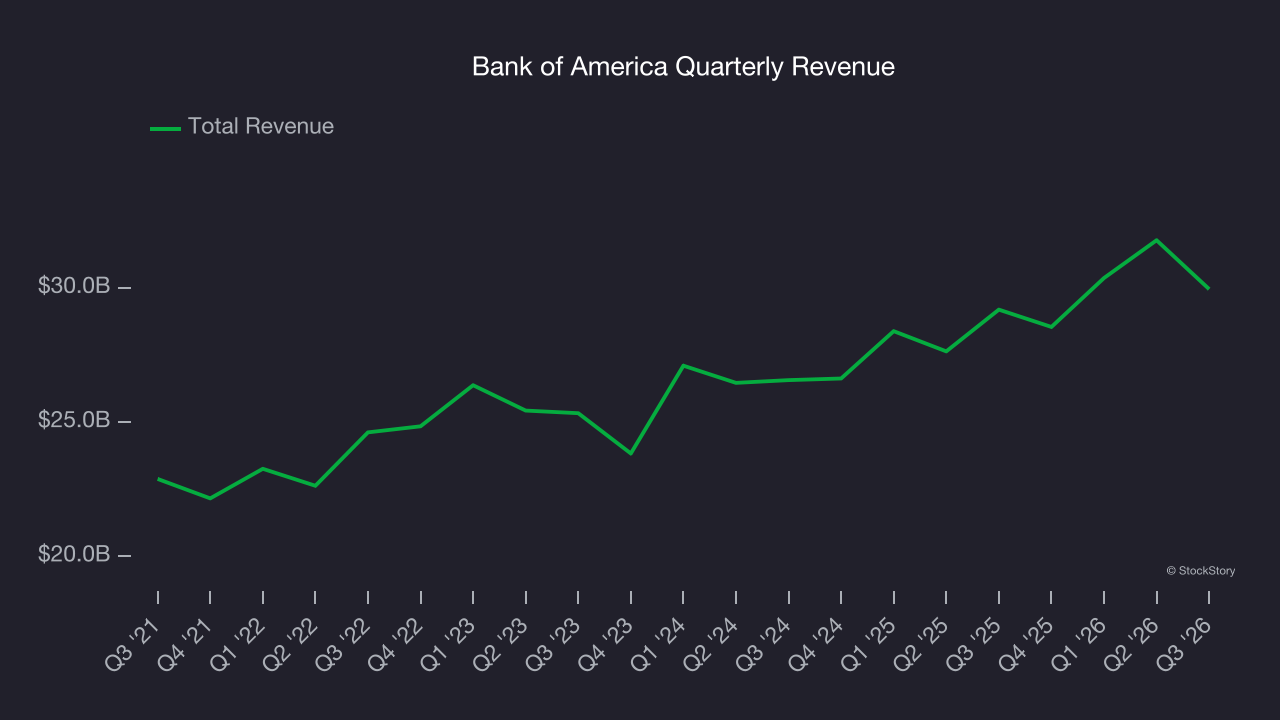
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Bank of America’s annualized revenue growth of 7.7% over the last two years is above its five-year trend, which is encouraging. 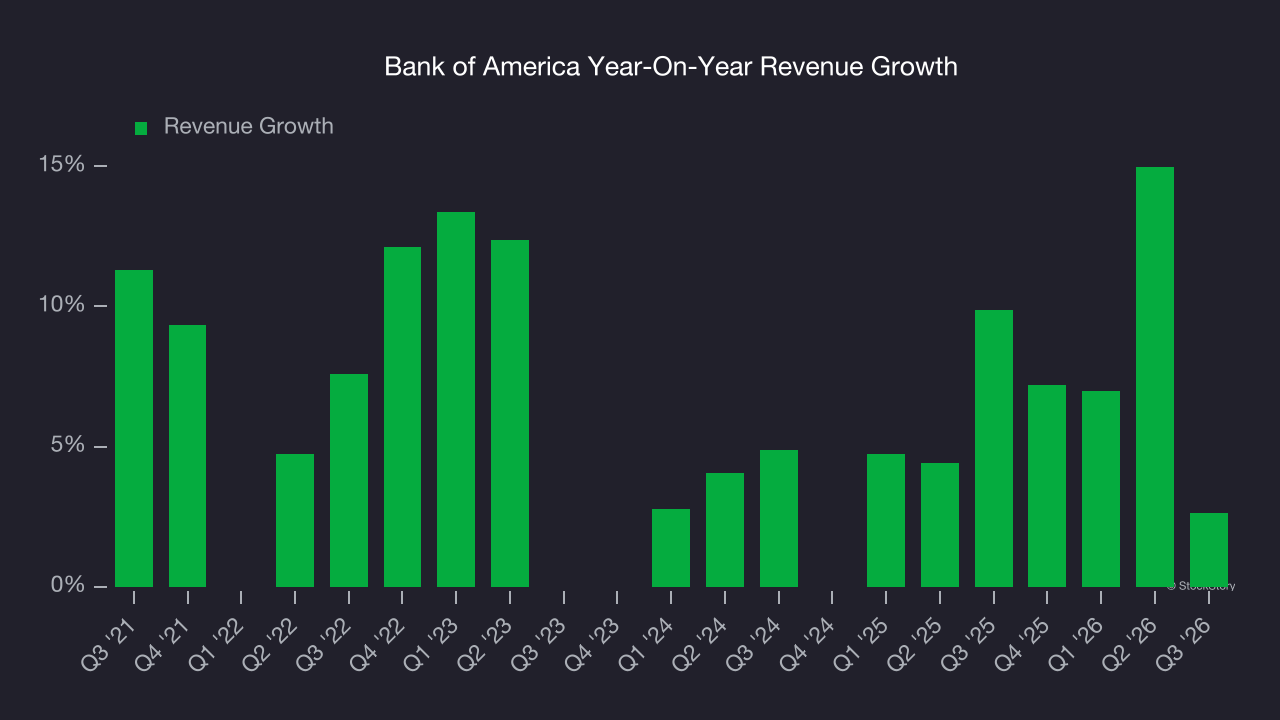 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Bank of America’s revenue grew by 2.6% year on year to $29.96 billion, falling short of Wall Street’s estimates.
Net interest income made up 53.8% of the company’s total revenue during the last five years, meaning Bank of America’s growth drivers strike a balance between lending and non-lending activities.
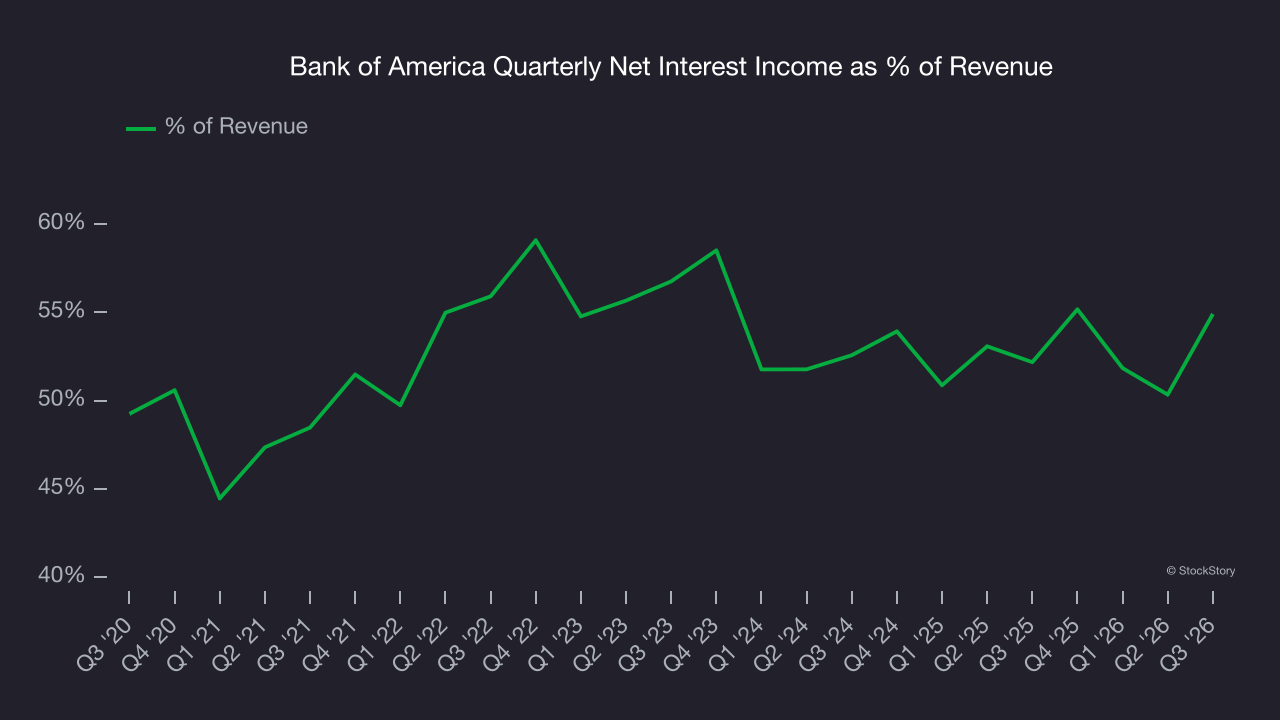
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Tangible Book Value Per Share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value by removing intangible assets of debatable liquidation worth. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
Bank of America’s TBVPS grew at a decent 5.9% annual clip over the last five years. The last two years show a similar trajectory as TBVPS grew by 5.1% annually from $26.39 to $29.14 per share.
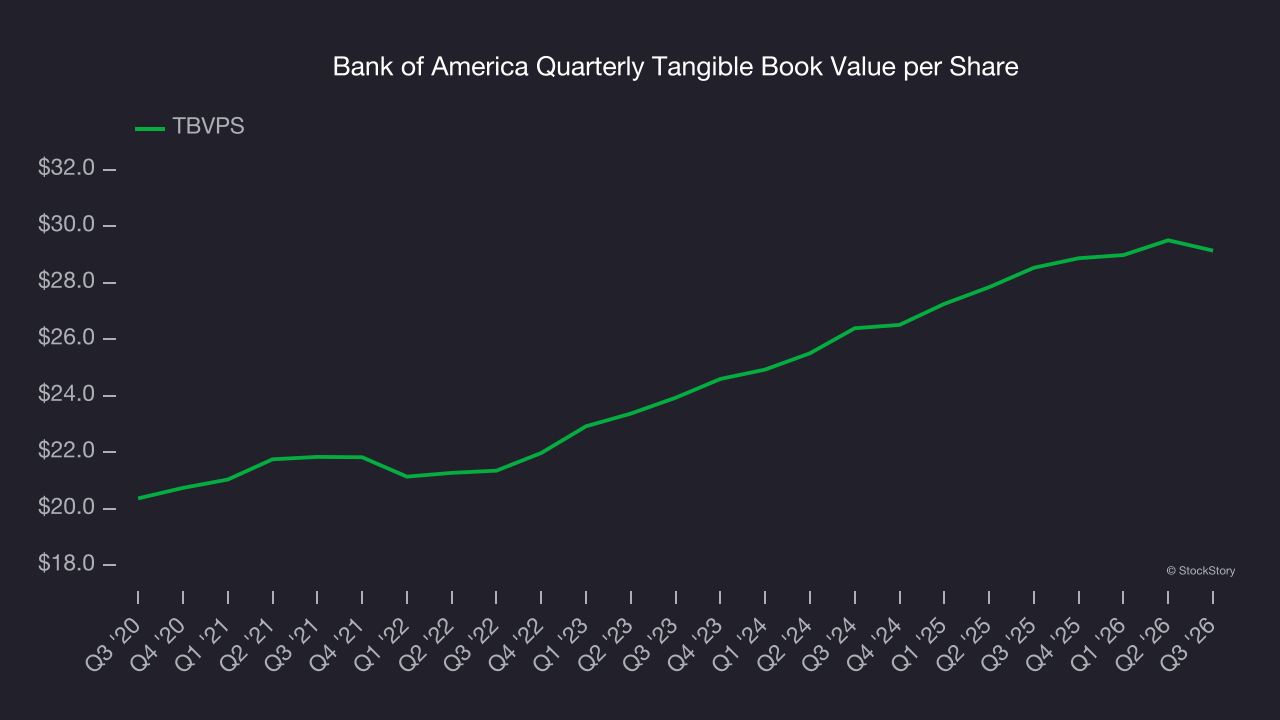
Over the next 12 months, Consensus estimates call for Bank of America’s TBVPS to grow by 9.5% to $31.92, paltry growth rate.
Key Takeaways from Bank of America’s Q3 Results
We struggled to find many positives in these results. Its EPS missed and its revenue fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock traded down 4% to $51.72 immediately after reporting.
The latest quarter from Bank of America’s wasn’t that good. One earnings report doesn’t define a company’s quality, though, so let’s explore whether the stock is a buy at the current price. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).