
Over the last six months, KBR’s shares have sunk to $35.16, producing a disappointing 6.3% loss - a stark contrast to the S&P 500’s 16.6% gain. This might have investors contemplating their next move.
Is now the time to buy KBR, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is KBR Not Exciting?
Even though the stock has become cheaper, we’re passing on KBR for now. Here are three reasons we avoid KBR, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
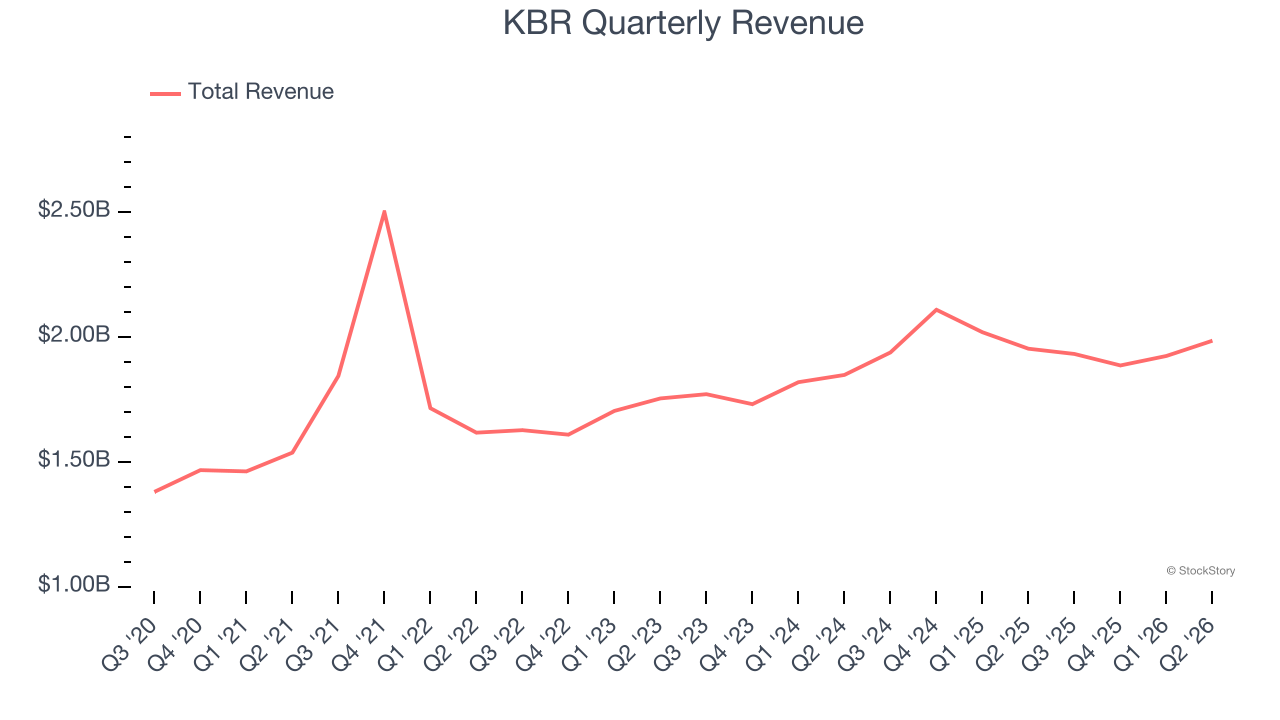
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Regrettably, KBR’s sales grew at a tepid 5.7% compounded annual growth rate over the last five years. This was below our standard for the industrials sector.
2. Backlog Is Unchanged, Sales Pipeline Stalls
In addition to reported revenue, backlog is a useful data point for analyzing Defense Contractors companies. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into KBR’s future revenue streams.
Over the last two years, KBR failed to grow its backlog, which came in at $17.81 billion in the latest quarter. This performance was underwhelming and shows the company faced challenges in winning new orders. It also suggests there may be increasing competition or market saturation. 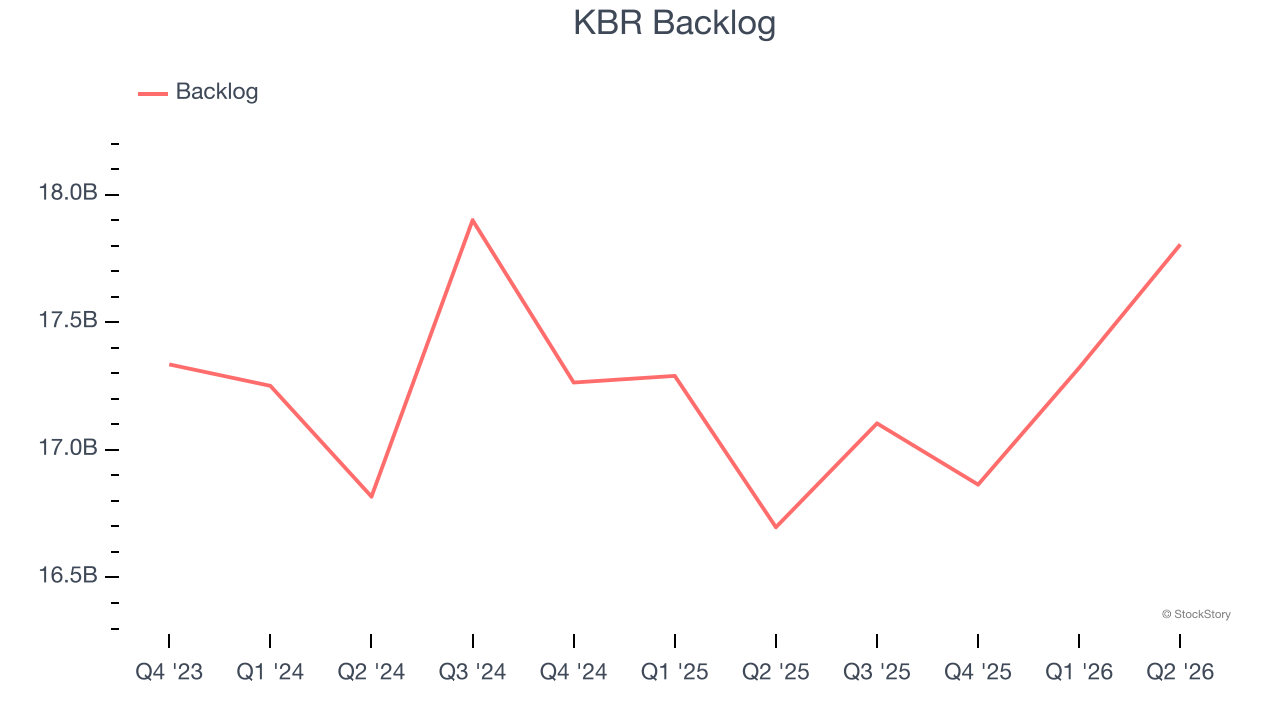
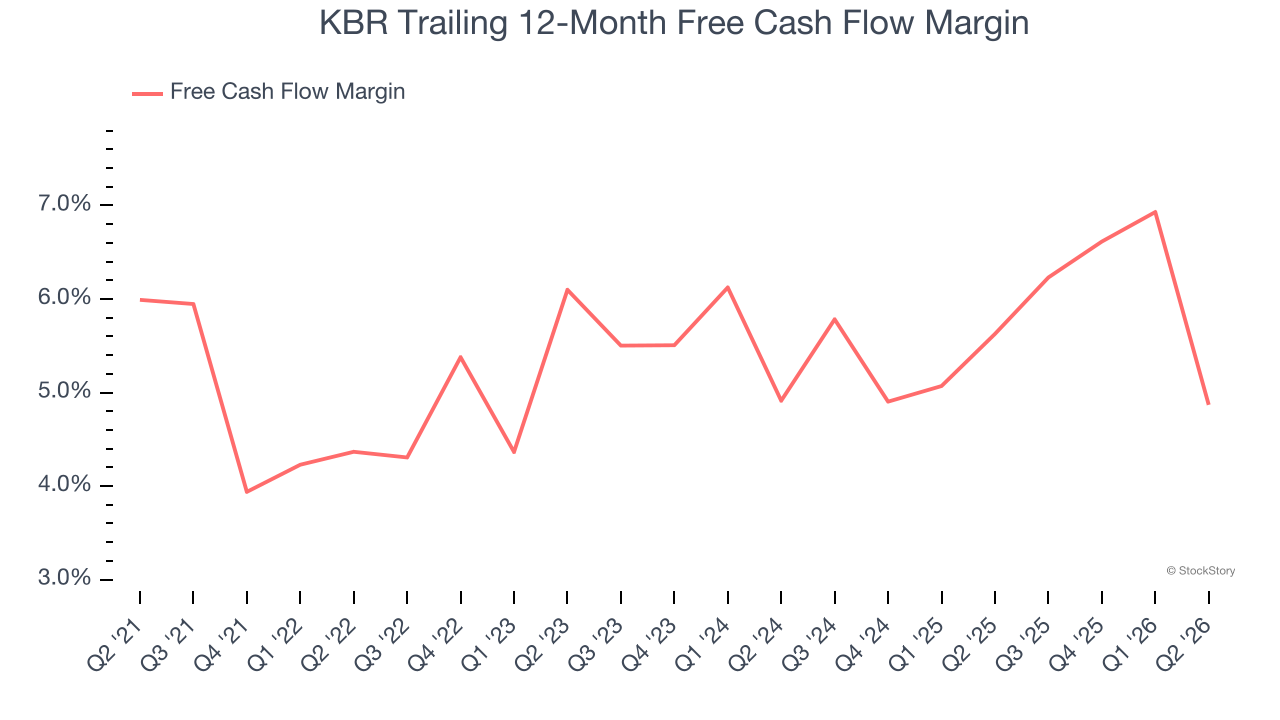
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
KBR has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5.2%, below what we’d expect for an industrials business.
Final Judgment
KBR isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 8.6× forward P/E (or $35.16 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Like More Than KBR
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.