Bunge Global currently trades at $119.30 per share and has shown little upside over the past six months, posting a small loss of 3.8%. The stock also fell short of the S&P 500’s 14% gain during that period.
Is now the time to buy Bunge Global, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Bunge Global Not Exciting?
We’re cautious about Bunge Global. Here are three reasons you should be careful with BG, plus one stock we’d rather own.
1. Projected Revenue Growth Shows Limited Upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Bunge Global’s revenue to stall, a deceleration versus its 12.9% annualized growth for the past three years. This projection doesn’t excite us and implies its products will face some demand challenges.
2. Low Gross Margin Reveals Weak Structural Profitability
All else equal, we prefer higher gross margins because they make it easier to generate more operating profits and indicate that a company commands pricing power by offering more differentiated products.
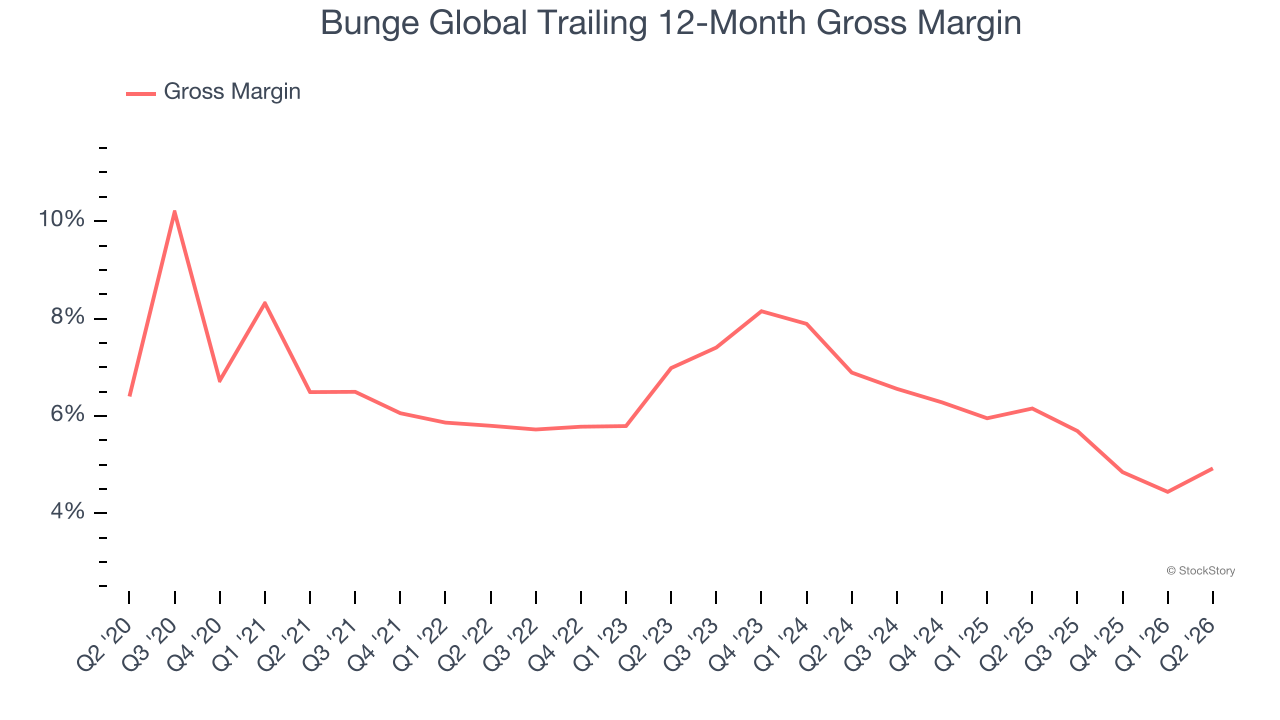
Bunge Global has bad unit economics for a consumer staples company, signaling it operates in a competitive market and lacks pricing power because its products can be substituted. As you can see below, it averaged a 5.4% gross margin over the last two years. That means Bunge Global paid its suppliers a lot of money ($94.64 for every $100 in revenue) to run its business.
3. EPS Trending Down
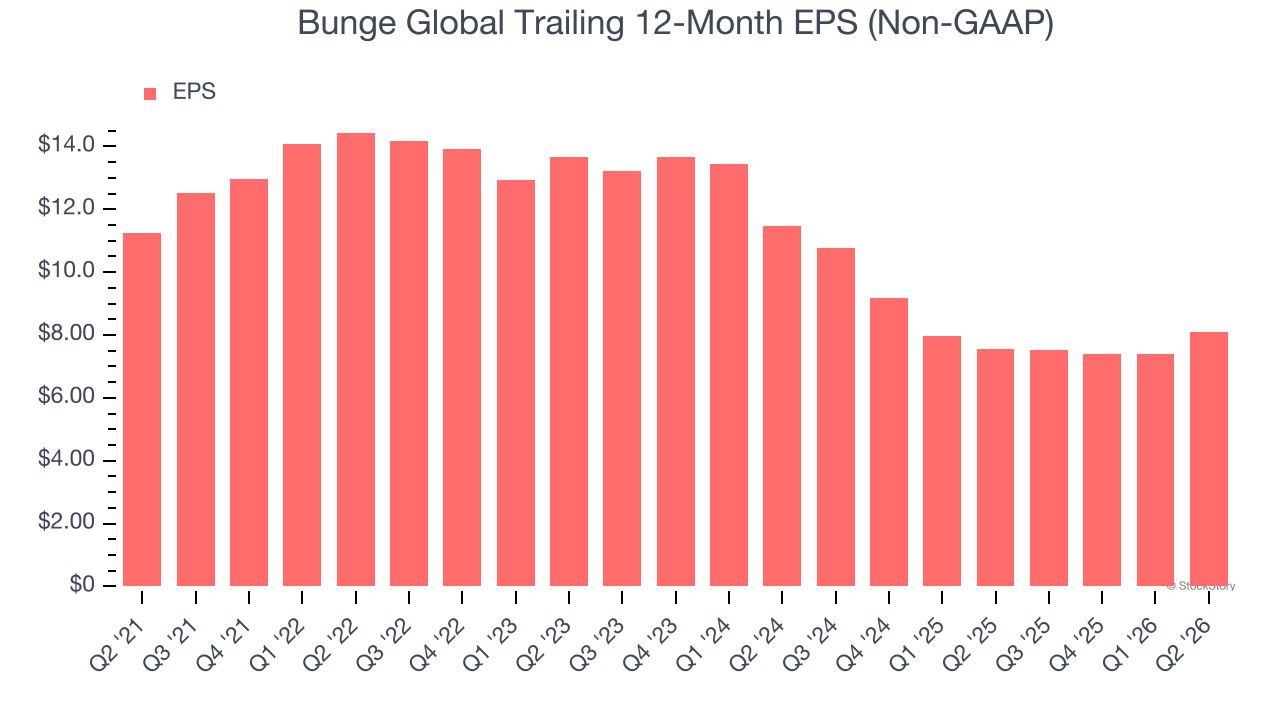
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Bunge Global, its EPS declined by 16% annually over the last three years while its revenue grew by 12.9%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Bunge Global’s business quality ultimately falls short of our standards. With its shares lagging the market recently, the stock trades at 10.8× forward P/E (or $119.30 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. We’d recommend looking at one of our all-time favorite software stocks.
Stocks We Like More Than Bunge Global
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.