Energy drink company Monster Beverage (NASDAQ: MNST) reported Q3 2026 results topping the market’s revenue expectations, with revenue rising 16.7% year on year to $2.56 billion. Its non-GAAP profit of $0.30 per share was in line with analysts’ consensus estimates.
For more on Monster, read our free full research report.
Monster (MNST) Q3 2026 highlights:
- Revenue $2.56 billion vs S&P analysts’ consensus estimates of $2.48 billion (16.7% year-on-year growth, 3.2% beat)
- Adjusted EPS $0.30 vs S&P analysts’ consensus estimates of $0.30 (in line)
- Adjusted operating income $748.1 million vs analysts’ consensus estimates of $742.5 million (29.2% margin, 0.8% beat)
- Operating margin 28%, down from 30.7% in the same quarter last year
- Market capitalization $95.5 billion
“Our new product launches this quarter, including additions to the Monster Energy®, Java Monster®, Mother® and FLRTTM product lines, reflect our ongoing commitment to innovation alongside the continued growth of our core offerings,” Mr. Schlosberg added.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones sustain growth for years.
With $9.58 billion in revenue over the past 12 months, Monster is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions.
Monster’s revenue grew at a decent 11.5% compounded annual growth rate over the last three years. This shows its offerings generated slightly more demand than the average consumer staples company.
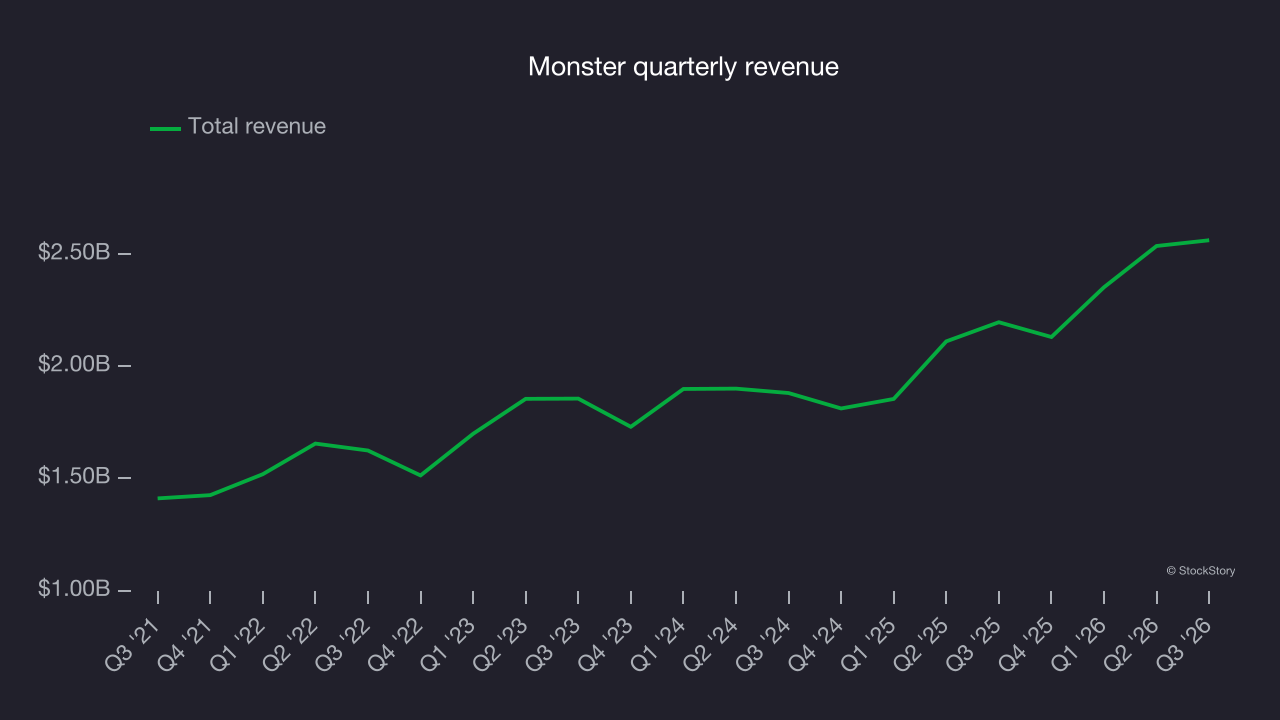
This quarter, Monster reported year-on-year revenue growth of 16.7%, and its $2.56 billion in revenue exceeded Wall Street’s consensus estimates by 3.2%.
Looking ahead, sell-side analysts expect revenue to grow 8.9% over the next 12 months, according to S&P, a slight deceleration versus the last three years. Still, that growth outlook is strong and implies the market sees success for its products.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it difficult to manipulate.
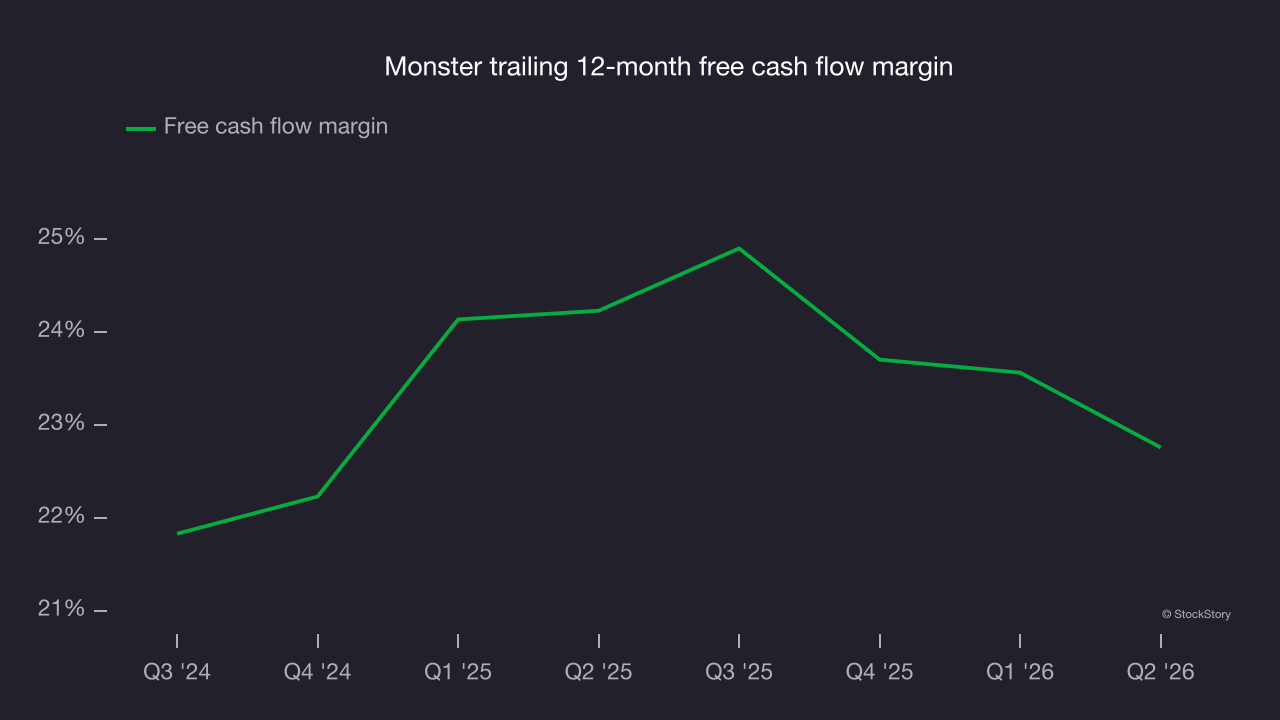
Monster has shown strong cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 22.6% over the last two years.
Key takeaways from Monster’s Q3 results
Monster’s Q3 had some key positives, with revenue topping analysts’ consensus estimates, but gross margin missed expectations. The market appeared to have been hoping for more: Shares tumbled 5.4% to $45.26 immediately after the results.
Should you invest in Monster at its current price? When making that decision, it’s important to consider its valuation, business quality and what has happened in the latest quarter. Read our full research report here (it’s free).