Liquified natural gas infrastructure provider Excelerate Energy (NYSE: EE) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 24% year on year to $297.2 million. Its non-GAAP profit of $0.44 per share was 2.8% above analysts’ consensus estimates.
For more on Excelerate Energy, read our free full research report.
Excelerate Energy (EE) Q3 2026 highlights:
- Revenue $297.2 million vs S&P analysts’ consensus estimates of $371.2 million (24% year-on-year decline, 19.9% miss)
- Adjusted EPS $0.44 vs S&P analysts’ consensus estimates of $0.43 (2.8% beat)
- Adjusted EBITDA $133.5 million vs analysts’ consensus estimates of $128.6 million (44.9% margin, 3.8% beat)
- Operating margin 31.8%, up from 22.3% in the same quarter last year
- Market capitalization $1.10 billion
Kobos continued, "We also made meaningful commercial progress, securing new long-term agreements, extending existing ones, and expanding in the Caribbean with the planned Bahamas LNG Hub. The opportunities we've advanced span our footprint, adding diversity to our portfolio and reinforcing our position as a global provider of critical LNG infrastructure. This progress expands our contracted earnings base and advances our sequenced growth strategy, which we believe will create lasting value for our shareholders."
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can perform well for a year or so, but a top-tier one should exhibit resilience through cycles. Excelerate Energy’s 16.6% annualized revenue growth over the last five years was impressive. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
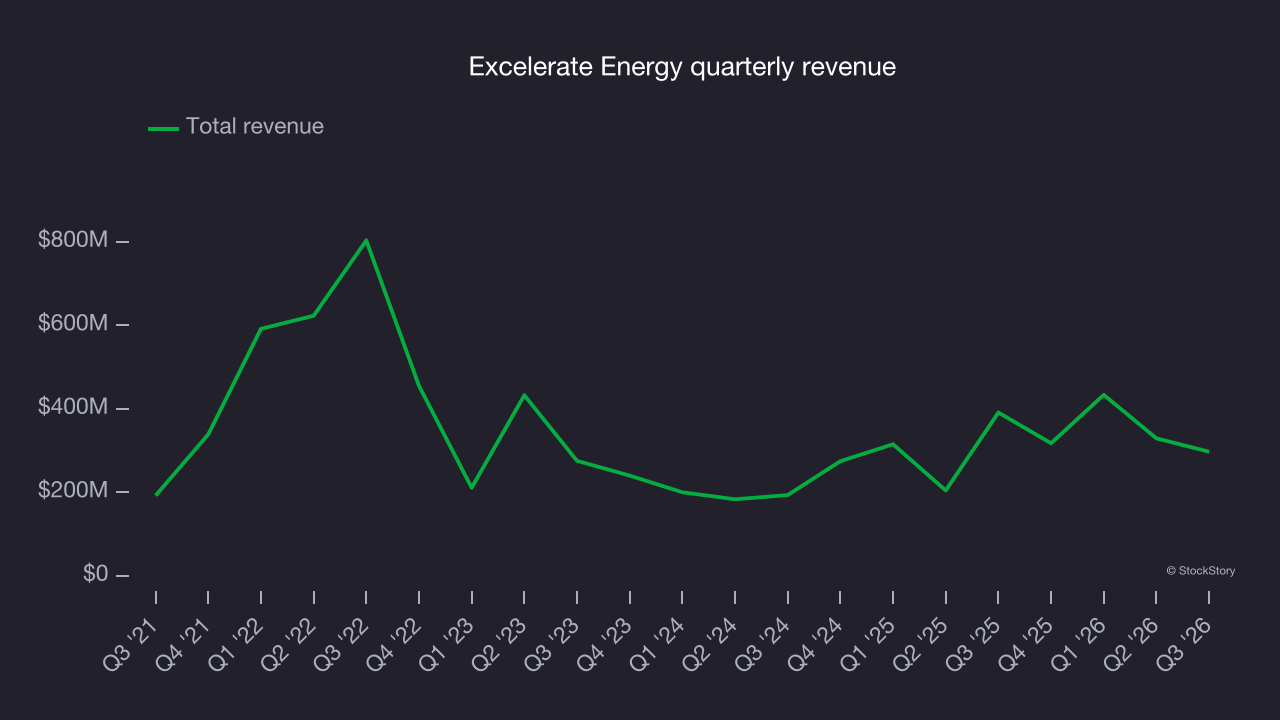
This quarter, Excelerate Energy missed Wall Street’s consensus estimates and reported an uninspiring 24% year-on-year revenue decline, generating $297.2 million of revenue.
Adjusted EBITDA margin
Excelerate Energy was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 26.3% was weak for an upstream and integrated energy business.
On the positive side, Excelerate Energy’s EBITDA margin rose by 24.3 percentage points over the last year.
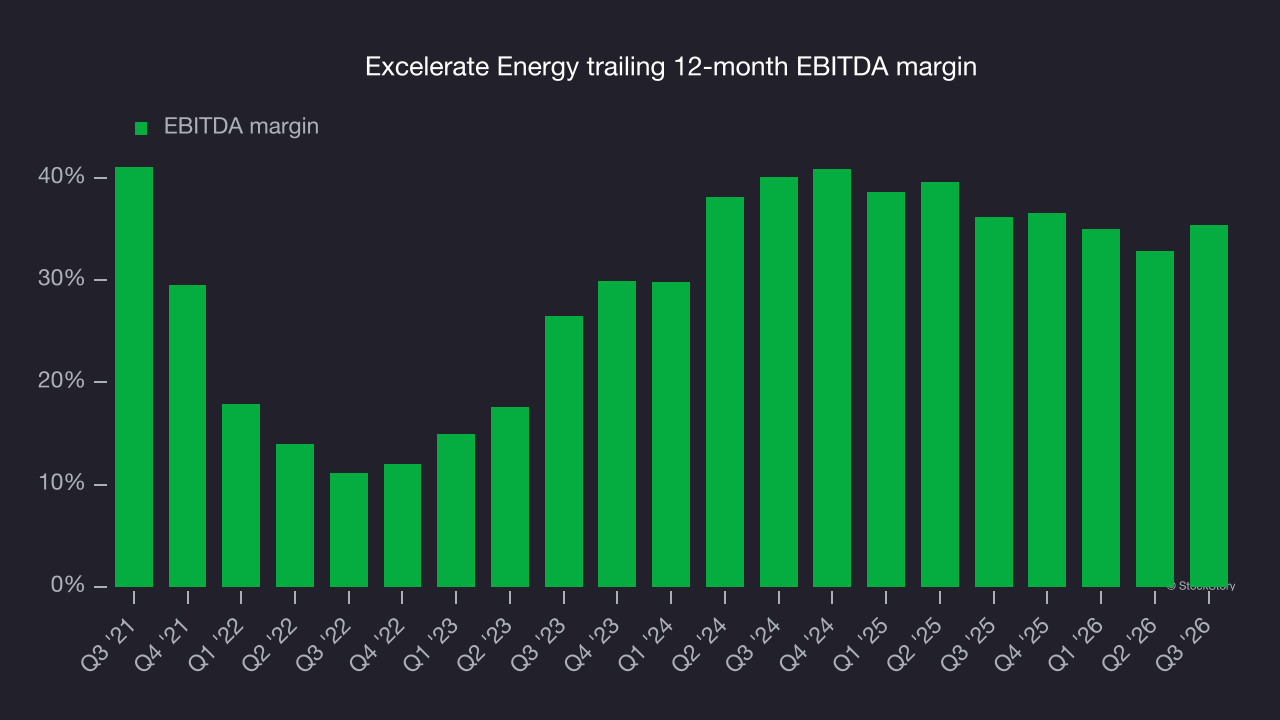
This quarter, Excelerate Energy generated an EBITDA margin of 44.9%, up 11.8 percentage points year on year. This increase was a positive development, especially since its revenue fell, indicating greater efficiency as it reduced expenses. Its adjusted EBITDA beat Wall Street’s consensus estimates by 3.8%.
Key takeaways from Excelerate Energy’s Q3 results
Excelerate Energy posted a softer quarter overall, with revenue missing expectations even as EBITDA and EPS topped analysts’ consensus estimates. Shares fell 2.3% to $33.50 immediately after the report.
When deciding whether to buy Excelerate Energy, consider the broader picture of valuation and business quality as well as the latest earnings. For more on Excelerate Energy, read the full research report here (it’s free).