Specialized equipment manufacturer for infrastructure and vegetation management Alamo Group (NYSE: ALG) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 4% year on year to $403.1 million. Its non-GAAP profit of $2.06 per share was 21.4% below analysts’ consensus estimates.
For more on Alamo, read our free full research report.
Alamo (ALG) Q3 2026 highlights:
- Revenue $403.1 million vs S&P analysts’ consensus estimates of $437.1 million (4% year-on-year decline, 7.8% miss)
- Adjusted EPS $2.06 vs S&P analysts’ consensus estimates of $2.62 (21.4% miss)
- Adjusted EBITDA $52.35 million vs analysts’ consensus estimates of $60.35 million (13% margin, 13.3% miss)
- Operating margin 0.9%, down from 8.9% in the same quarter last year
- Free cash flow margin 13.6%, similar to the same quarter last year
- Market capitalization $1.80 billion
Mr. Hureau commented, "I am pleased with the continued, steady improvement in our Vegetation Management Division as our leadership team executes well against its operational priorities and drives meaningful progress toward our long-term objective of restoring the Division's operating margins to healthy levels. We remain focused on the factors within our control and confident in the progress our teams are making to strengthen performance and drive long-term profitability. Our Industrial Equipment Division experienced margin pressure during the quarter from elevated material and freight costs. We have taken decisive pricing actions to address these higher costs, although the timing of those actions lagged inflation during the quarter. Importantly, while revenue declined from the prior year, order intake strengthened during the third quarter, with particularly encouraging activity in vacuum trucks and sweepers, reinforcing our confidence in the underlying strength of the business."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can post a good quarter or two, but many enduring ones grow for years. Alamo’s revenue grew at a tepid 5% annualized rate over the last five years, falling short of the industrials sector standard.
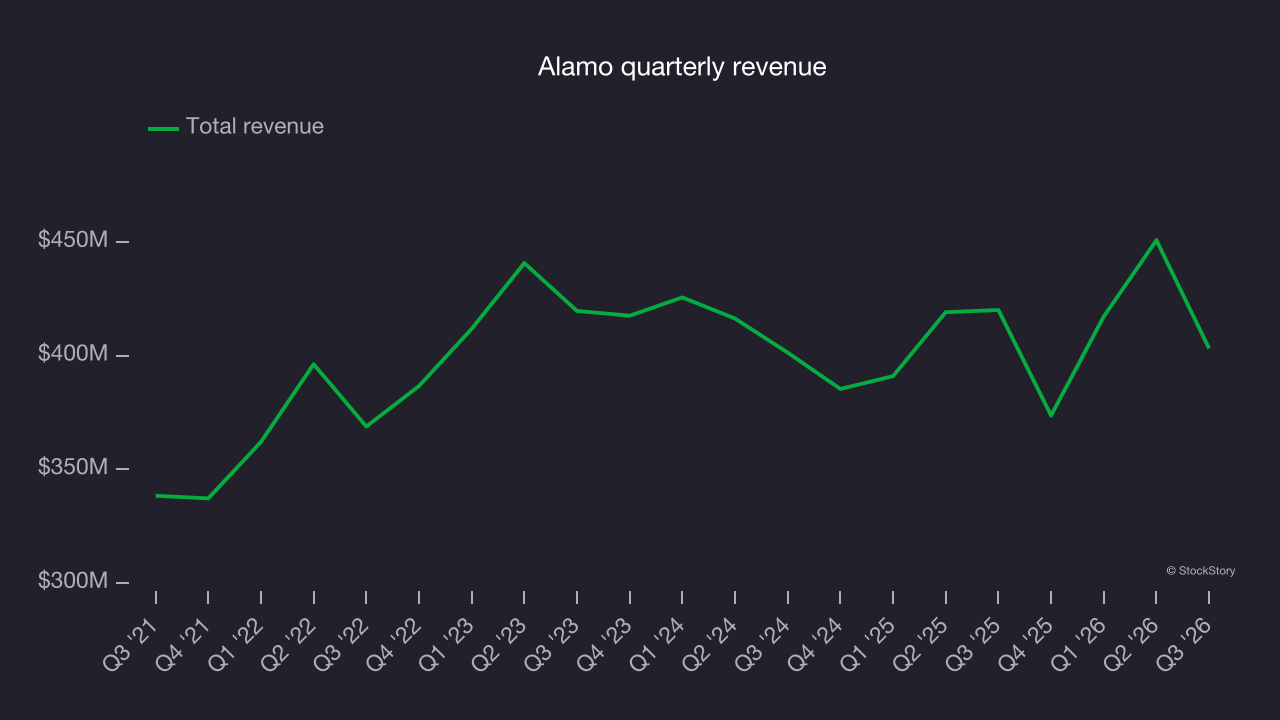
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Alamo’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 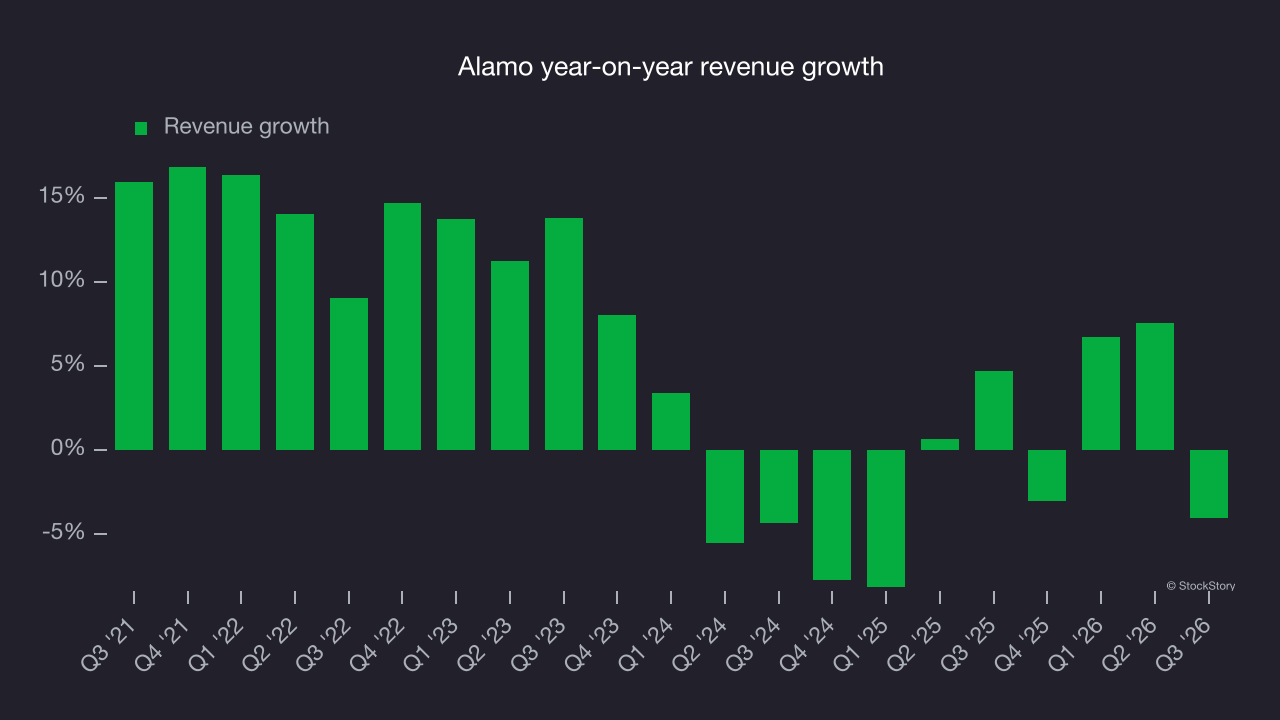
This quarter, Alamo missed Wall Street’s consensus estimates and reported an uninspiring 4% year-on-year revenue decline, generating $403.1 million of revenue.
Looking ahead, sell-side analysts expect revenue to grow 6.5% over the next 12 months, according to S&P. Although this projection implies its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
Alamo has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 9.7%, higher than the broader industrials sector.
Looking at the trend in its profitability, Alamo’s operating margin decreased by 2.2 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
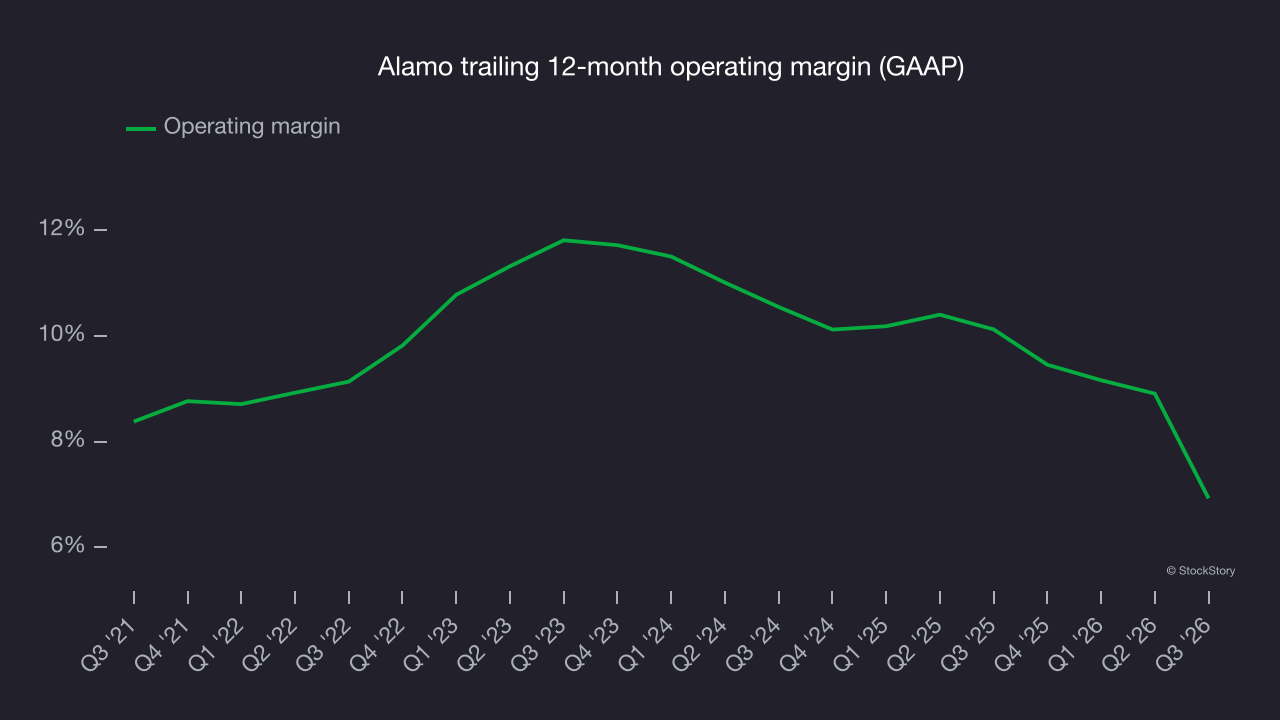
In Q3, Alamo’s breakeven margin was 0.9%, down 8.1 percentage points year on year. Since Alamo’s operating margin decreased more than its gross margin, it appears to have been less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Alamo’s EPS grew at an 8.3% compounded annual growth rate over the last five years, higher than its 5% annualized revenue growth. However, that growth warrants caution because its operating margin didn’t improve and it didn’t repurchase its shares, meaning the difference came from reduced interest expenses or taxes.
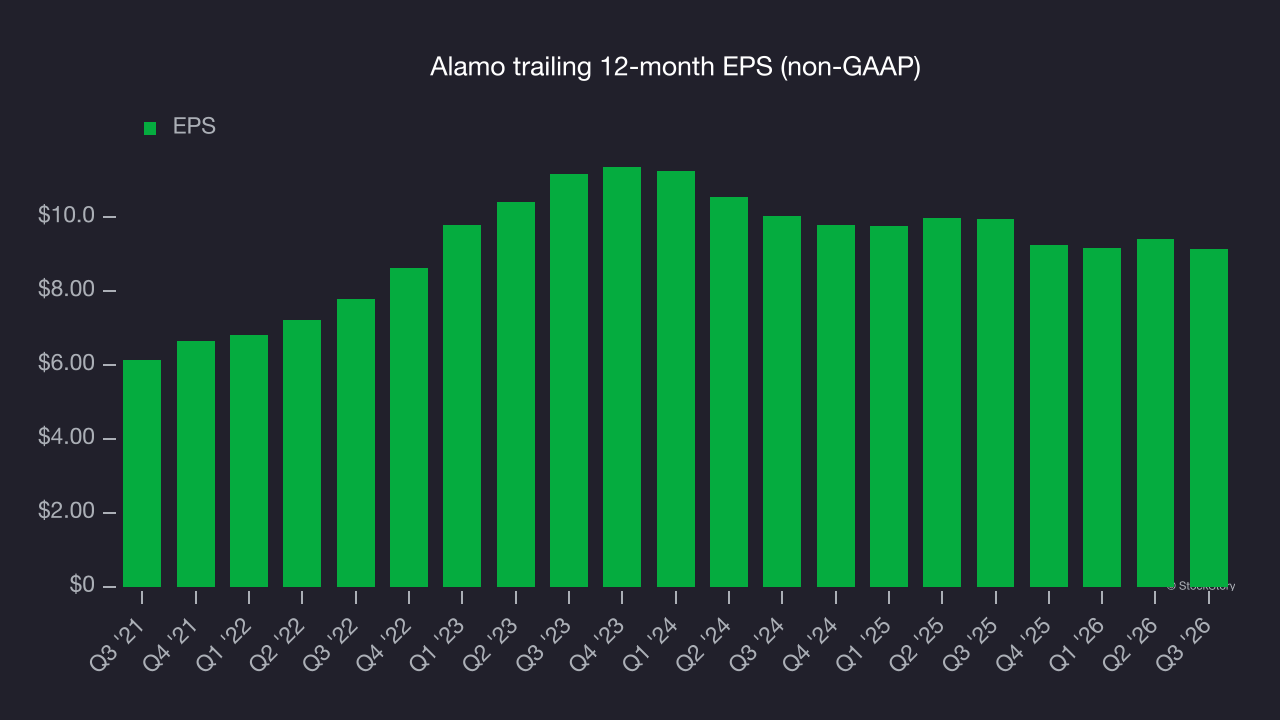
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
Alamo’s EPS declined 4.5% annually over the last two years, a poor result that trailed its flat revenue.
We can take a deeper look into Alamo’s earnings to better understand the drivers of its performance. Alamo’s operating margin has declined over the last two years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Alamo reported adjusted EPS of $2.06, down from $2.34 in the same quarter last year. This result missed analysts’ consensus estimates, but long-term adjusted EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects Alamo’s full-year EPS to grow 26.1% from $9.14 to $11.53, according to S&P.
Key takeaways from Alamo’s Q3 results
Alamo’s Q3 was short on positives, with revenue and EBITDA both falling short of Wall Street’s consensus estimates. Those misses made for a softer quarter overall. Shares tumbled 7% to $142.20 immediately after the results.
Alamo had an underwhelming quarter, but does that create an opportunity to buy the stock? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on Alamo, read our full research report here (it’s free).