Cybersecurity exposure management company Tenable (NASDAQ: TENB) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 9.5% year on year to $276.4 million. Guidance for next quarter’s revenue was better than expected at $278.5 million at the midpoint, 0.7% above analysts’ consensus estimates. Its non-GAAP profit of $0.63 per share was 24.1% above analysts’ consensus estimates.
For more on Tenable, read our free full research report.
Tenable (TENB) Q3 2026 highlights:
- Revenue $276.4 million vs S&P analysts’ consensus estimates of $271.4 million (9.5% year-on-year growth, 1.8% beat)
- Adjusted EPS $0.63 vs S&P analysts’ consensus estimates of $0.51 (24.1% beat)
- Adjusted operating income $74.89 million vs analysts’ consensus estimates of $67.6 million (27.1% margin, 10.8% beat)
- Revenue guidance $278.5 million at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $2.18 at the midpoint, a 10.1% increase
- Operating margin 6%, up from 2.8% in the same quarter last year
- Free cash flow margin 23.2%, up from 14.6% in the previous quarter
- Market capitalization $5.36 billion
“We delivered an excellent third quarter, exceeding every one of our guided metrics,” said Steve Vintz, Co-CEO of Tenable. “As AI creates a structural shift in how organizations manage cyber exposure, security is becoming its own business function tied to business risk and growth, and we believe Tenable is uniquely positioned to lead in this new era.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Tenable grew its revenue at a 15.9% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough to assess the software sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year CAGR starts around Covid, when revenue was depressed then rebounded.
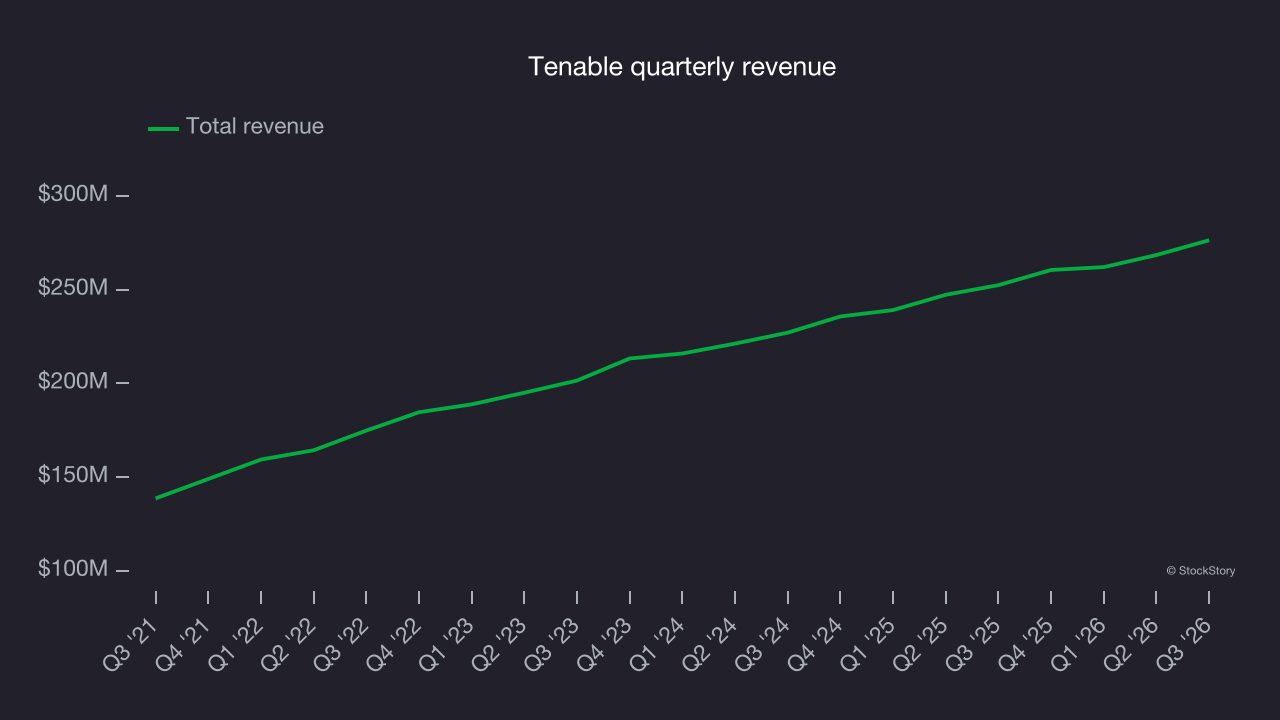
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Tenable’s recent performance shows its demand has slowed as its annualized revenue growth of 10.3% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 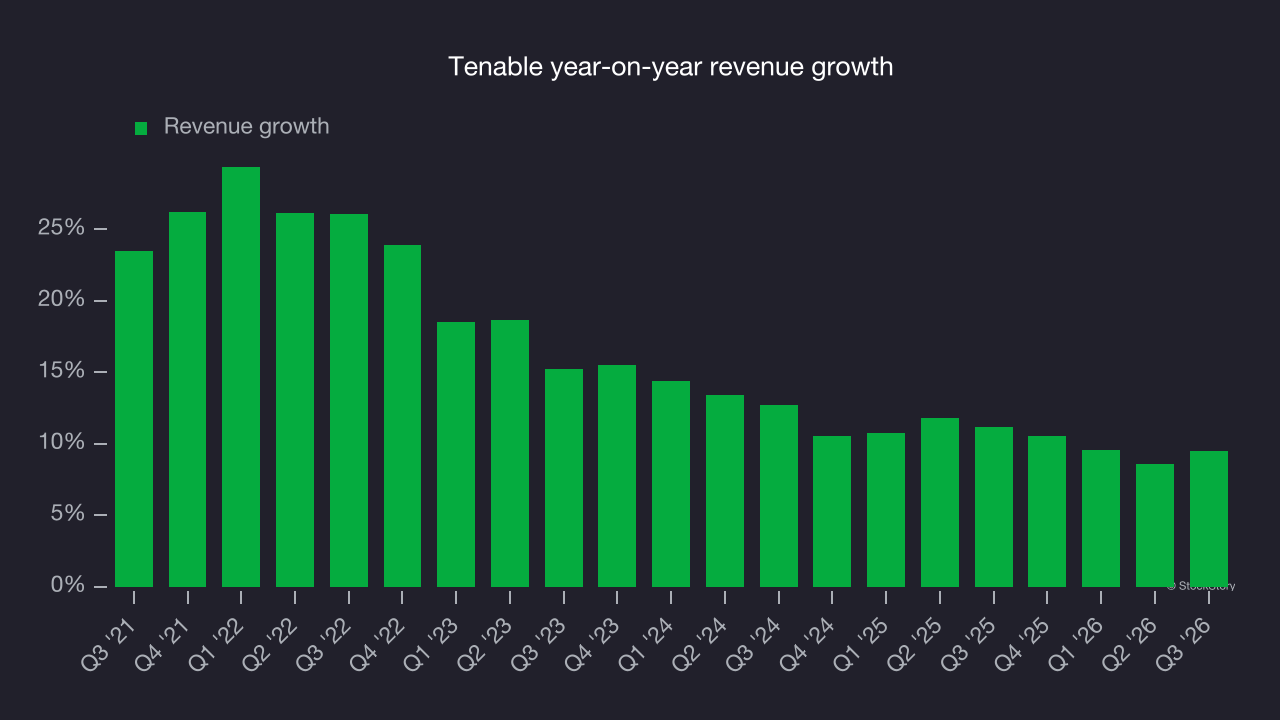
This quarter, Tenable reported year-on-year revenue growth of 9.5%, and its $276.4 million of revenue exceeded Wall Street’s consensus estimates by 1.8%. Company management is currently guiding for a 6.9% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 6.4% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will see some demand headwinds.
Customer acquisition efficiency
The customer acquisition cost (CAC) payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
It’s relatively expensive for Tenable to acquire new customers as its CAC payback period was 107.7 months this quarter. The company’s slow recovery of its sales and marketing expenses indicates it operates in a highly competitive market and must invest to stand out, even if the return on that investment is low.
Key takeaways from Tenable’s Q3 results
Tenable delivered a solid quarter, with adjusted operating income beating Wall Street’s consensus estimates by a wide margin and next-quarter EPS guidance also coming in well above analysts’ consensus estimates. Shares rose 2.6% to $49.99 immediately after the results.
Tenable may have had a good quarter, but does that mean you should invest right now? When making that decision, it’s important to consider its valuation and business quality as well as what happened in the latest quarter. For more on Tenable, read our full research report here (it’s free).