Online advertising giant Alphabet (NASDAQ: GOOGL) met Wall Street’s revenue expectations in Q3 2026, with revenue up 24.7% year on year to $127.6 billion. Its GAAP profit of $2.12 per share was 29.5% below analysts’ consensus estimates.
For more on Alphabet, read the full research report for free.
Alphabet (GOOGL) Q3 2026 highlights:
- Revenue $127.6 billion vs S&P analysts’ consensus estimates of $127.9 billion (in line)
- EPS (GAAP) $2.12 vs analysts’ consensus estimates of $3.01 (29.5% miss, partly driven by a loss on equity securities of $8.7 billion vs. a gain of $10.7 billion in the same quarter last year)
- Operating margin 31.8%, up from 30.5% in the same quarter last year
- Free cash flow margin -7.1%, down from 23.9% in the same quarter last year
- Market capitalization $3.9 trillion
Revenue growth
Alphabet shows that fast growth and large scale can coexist despite conventional wisdom. The company’s revenue base of $239.2 billion five years ago has nearly doubled to $471.1 billion in the last year, translating into a strong 14.5% annualized growth rate.
Alphabet’s growth over the same period was also higher than its big tech peers, Amazon (11.4%), Microsoft (14.2%) and Apple (5.2%). This is an important consideration because investors often use the comparisons as a starting point for their valuations. With these benchmarks in mind, Alphabet is a bit expensive but still worth owning.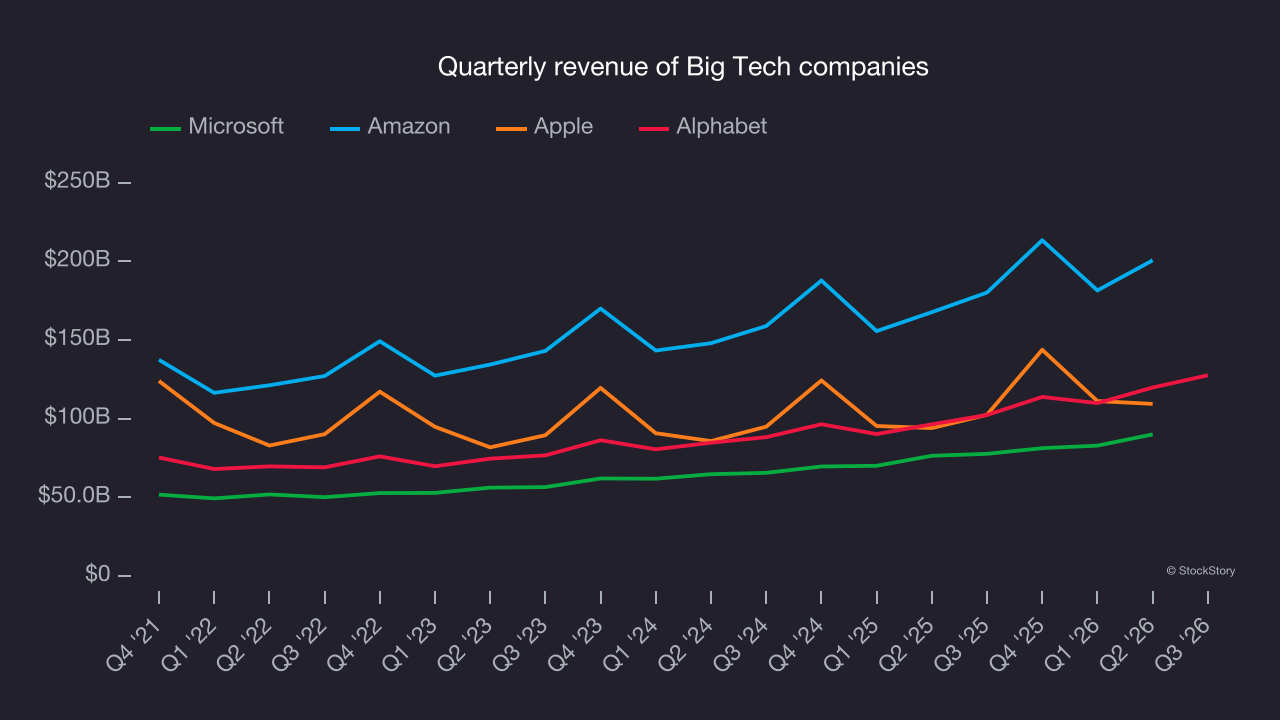
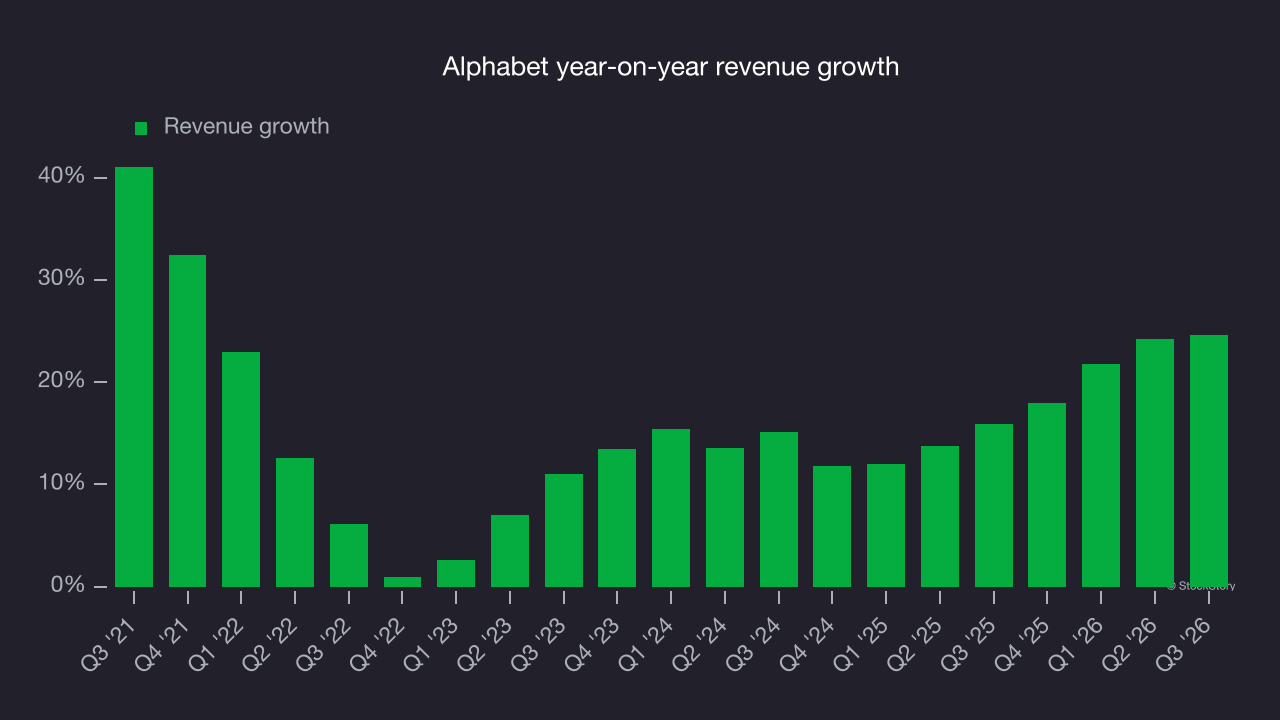
This quarter, Alphabet’s year-on-year revenue growth of 24.7% was strong, and its $127.6 billion of revenue was in line with Wall Street’s consensus estimates. Looking ahead, this projection is notable for a company of its scale and illustrates that the market sees it as a beneficiary of the AI trend rather than a victim.
Google Search: Alphabet’s core business
The most topical question surrounding Alphabet today is: “Will new Generative-AI products like ChatGPT and Meta AI disrupt Google Search and its 80%+ market share?”
Although OpenAI (creator of ChatGPT) doesn’t disclose its financials, comparing Google Search with Meta offers further insight. Meta essentially has a monopoly in social media advertising and is moving into search with Meta AI, which is powered by its Llama large language model.
Starting with Alphabet, Google Search accounts for by far the largest portion of its revenue at 53.1%, and it grew at a 12.1% annualized rate over the last five years, slower than total revenue. It accelerated in recent years, however, growing 14.1% annually over the last two years.
On the other hand, its two-year result was lower than Meta’s 24.4%, showing digital advertising dollars could be flowing to Meta because of its improved AI algorithms and targeting capabilities. Alphabet bulls would argue this trend could reverse because the return on investment from keyword-driven advertising is more tangible, but that hasn’t been the case lately.
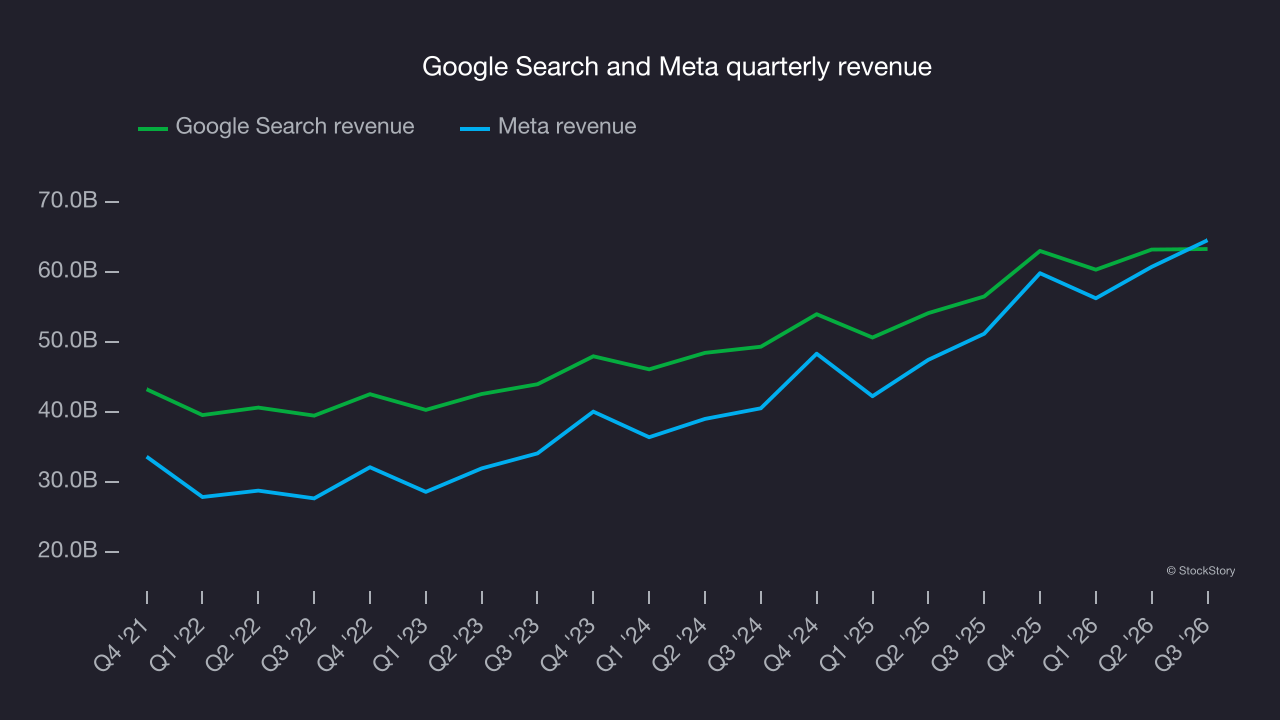
Quarterly performance is particularly relevant for Alphabet because it captures the growth of AI and signals whether investors are overestimating its competitive impact. Google Search revenue recorded a strong year-on-year increase of 12% in Q3.
Key takeaways from Alphabet’s Q3 results
We struggled to find many positives in these results. Its EPS missed and its free cash flow margin decline meaningfully year-on-year. Overall, this quarter could have been better. The stock traded down 8.3% to $299.54 immediately following the results.
Alphabet’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so assessing whether the stock is a buy at the current price requires a broader view. When making that decision, it’s important to consider its valuation, business qualities and latest quarterly results. For more on Alphabet, read our full research report here (it’s free).