Heavy equipment distributor Custom Truck One Source (NYSE: CTOS) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 2.7% year on year to $495.2 million. On the other hand, the company’s full-year revenue guidance of $2.15 billion at the midpoint came in 1.2% above analysts’ consensus estimates. Its GAAP profit of $0.01 per share was in line with analysts’ consensus estimates.
For more on Custom Truck One Source, read our free full research report.
Custom Truck One Source (CTOS) Q3 2026 highlights:
- Revenue $495.2 million vs S&P analysts’ consensus estimates of $515 million (2.7% year-on-year growth, 3.8% miss)
- EPS (GAAP) $0.01 vs analysts’ consensus estimates of $0.01 (in line)
- Adjusted EBITDA $110.9 million vs analysts’ consensus estimates of $104.5 million (22.4% margin, 6.2% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $2.15 billion at the midpoint
- EBITDA guidance $453.8 million at the midpoint for the full year, above analysts’ consensus estimates of $447.4 million
- Operating margin 7.7%, in line with the same quarter last year
- Backlog $341.9 million at quarter end, up 22.2% year on year
- Market capitalization $2.06 billion
“In the third quarter, record demand across our core T&D markets drove 16% year-over-year Adjusted EBITDA growth and 24% growth year to date, and we are raising our full-year Adjusted EBITDA outlook for the third time this year. Our SER segment continued to benefit from strong utility end-market demand, with our rental fleet generating a record quarterly average OEC on rent of nearly $1.4 billion and average utilization of 81.5%. We also ended the quarter with record total OEC of $1.76 billion, providing strong visibility into continued SER growth through the fourth quarter and into 2027,” said Ryan McMonagle, Chief Executive Officer of CTOS. “In STEM, orders grew 22% year-over-year and backlog reached $342 million, and the third-party deliveries that shifted out of the quarter are scheduled to ship in the fourth quarter. Our earnings growth also drove a further meaningful reduction in net leverage, to 3.70x. As we look to the remainder of 2026 and beyond, CTOS is well positioned to participate in powerful secular trends, including utility grid upgrades and transmission expansion, electrification, data center-driven load growth, and infrastructure spending. We remain disciplined in executing our strategy, with a focus on profitable growth, strategic capital deployment, free cash flow generation, and continued deleveraging. Increasing our investment in the rental fleet reflects that discipline as we put capital behind visible, long-duration transmission demand at attractive returns, with the larger earnings benefit arriving in 2027.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Custom Truck One Source grew its revenue at an 11.3% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
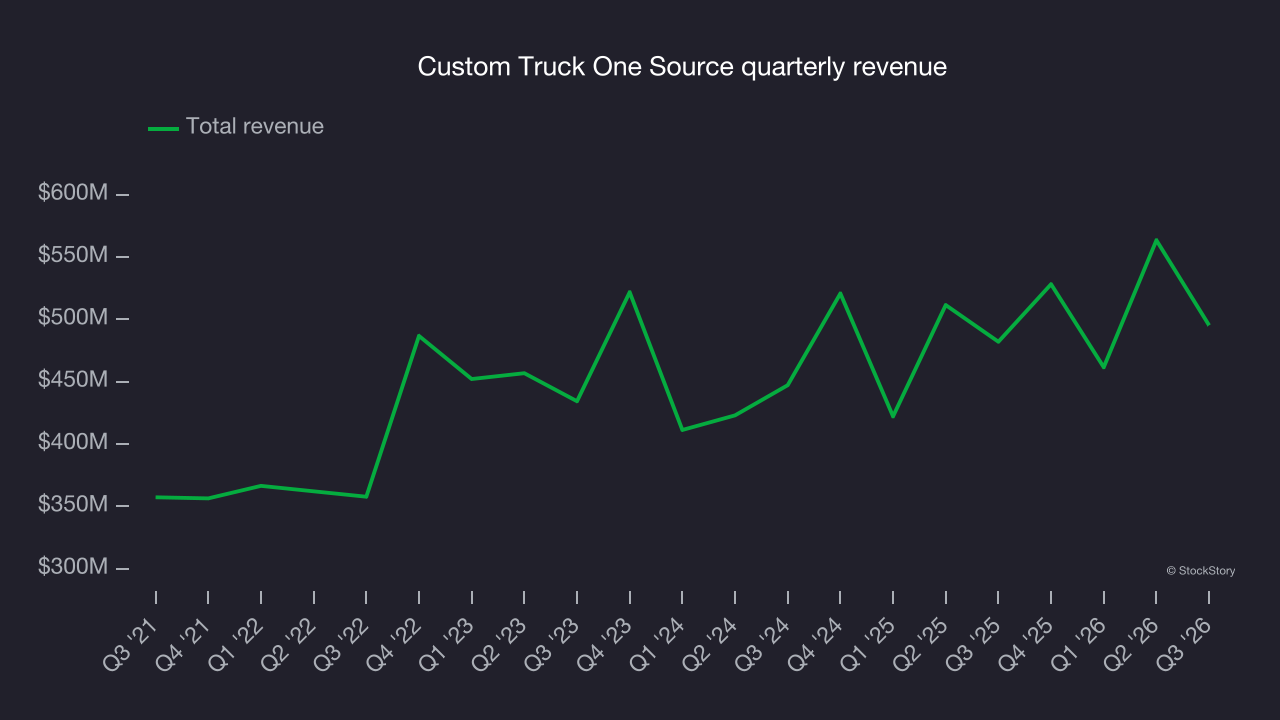
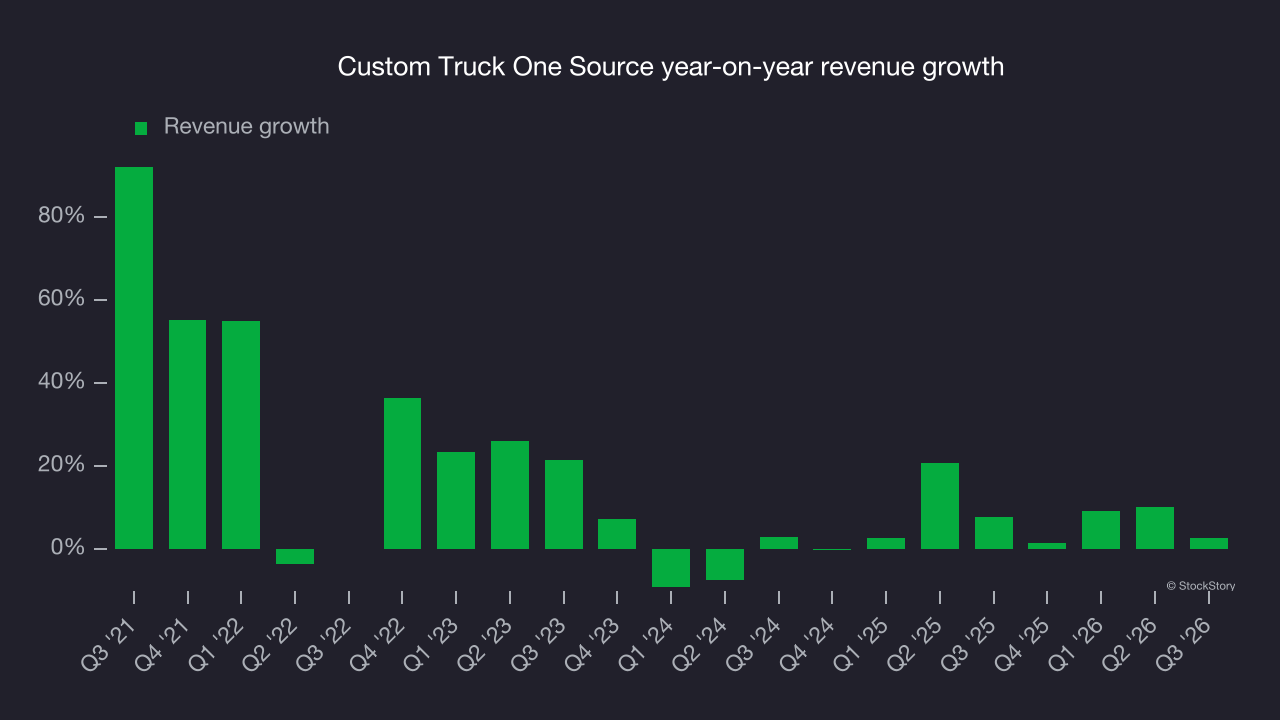
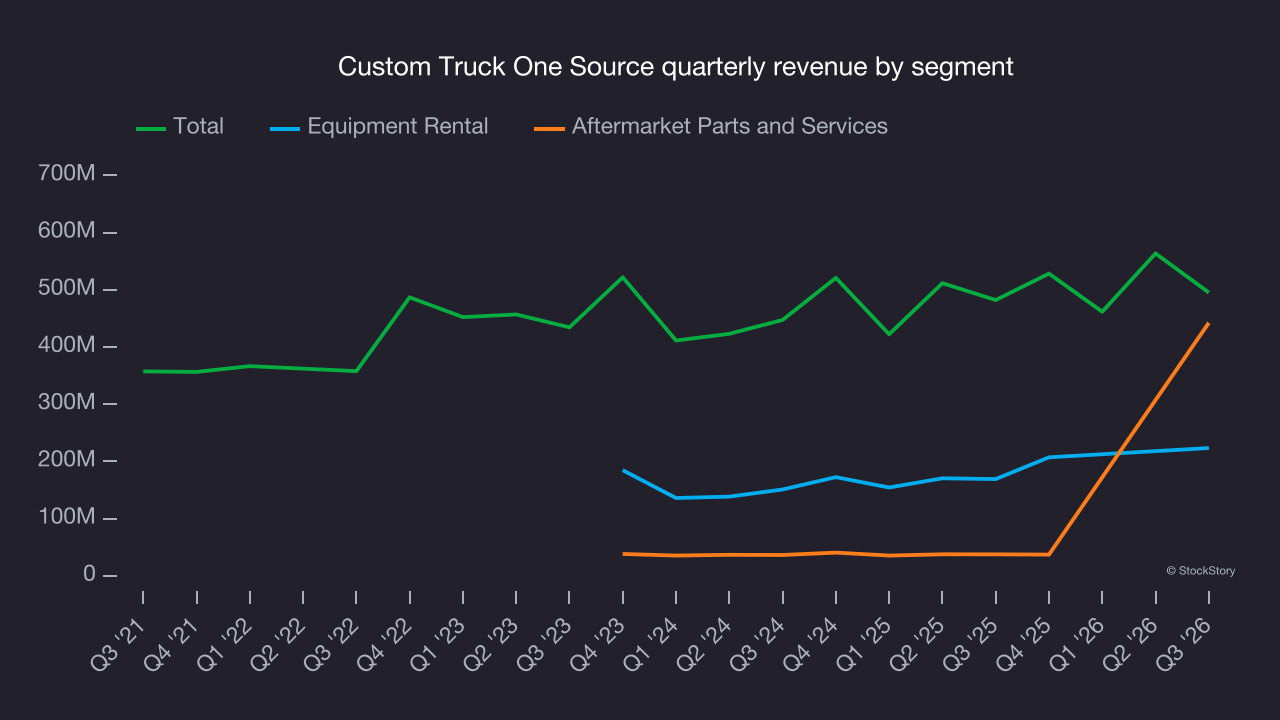
This quarter, Custom Truck One Source’s revenue grew by 2.7% year on year to $495.2 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 7.2% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not accelerate its top-line performance yet. At least the company is tracking well in other measures of financial health.
Operating margin
Custom Truck One Source was profitable over the last five years but held back by its large cost base. Its average operating margin of 7.2% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, Custom Truck One Source’s operating margin rose by 3.9 percentage points over the last five years, as its revenue growth provided operating leverage.
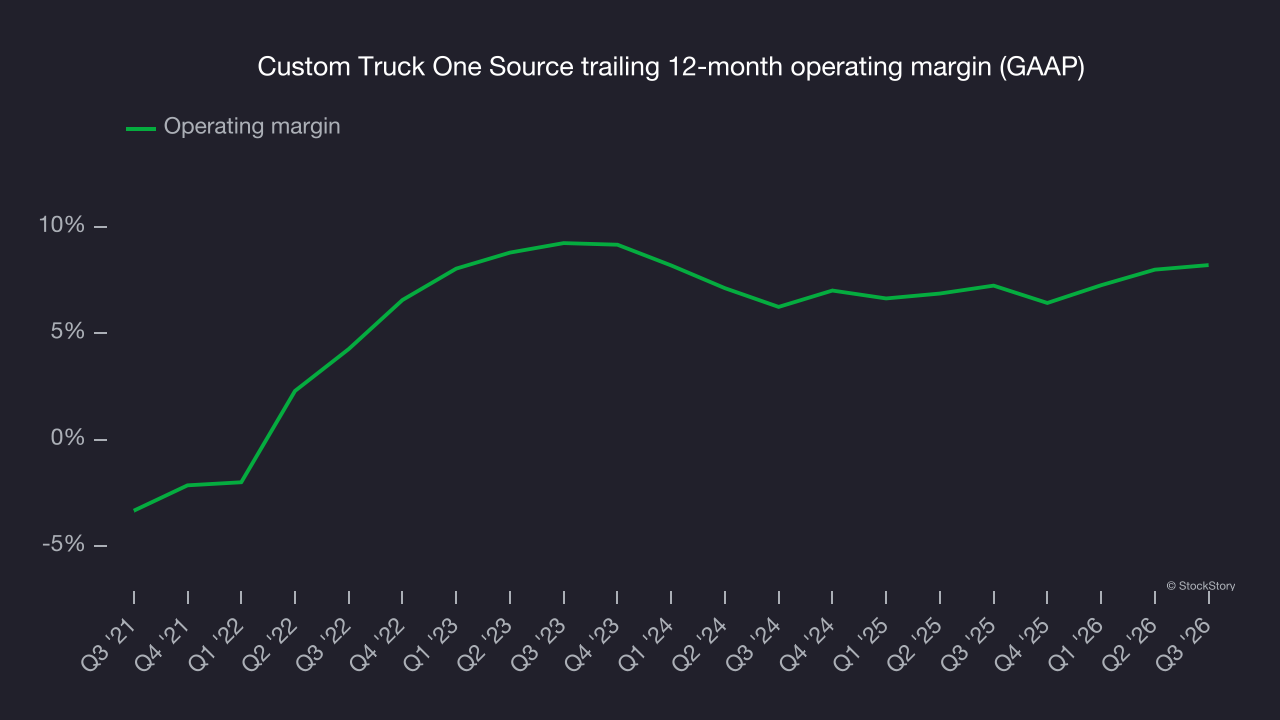
In Q3, Custom Truck One Source generated an operating margin of 7.7%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Custom Truck One Source’s full-year EPS turned positive over the last five years. This is a positive sign and shows it’s at an inflection point.
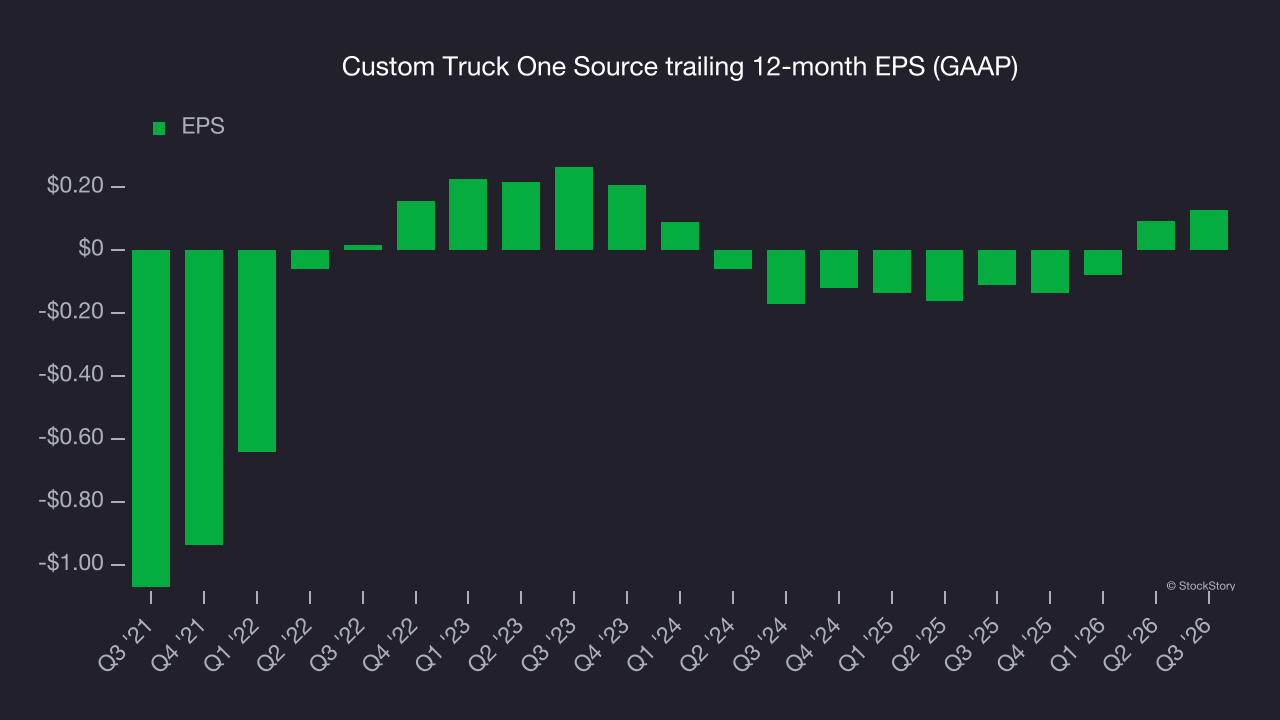
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Custom Truck One Source, its two-year annual EPS growth of 66.2% was higher than its five-year trend. That acceleration is a positive sign, especially coming off an already high base.
In Q3, Custom Truck One Source reported EPS of $0.01, up from negative $0.03 in the same quarter last year. Despite growing year on year, EPS missed analysts’ consensus estimates, but long-term EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects Custom Truck One Source’s full-year EPS to grow 100% from $0.13 to $0.26, according to S&P.
Key takeaways from Custom Truck One Source’s Q3 results
An EBITDA beat and full-year EBITDA guidance slightly above Wall Street’s consensus were the positives in Custom Truck One Source’s softer quarter. Revenue missed consensus estimates, and EPS was in line with expectations. Shares remained flat at $9.00 immediately after the results.
Is Custom Truck One Source worth buying? The latest quarter is only one part of assessing its longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).