Diversified science and technology company Danaher (NYSE: DHR) met Wall Street’s revenue expectations in Q3 2026, with sales up 8.3% year on year to $6.55 billion. Its non-GAAP profit of $2.11 per share was 10% above analysts’ consensus estimates.
Is now the time to buy Danaher? Find out by accessing our full research report, it’s free.
Danaher (DHR) Q3 2026 Highlights:
- Revenue: $6.55 billion vs analyst estimates of $6.56 billion (8.3% year-on-year growth, in line)
- Adjusted EPS: $2.11 vs analyst estimates of $1.92 (10% beat)
- Management slightly raised its full-year Adjusted EPS guidance to $8.59 at the midpoint
- Operating Margin: 19%, in line with the same quarter last year
- Free Cash Flow Margin: 24.9%, up from 22.6% in the same quarter last year
- Organic Revenue rose 3% year on year (beat)
- Market Capitalization: $157.6 billion
Julie Sawyer Montgomery, President and Chief Executive Officer, stated, "We delivered better-than-expected third quarter revenue, earnings and cash flow, and are encouraged by the improving trends we saw across our end markets. The continued acceleration in core revenue growth excluding respiratory revenue, together with DBS-driven execution drove double-digit adjusted EPS growth and underscored our ability to convert improving demand into strong financial performance."
Company Overview
Born from a real estate investment trust that transformed into a manufacturing powerhouse, Danaher (NYSE: DHR) is a global science and technology company that provides specialized equipment, software, and services for biotechnology, life sciences, and diagnostics.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Danaher struggled to consistently increase demand as its $25.61 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and suggests it’s a lower quality business.
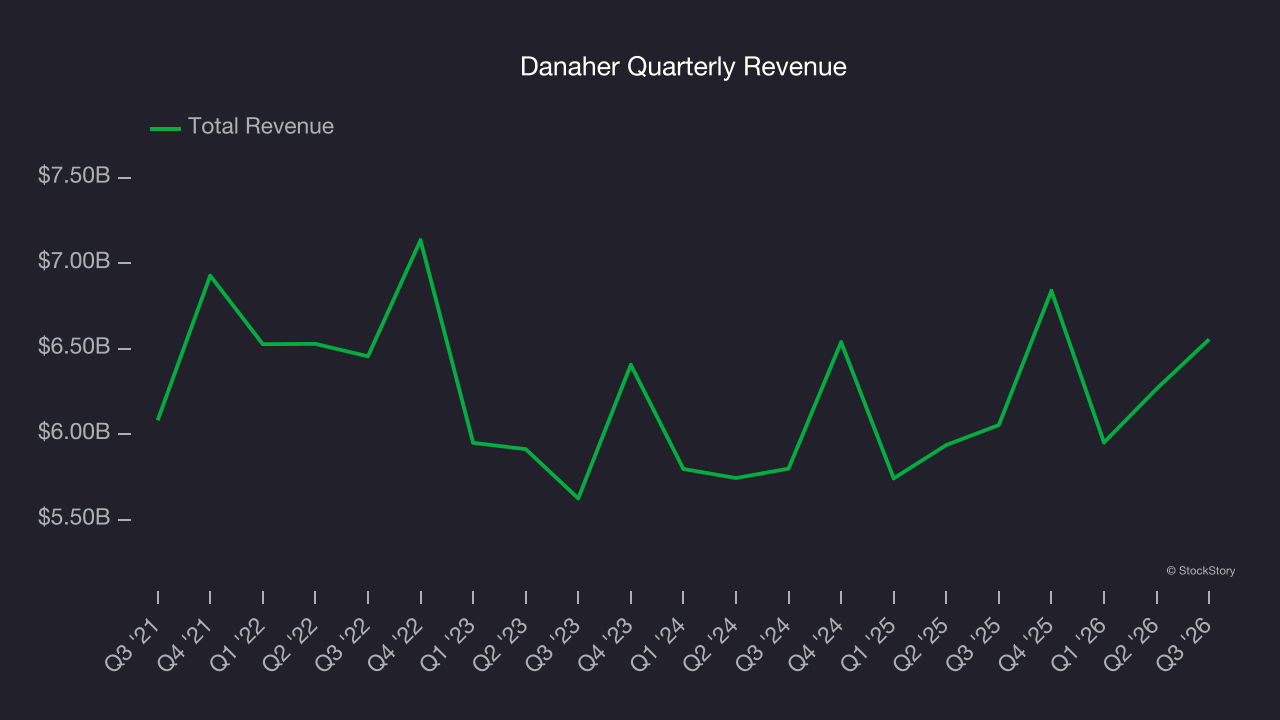
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Danaher’s annualized revenue growth of 3.9% over the last two years is above its five-year trend, which is encouraging. 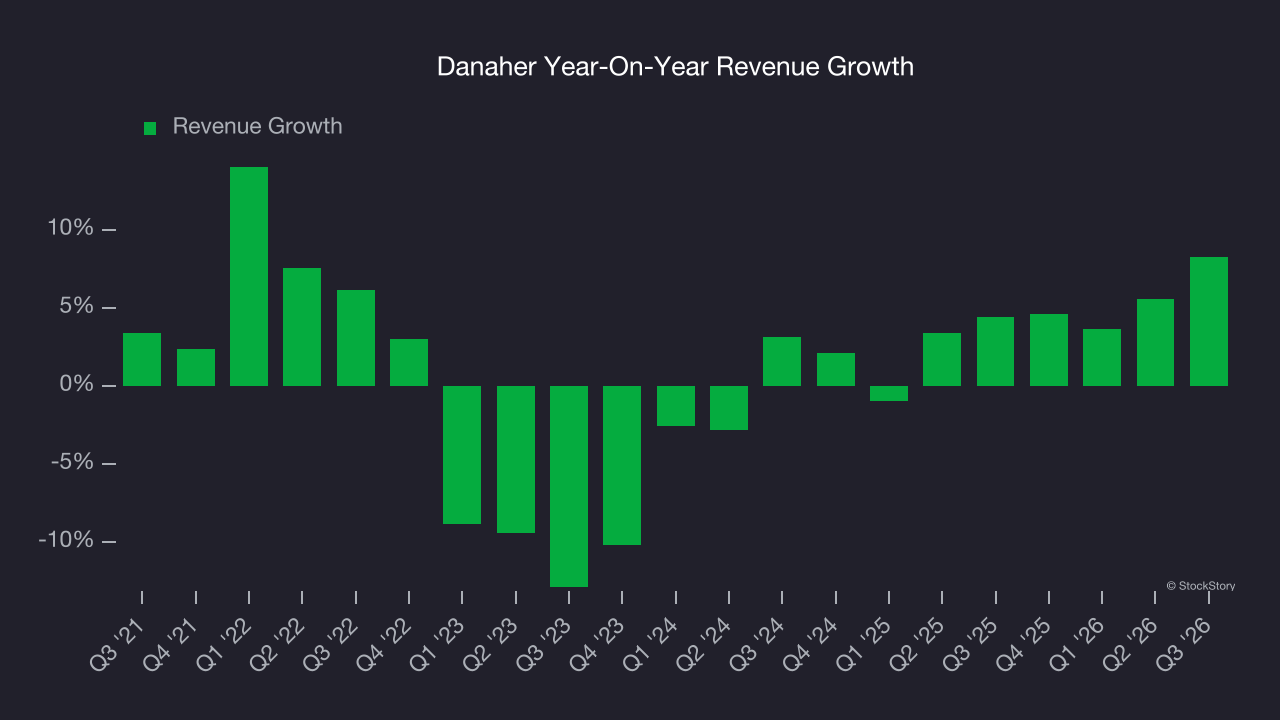
We can better understand the company’s sales dynamics by analyzing its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Danaher’s organic revenue averaged 2.3% year-on-year growth. Because this number is lower than its two-year revenue growth, we can see that some mixture of acquisitions and foreign exchange rates boosted its headline results. 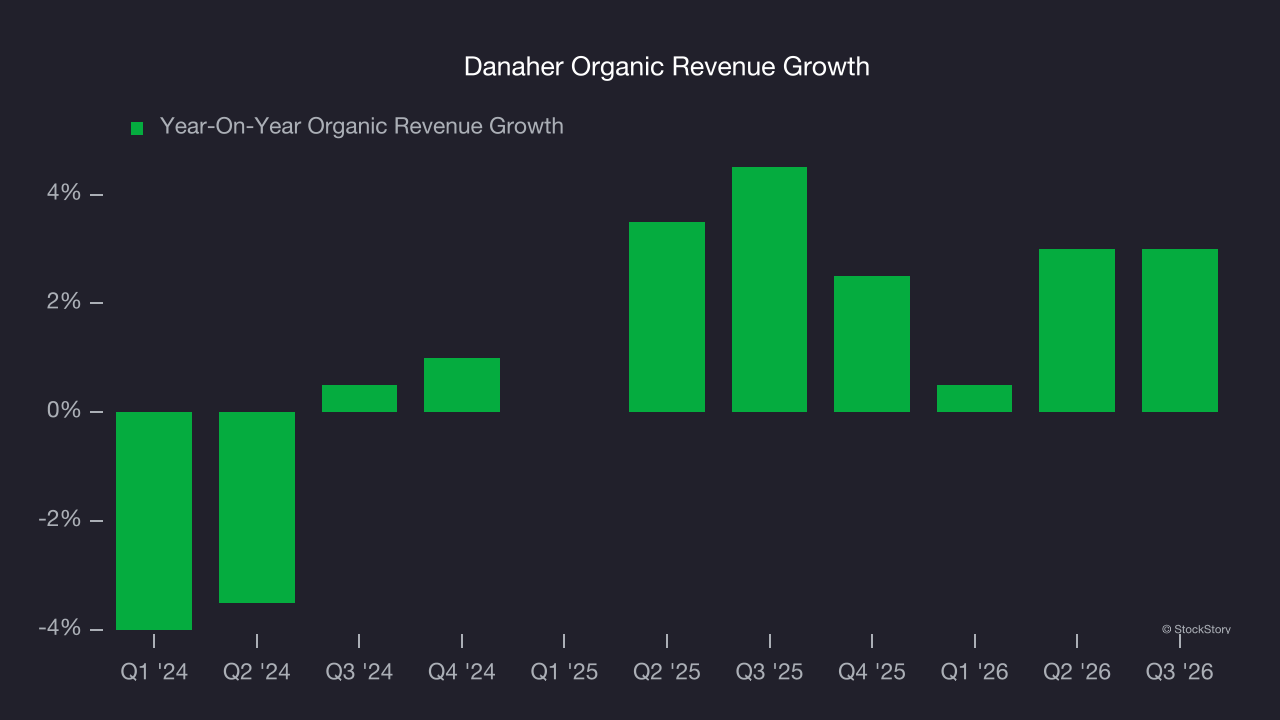
This quarter, Danaher grew its revenue by 8.3% year on year, and its $6.55 billion of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 9.5% over the next 12 months, an improvement versus the last two years. This projection is particularly healthy for a company of its scale and implies its newer products and services will catalyze better top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes, and interest on debt - metrics less connected to business fundamentals.
Danaher has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, boasting an average adjusted operating margin of 29.6%.
Looking at the trend in its profitability, Danaher’s adjusted operating margin decreased by 8.8 percentage points over the last five years. The company’s two-year trajectory also shows it failed to get its profitability back to the peak as its margin fell by 2.4 percentage points. This performance was poor no matter how you look at it - it shows its expenses were rising and it couldn’t pass those costs onto its customers.
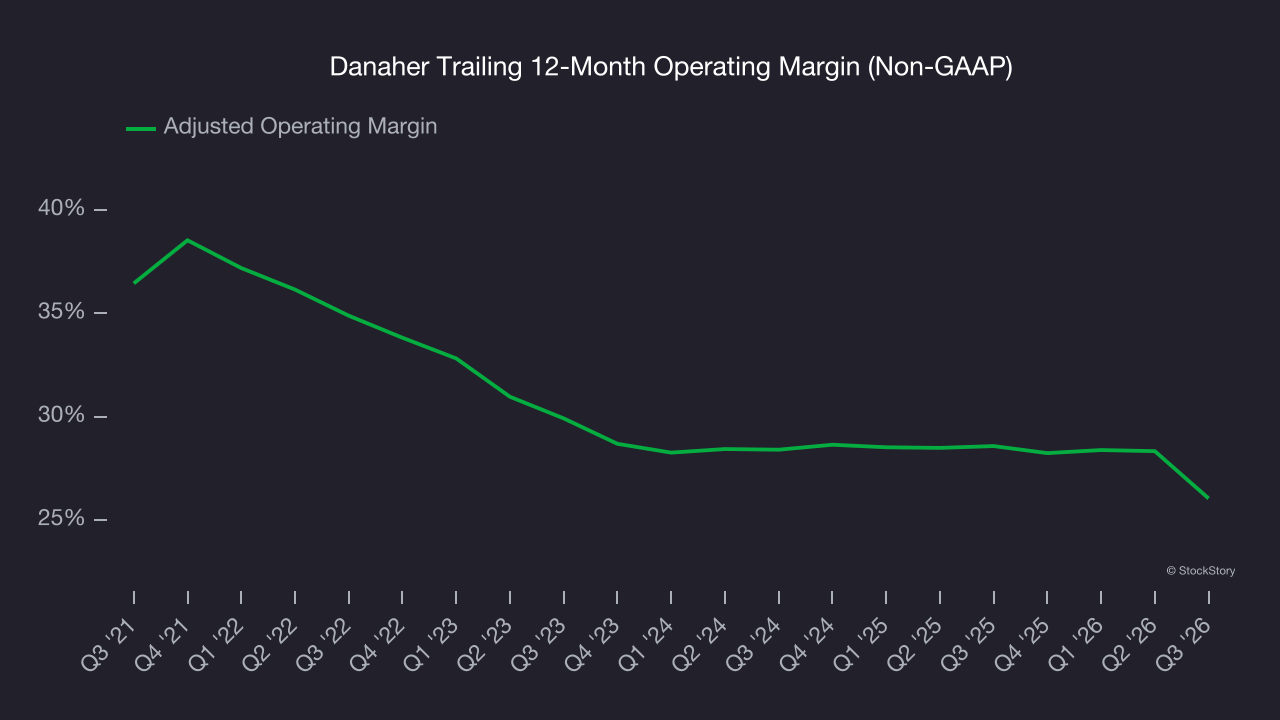
This quarter, Danaher generated an adjusted operating margin profit margin of 19%, down 8.9 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Sadly for Danaher, its EPS declined by 2.5% annually over the last five years while its revenue was flat. This tells us the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
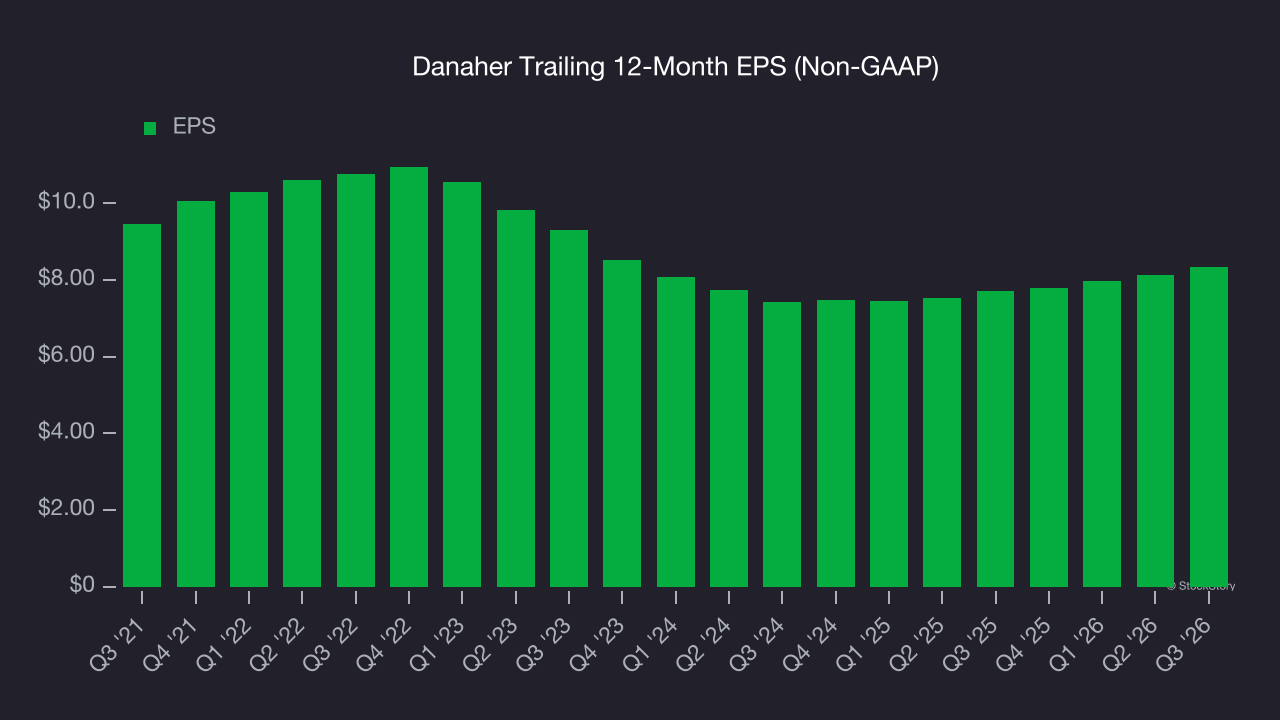
We can take a deeper look into Danaher’s earnings to better understand the drivers of its performance. As we mentioned earlier, Danaher’s adjusted operating margin declined by 8.8 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Danaher reported adjusted EPS of $2.11, up from $1.89 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Danaher’s full-year EPS to grow 8.5% from $8.34 to $9.05.
Key Takeaways from Danaher’s Q3 Results
It was good to see Danaher beat analysts’ EPS expectations this quarter. We were also happy its full-year EPS guidance narrowly outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $225.90 immediately following the results.
Should you buy the stock or not? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).