Vitesse Energy has been treading water for the past six months, holding steady at $18.14. The stock also fell short of the S&P 500’s 8.9% gain during that period.
Does this present a buying opportunity for VTS? Or is its underperformance reflective of its story and business quality? Find out in our full research report, it’s free.
Why Is VTS a Good Business?
Taking a hands-off approach to energy production, Vitesse Energy (NYSE: VTS) owns non-operated stakes in oil and natural gas wells primarily in North Dakota and Montana's Williston Basin.
1. Long-Term Revenue Growth Shows Strong Momentum
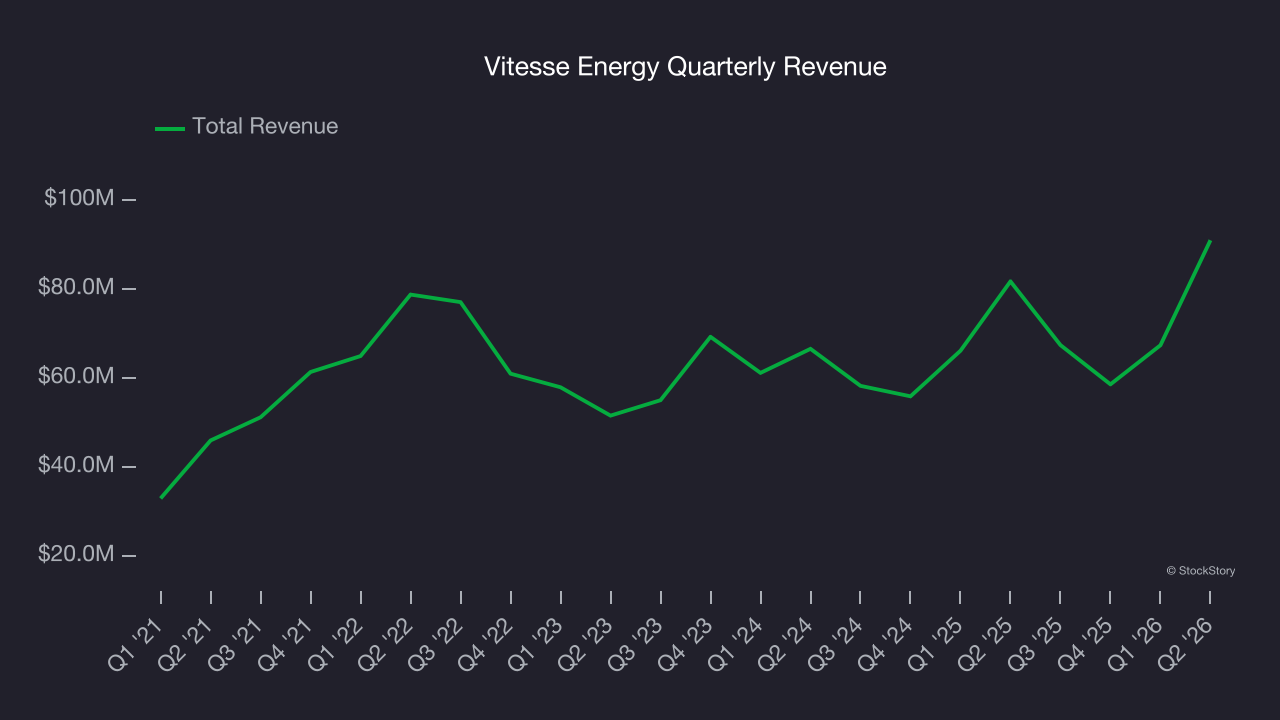
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Over the last five years, Vitesse Energy grew its sales at a solid 14.9% compounded annual growth rate. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite Gross Margin Powers Best-In-Class Business Model
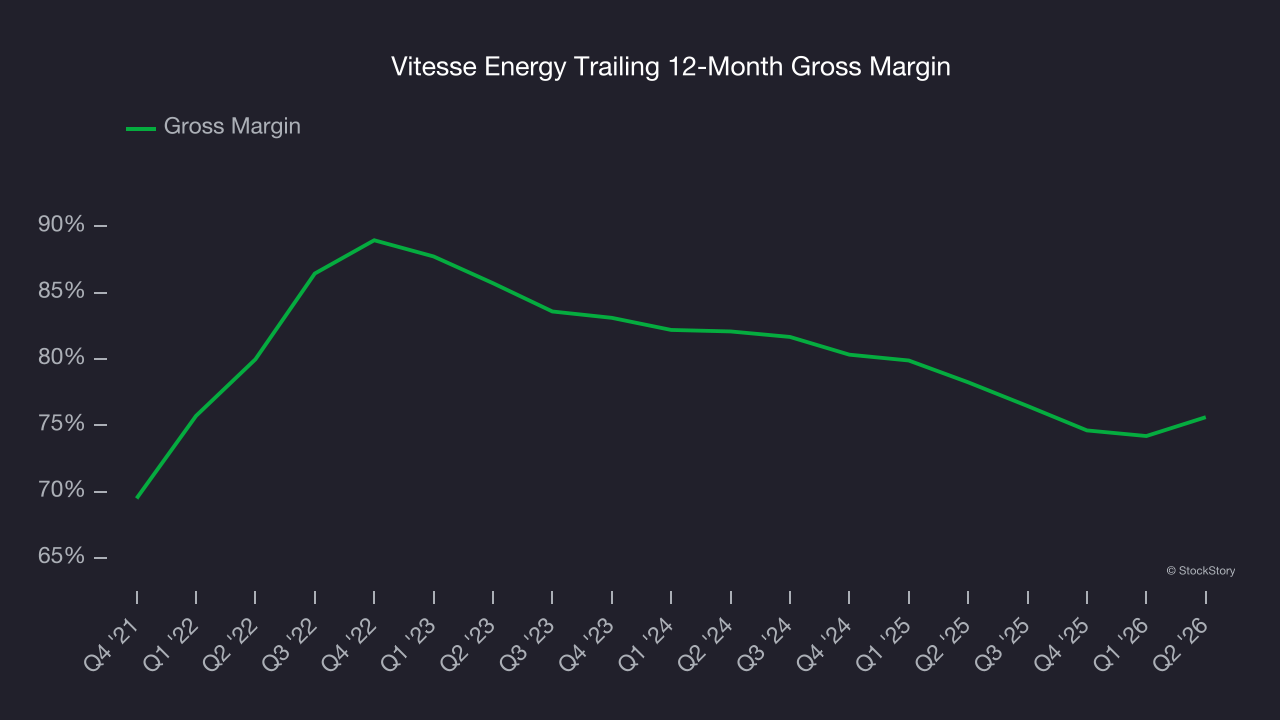
While energy gross margins can be distorted by commodity prices, hedging, and short-term cost swings, sustained margins across a full cycle reflect a producer’s underlying asset quality, infrastructure position, and cost structure.
Vitesse Energy, which averaged 80.2% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
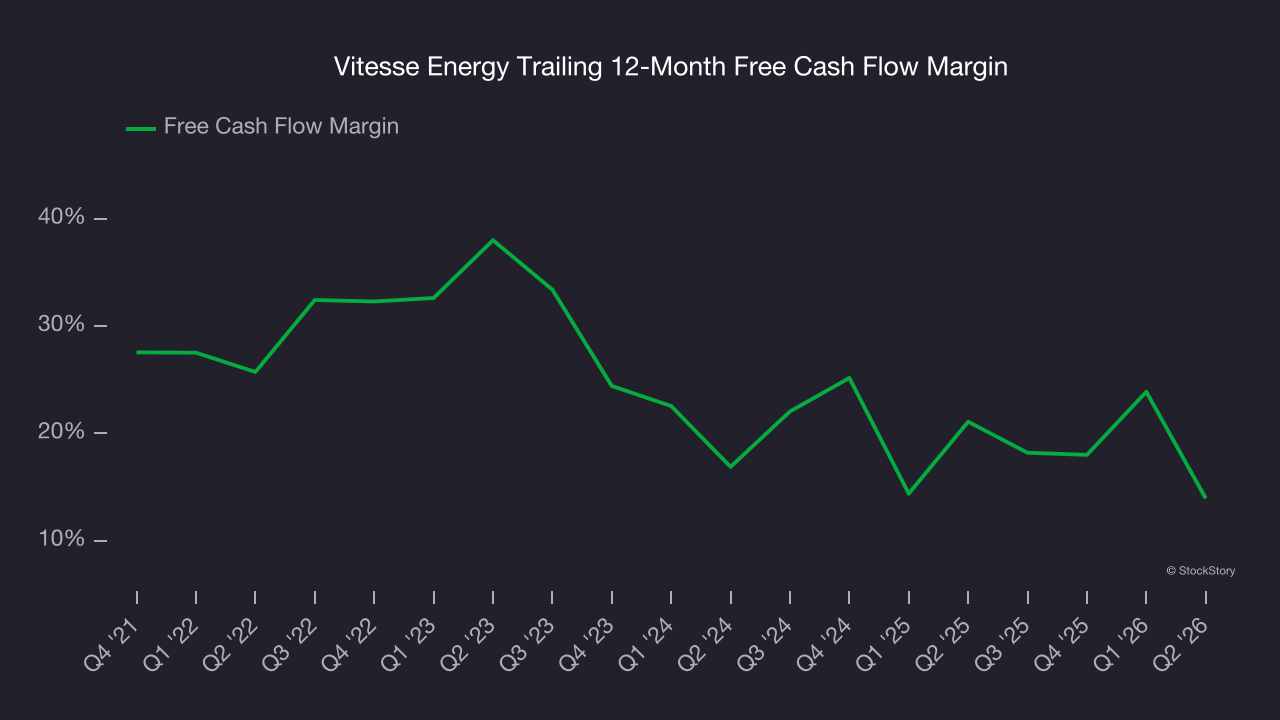
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Vitesse Energy has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 22.8% over the last five years.
Final Judgment
These are just a few reasons why we think Vitesse Energy is a high-quality business. With its shares trailing the market in recent months, the stock trades at 79.7× forward P/E (or $18.14 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.