Regional banking company Nicolet Bankshares (NYSE: NIC) met Wall Street’s revenue expectations in Q3 2026, with sales up 68.8% year on year to $174.4 million. Its non-GAAP profit of $3.15 per share was 3.3% above analysts’ consensus estimates.
Is now the time to buy Nicolet Bankshares? Find out by accessing our full research report, it’s free.
Nicolet Bankshares (NIC) Q3 2026 Highlights:
- Net Interest Income: $142.2 million vs analyst estimates of $141.3 million (79.4% year-on-year growth, 0.7% beat)
- Net Interest Margin: 4.2% vs analyst estimates of 4.1% (5 basis point beat)
- Revenue: $174.4 million vs analyst estimates of $173.7 million (68.8% year-on-year growth, in line)
- Efficiency Ratio: 51.7% vs analyst estimates of 49.3% (240 basis point miss)
- Adjusted EPS: $3.15 vs analyst estimates of $3.05 (3.3% beat)
- Tangible Book Value per Share: $61.14 vs analyst estimates of $64.10 (8.6% year-on-year growth, 4.6% miss)
- Market Capitalization: $3.41 billion
“Our third quarter results are beginning to show what this combined company can produce,” said Mike Daniels, Chairman, President, and CEO of Nicolet. “Core earnings increased, our net interest margin expanded again, and we delivered a core return on average tangible common equity of 22%. Our people produced those results all while completing the MidWestOne systems conversion and integration, closing the Denver branch sale, and bringing our teams together around a shared culture. That takes a lot of work. I am proud of how they handled it while continuing to do the thousand little things that matter to our customers and communities every day.”
Company Overview
Starting as Green Bay Financial Corporation in 2000 before rebranding in 2002, Nicolet Bankshares (NYSE: NIC) is a regional bank holding company that provides commercial, agricultural, and consumer banking services primarily in Wisconsin, Michigan, and Minnesota.
Sales Growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income. Thankfully, Nicolet Bankshares’s 23.4% annualized revenue growth over the last five years was incredible. Its growth surpassed the average banking company and shows its offerings resonate with customers, a great starting point for our analysis.
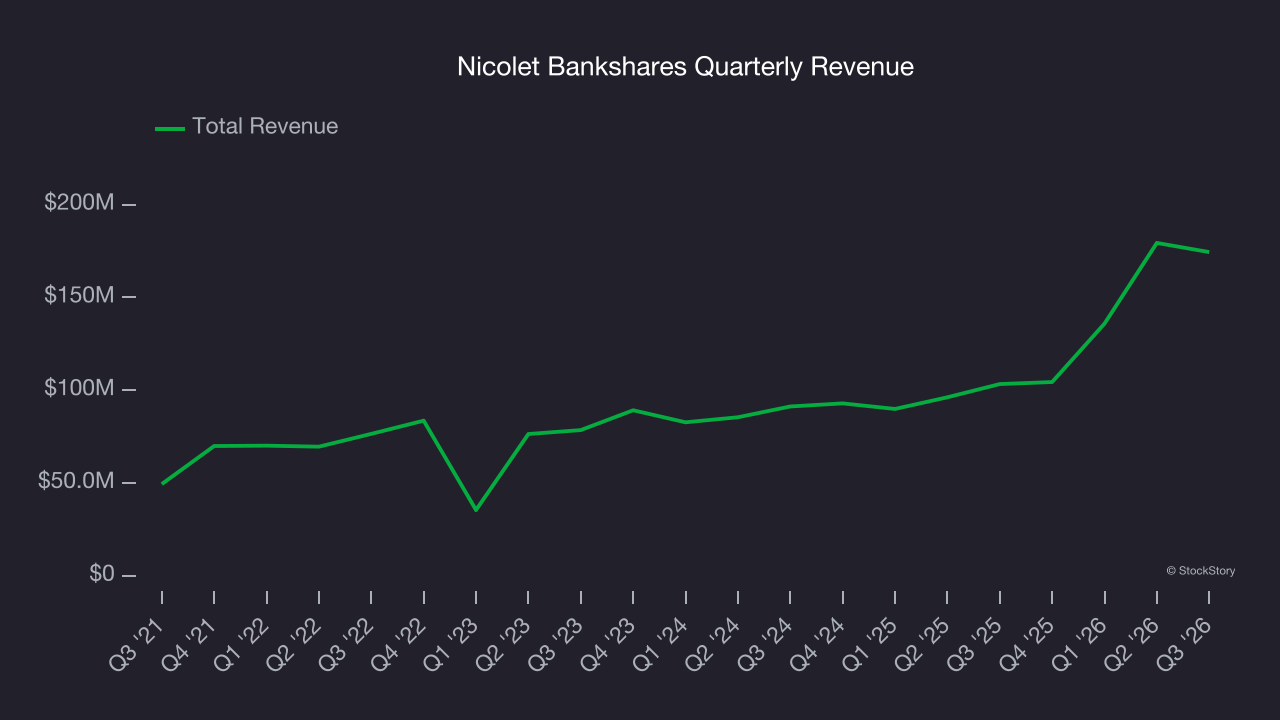
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Nicolet Bankshares’s annualized revenue growth of 30.5% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 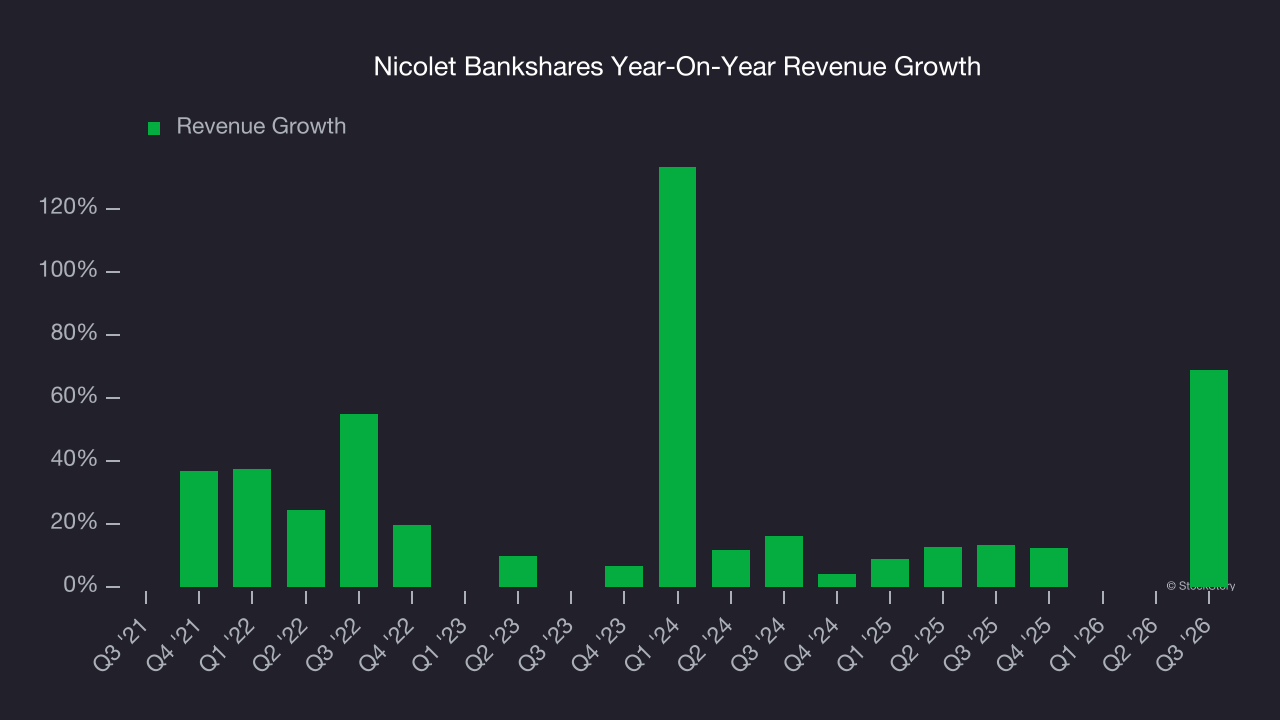 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Nicolet Bankshares’s year-on-year revenue growth of 68.8% was magnificent, and its $174.4 million of revenue was in line with Wall Street’s estimates.
Net interest income made up 84.3% of the company’s total revenue during the last five years, meaning Nicolet Bankshares barely relies on non-interest income to drive its overall growth.
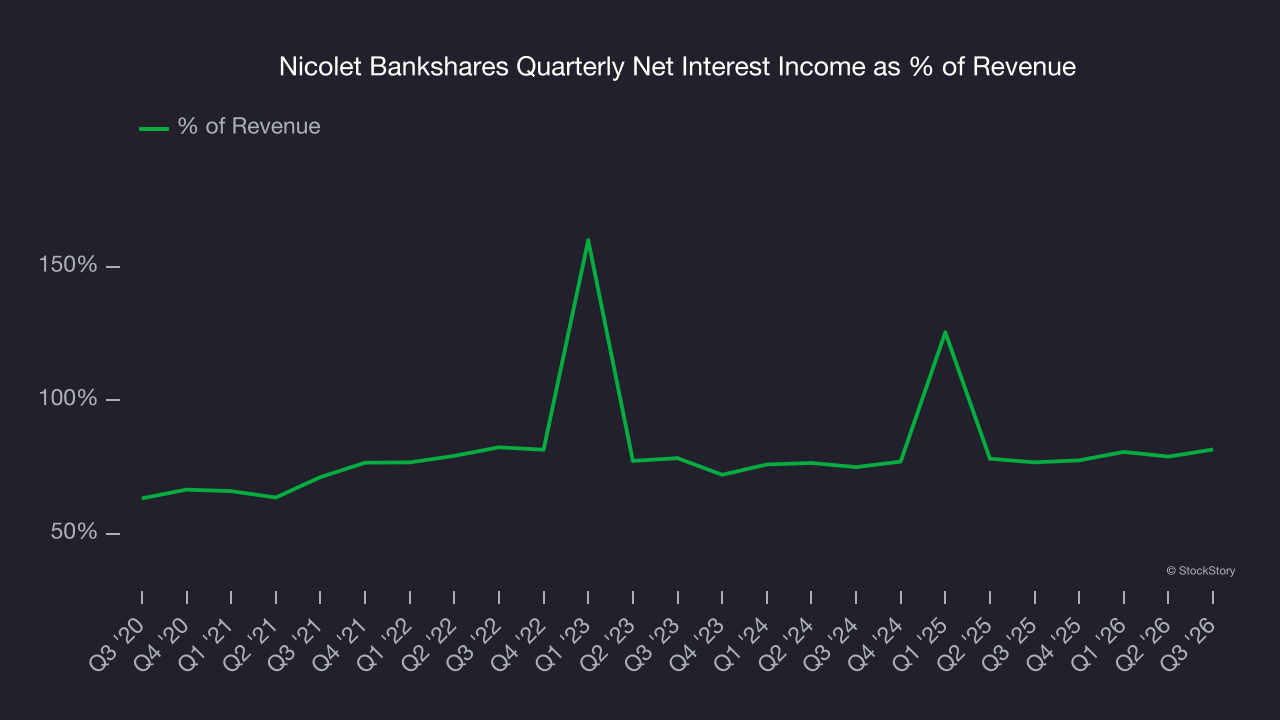
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Tangible Book Value Per Share (TBVPS)
Banks are balance sheet-driven businesses because they generate earnings primarily through borrowing and lending. They’re also valued based on their balance sheet strength and ability to compound book value (another name for shareholders’ equity) over time.
This is why we consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
Nicolet Bankshares’s TBVPS grew at an exceptional 9.7% annual clip over the last five years. The last two years show a similar trajectory as TBVPS grew by 10.3% annually from $50.29 to $61.14 per share.
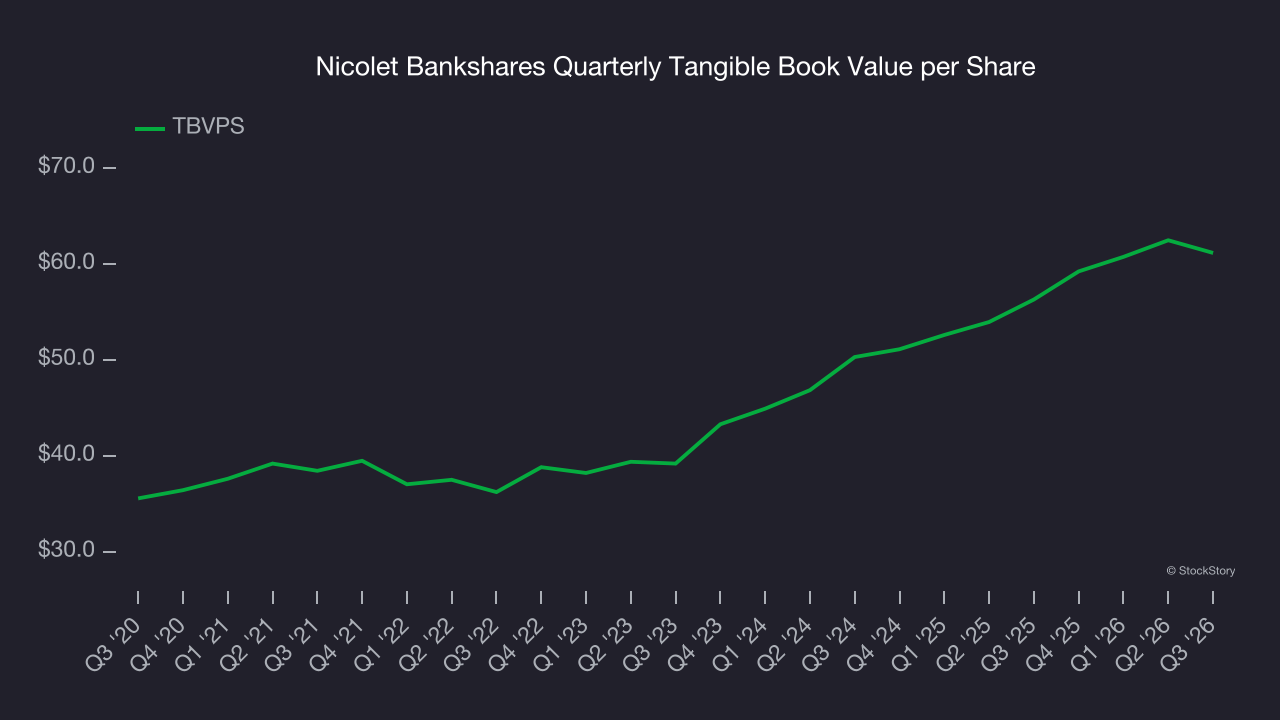
Over the next 12 months, Consensus estimates call for Nicolet Bankshares’s TBVPS to grow by 21% to $74.00, top-notch growth rate.
Key Takeaways from Nicolet Bankshares’s Q3 Results
It was good to see Nicolet Bankshares narrowly top analysts’ net interest income expectations this quarter. On the other hand, its tangible book value per share missed and its EPS slightly exceeded Wall Street’s estimates. Overall, this was a softer quarter. The stock remained flat at $164.71 immediately following the results.
The latest quarter from Nicolet Bankshares’s wasn’t that good. One earnings report doesn’t define a company’s quality, though, so let’s explore whether the stock is a buy at the current price. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).