Streaming video giant Netflix (NASDAQ: NFLX) met Wall Street’s revenue expectations in Q3 2026, with sales up 11.8% year on year to $12.87 billion. On the other hand, next quarter’s revenue guidance of $13.44 billion was less impressive, coming in 0.5% below analysts’ estimates. Its GAAP profit of $0.87 per share was 5.8% above analysts’ consensus estimates.
Is now the time to buy Netflix? Find out by accessing our full research report, it’s free.
Netflix (NFLX) Q3 2026 Highlights:
- Revenue: $12.87 billion vs analyst estimates of $12.87 billion (11.8% year-on-year growth, in line)
- EPS (GAAP): $0.87 vs analyst estimates of $0.82 (5.8% beat)
- Revenue Guidance for Q4 2026 is $13.44 billion, below analyst estimates of $13.51 billion
- EPS (GAAP) guidance for Q4 2026 is $0.67, missing analyst estimates by 7.9%
- Operating Margin: 34.6%, up from 28.2% in the same quarter last year
- Free Cash Flow Margin: 22.4%, up from 12.1% in the previous quarter
- Market Capitalization: $290.9 billion
Company Overview
Launched by Reed Hastings as a DVD mail rental company until its famous pivot to streaming in 2007, Netflix (NASDAQ: NFLX) is a pioneering streaming content platform.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Luckily, Netflix’s sales grew at a solid 15% compounded annual growth rate over the last three years. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers, a great starting point for our analysis.
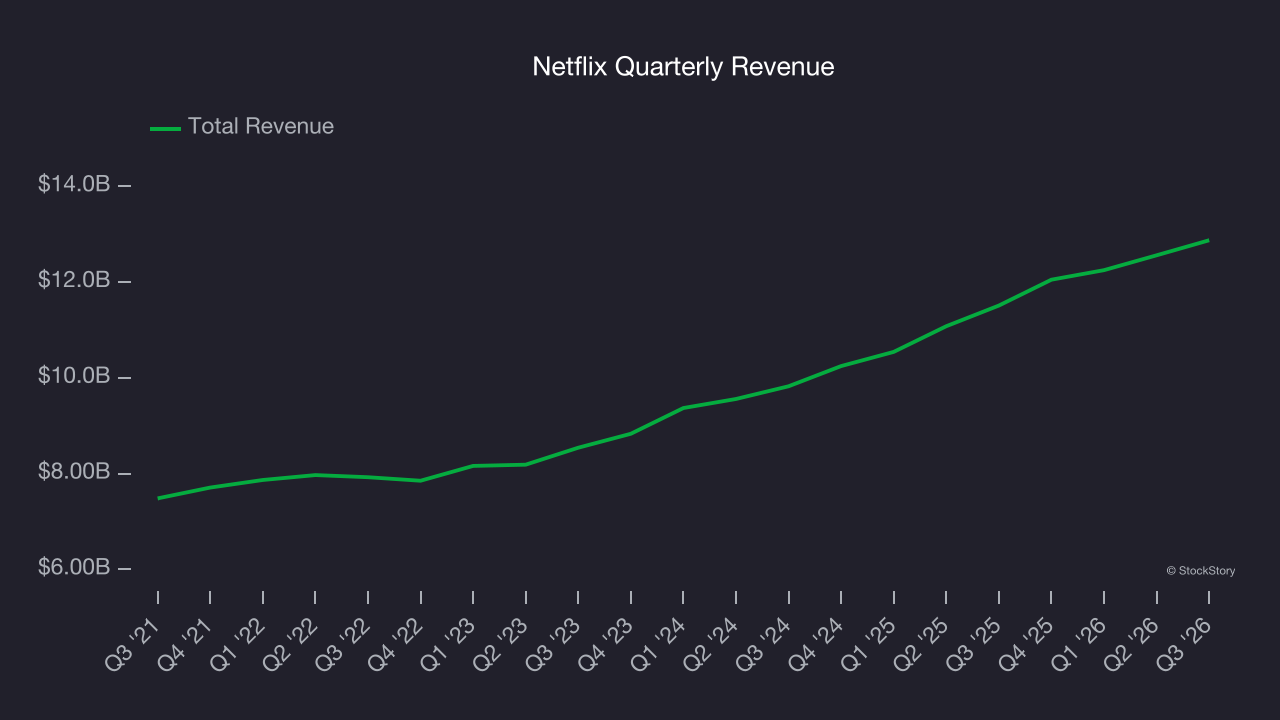
This quarter, Netflix’s year-on-year revenue growth was 11.8%, and its $12.87 billion of revenue was in line with Wall Street’s estimates. Company management is currently guiding for a 11.5% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 11.3% over the next 12 months, a deceleration versus the last three years. We still think its growth trajectory is satisfactory given its scale and suggests the market sees success for its products and services.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Cash Is King
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Netflix has shown terrific cash profitability, driven by its cost-effective customer acquisition strategy that enables it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging 21.8% over the last two years.
Taking a step back, we can see that Netflix’s margin expanded by 5.5 percentage points over the last few years. This is encouraging because it gives the company more optionality.
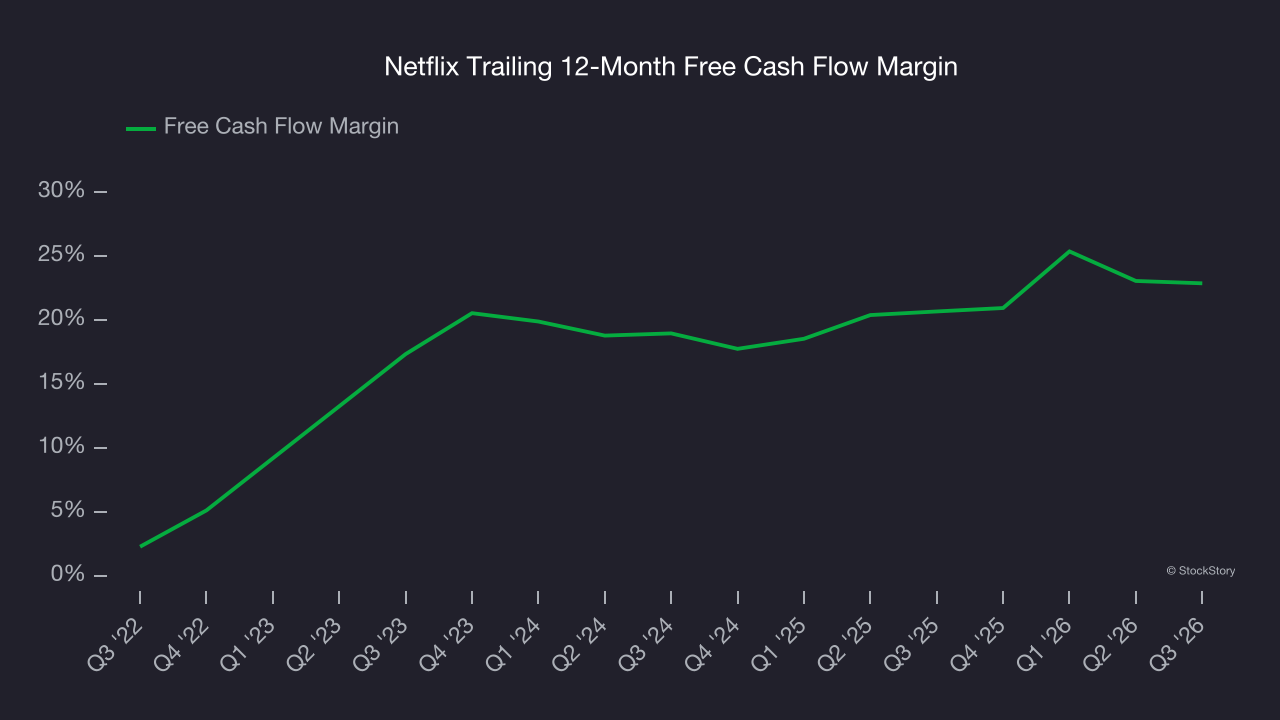
Netflix’s free cash flow clocked in at $2.88 billion in Q3, equivalent to a 22.4% margin. This cash profitability was in line with the comparable period last year and its two-year average.
Key Takeaways from Netflix’s Q3 Results
We struggled to find many positives in these results. Its EPS guidance for next quarter missed and its revenue guidance for next quarter fell slightly short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock traded down 4.3% to $65.79 immediately after reporting.
Netflix’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so let’s explore whether the stock is a buy at the current price. We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).