Global professional services company Accenture (NYSE: ACN) reported calendar Q3 2026 (fiscal Q4 2026) results beating Wall Street’s revenue expectations, with sales up 6.2% year on year to $18.68 billion. Next quarter’s revenue guidance of $19.28 billion was 0.6% below analysts’ estimates. Its GAAP profit of $3.29 per share was 3.4% above analysts’ consensus estimates.
Is now the time to buy Accenture? Find out by accessing our full research report, it’s free.
Accenture (ACN) Q3 CY2026 Highlights:
- Revenue: $18.68 billion vs analyst estimates of $18.04 billion (6.2% year-on-year growth, 3.5% beat)
- EPS (GAAP): $3.29 vs analyst estimates of $3.18 (3.4% beat)
- Revenue Guidance for Q4 CY2026 is $19.28 billion at the midpoint, below analyst estimates of $19.39 billion
- Operating Margin: 15.3%, up from 11.6% in the same quarter last year
- Free Cash Flow Margin: 15.2%, down from 21.6% in the same quarter last year
- Market Capitalization: $112.2 billion
Company Overview
With a workforce of approximately 774,000 people serving clients in more than 120 countries, Accenture (NYSE: ACN) is a professional services firm that helps organizations transform their businesses through consulting, technology, operations, and digital services.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $74.18 billion in revenue over the past 12 months, Accenture is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices.
As you can see below, Accenture’s 8% annualized revenue growth over the last five years was solid. This is an encouraging starting point for our analysis because it shows Accenture’s demand was higher than many business services companies.
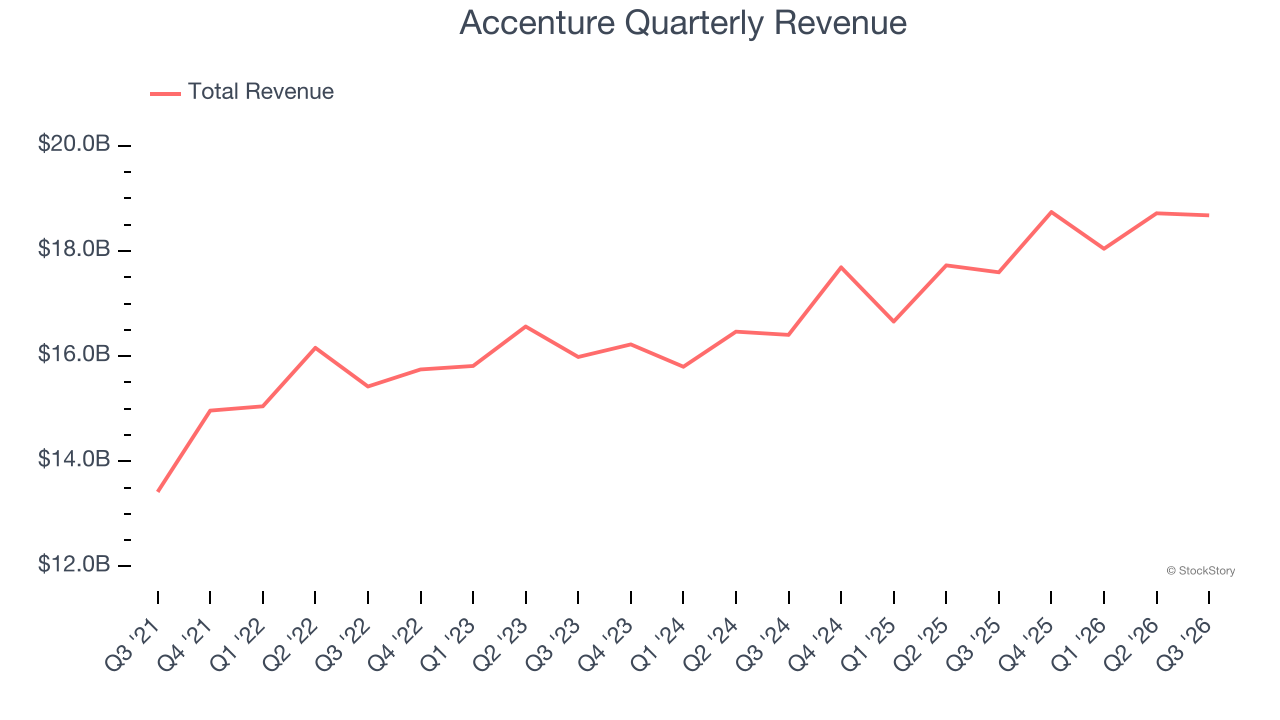
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Accenture’s annualized revenue growth of 6.9% over the last two years is below its five-year trend, but we still think the results were respectable. 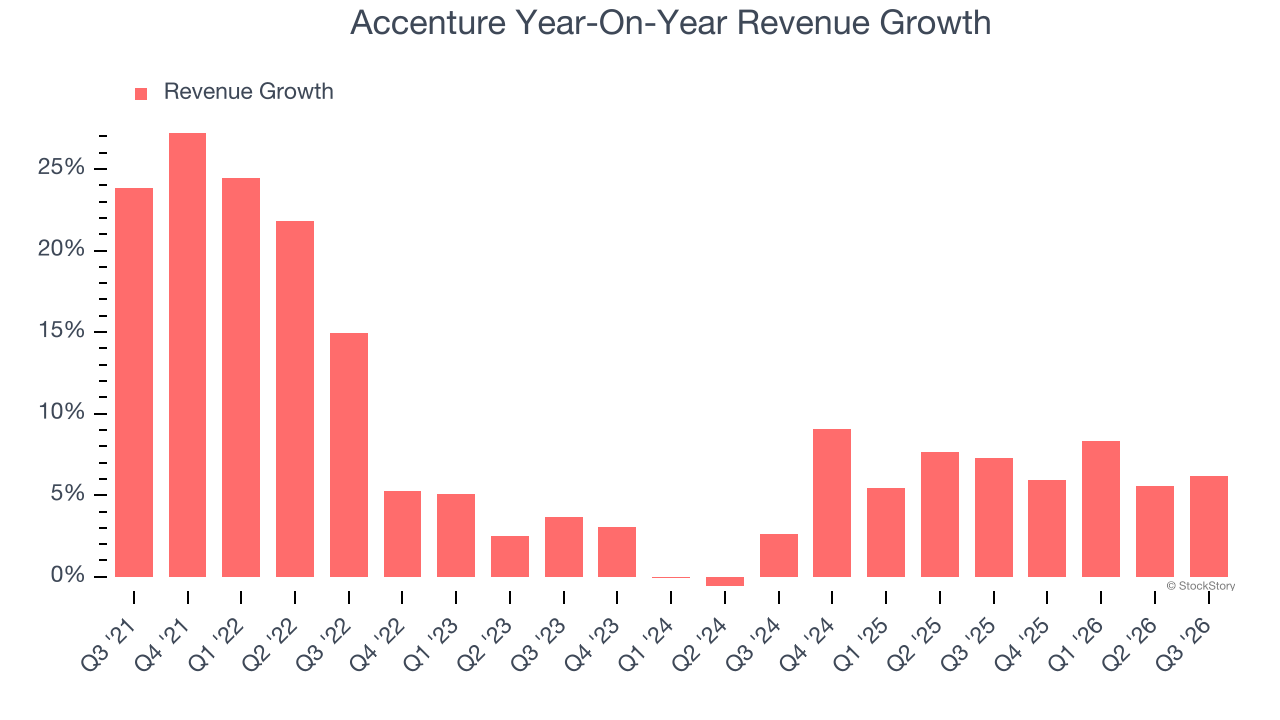
This quarter, Accenture reported year-on-year revenue growth of 6.2%, and its $18.68 billion of revenue exceeded Wall Street’s estimates by 3.5%. Company management is currently guiding for a 2.8% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 2.9% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
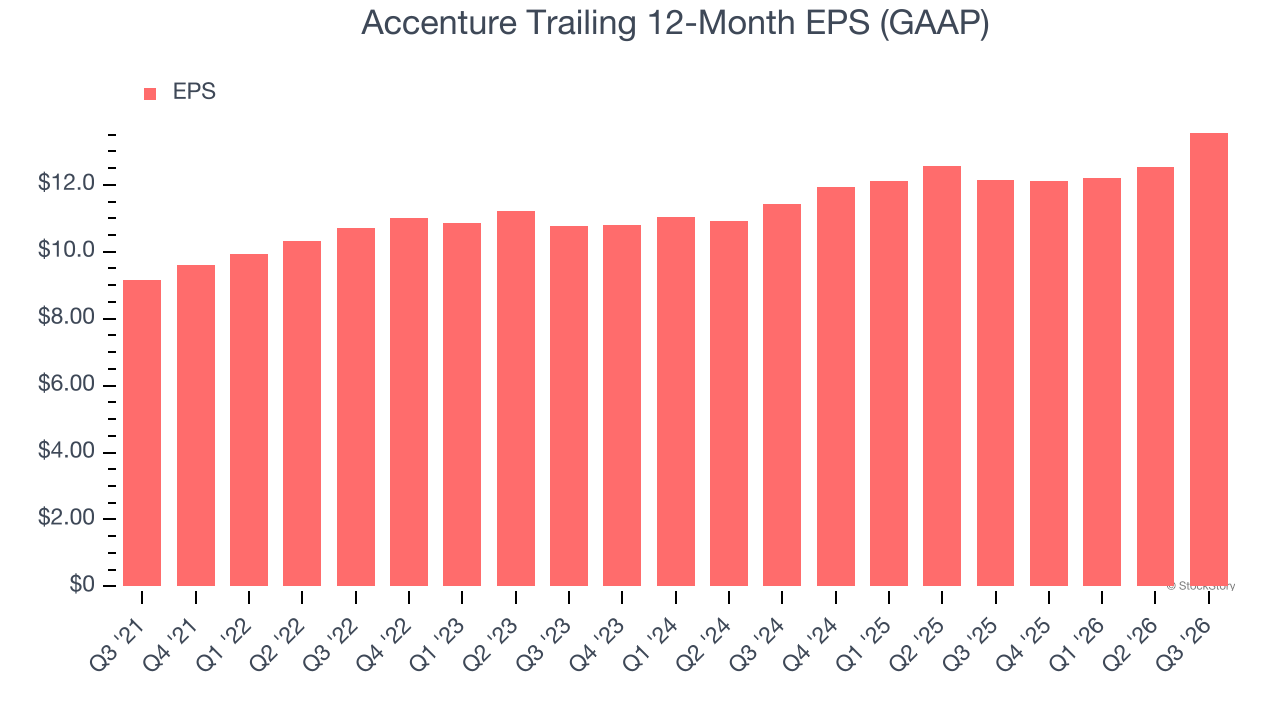
Accenture’s decent 8.2% annual EPS growth over the last five years aligns with its revenue performance. This tells us its incremental sales were profitable.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Although it wasn’t great, Accenture’s two-year annual EPS growth of 8.9% topped its 6.9% two-year revenue growth.
Diving into the nuances of Accenture’s earnings can give us a better understanding of its performance. Accenture’s adjusted operating margin has expanded over the last two yearswhile its share count has shrunk 4.5%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 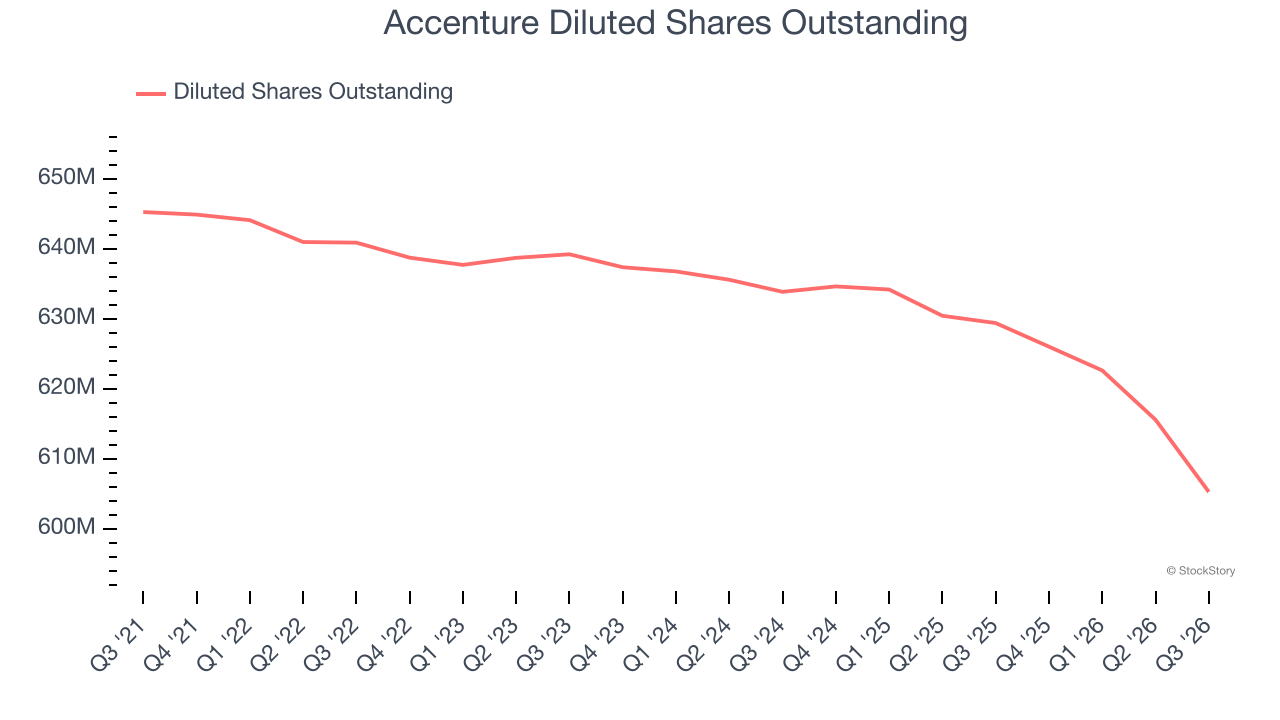
In Q3, Accenture reported EPS of $3.29, up from $2.25 in the same quarter last year. This print beat analysts’ estimates by 3.4%. Over the next 12 months, Wall Street expects Accenture’s full-year EPS to grow 8.3% from $13.56 to $14.68.
Key Takeaways from Accenture’s Q3 Results
We enjoyed seeing Accenture beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 20% to $220.03 immediately after reporting.
So should you invest in Accenture right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).