

Oilfield services provider NESR (NASDAQ: NESR) announced better-than-expected revenue in Q3 2026, with revenue up 70.9% year on year to $504.7 million. Its non-GAAP profit of $0.38 per share was 6.8% above analysts’ consensus estimates.
For more on NESR, read our full research report, available free.
NESR (NESR) Q3 2026 highlights:
- Revenue $504.7 million vs S&P analyst consensus of $494.7 million (70.9% year-on-year growth, 2% beat)
- Adjusted EPS $0.38 vs S&P analyst consensus of $0.36 (6.8% beat)
- Adjusted EBITDA $95.88 million vs analysts’ consensus estimates of $94.5 million (19% margin, 1.5% beat)
- Operating margin 10.4%, up from 6.6% in the same quarter last year
- Free cash flow -$45.93 million compared to -$34.07 million in the same quarter last year
- Market capitalization $2.01 billion
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. NESR’s revenue grew at a solid 15.8% compounded annual growth rate over the last five years. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
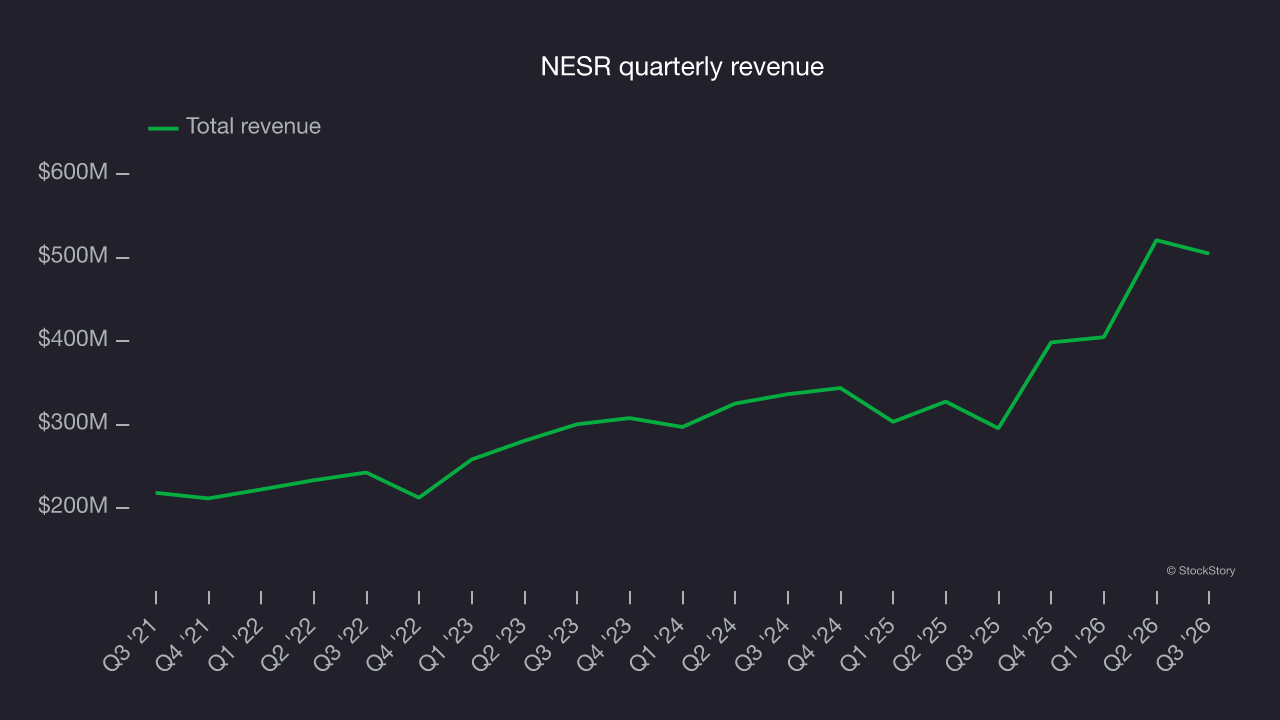
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. NESR’s annualized revenue growth of 20.2% over the last eight years is above its five-year trend.
This quarter, NESR reported strong year-on-year revenue growth of 70.9%, and its $504.7 million in revenue beat Wall Street’s consensus estimates by 2%.
Adjusted EBITDA margin
NESR has managed its cost base reasonably well over the last five years. The company has produced an average EBITDA margin of 35.9%, higher than the broader energy upstream and integrated energy sector.
Looking at the trend in its profitability, NESR’s EBITDA margin decreased by 98.2 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
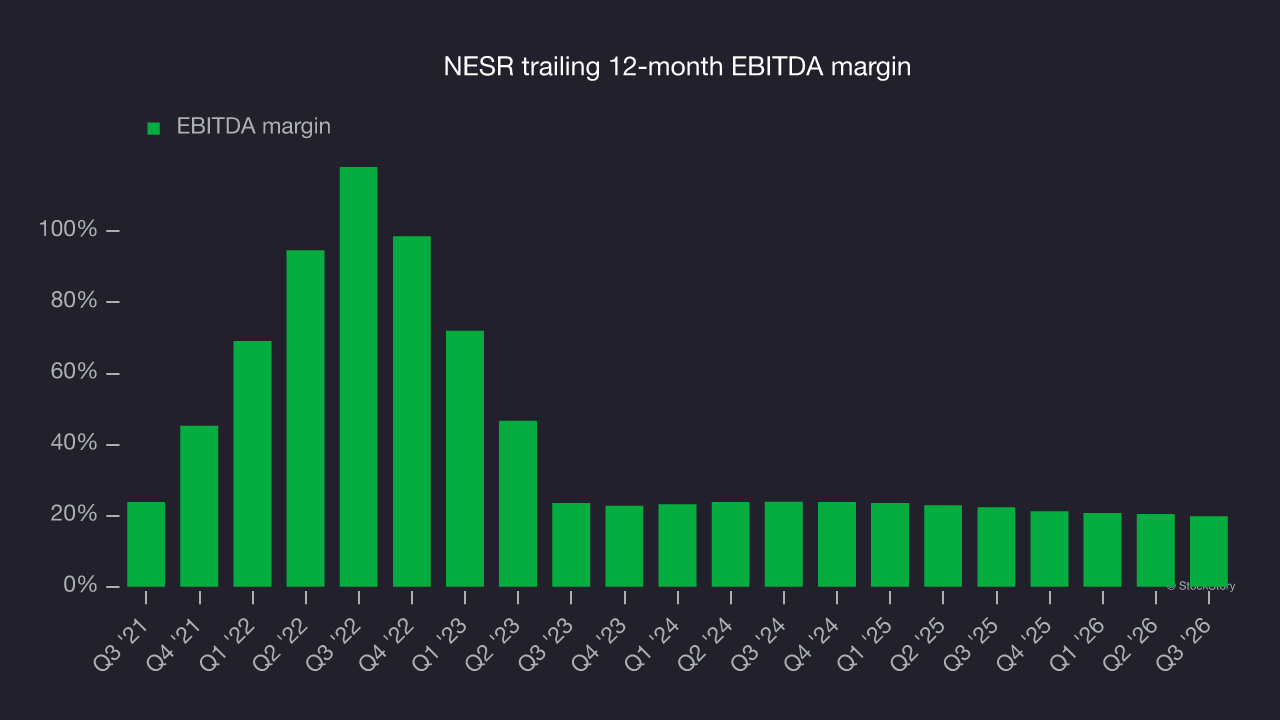
This quarter, NESR generated an EBITDA profit margin of 19%, down 2.7 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA beat Wall Street’s consensus estimates by 1.5%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
NESR has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.5%, below expectations for an upstream and integrated energy business.
Absolute free cash flow margins matter, but so does the stability of free cash flow. All else equal, a steady 25.0% average free cash flow margin regardless of commodity prices is preferable to very high margins in favorable conditions and negative ones in downturns.
NESR’s ratio of quarterly free cash flow volatility to volatility in West Texas Intermediate, or WTI, crude prices over the past five years was 27.7 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why compare free cash flow rather than revenue or EBITDA with WTI crude prices for NESR? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
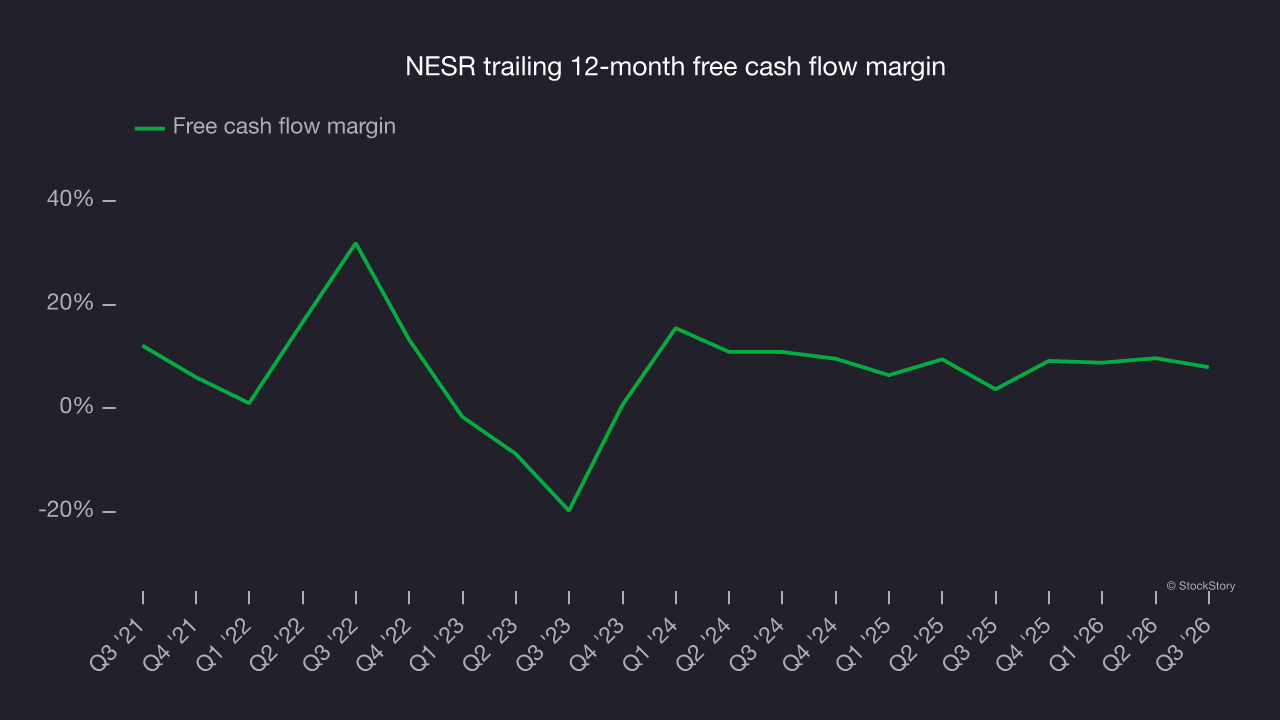
NESR used $45.93 million of cash in Q3, equivalent to a negative 9.1% margin. The company’s cash burn was similar to its $34.07 million cash burn in the same quarter last year. These numbers deviate from its longer-term margin, indicating it is a seasonal business that must build up inventory during certain quarters.
Key takeaways from NESR’s Q3 results
NESR’s revenue and EPS both topped Wall Street’s consensus estimates, giving the quarter some clear positives. Shares remained flat at $19.83 immediately after the release.
The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in this stock. For more on NESR, read our full research report here (it’s free).




