Online new and used car marketplace Cars.com (NYSE: CARS) fell short of the market’s revenue expectations in Q3 2026, with revenue flat year on year at $181.9 million. Its non-GAAP profit of $0.58 per share was 8.1% above analysts’ consensus estimates.
For more on Cars.com, read our free full research report.
Cars.com (CARS) Q3 2026 highlights:
- Revenue $181.9 million vs S&P analysts’ consensus estimates of $183.4 million (flat year on year, 0.8% miss)
- Adjusted EPS $0.58 vs S&P analysts’ consensus estimates of $0.54 (8.1% beat)
- Adjusted EBITDA $55.82 million vs analysts’ consensus estimates of $53.43 million (30.7% margin, 4.5% beat)
- Operating margin 15.9%, up from 9.3% in the same quarter last year
- Free cash flow margin 29.6%, up from 5.5% in the previous quarter
- Dealer customers 19,251, down 275 year on year
- Market capitalization $682.5 million
"Our third quarter results reinforced the growing strength of our core, scaled Marketplace. We once again grew Marketplace customers, reached another milestone in Premium+ package adoption, and also launched our first ever self-service subscription designed to meet the needs of local independent dealers. These outcomes flow directly from fundamental improvements to our operating model throughout 2026 that span our focus areas of product innovation, process efficiency, and organizational talent. Though still early, these steps point in the right direction. We are moving swiftly to extend that momentum across the rest of our portfolio as we build the foundation for product-led growth and long-term value creation," said Tobias Hartmann, Chief Executive Officer of Cars.com, Inc.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can post a good quarter or two, but the best consistently grow over the long haul. Over the last three years, Cars.com grew its revenue at a sluggish 2.3% compounded annual growth rate, falling short of our benchmarks.
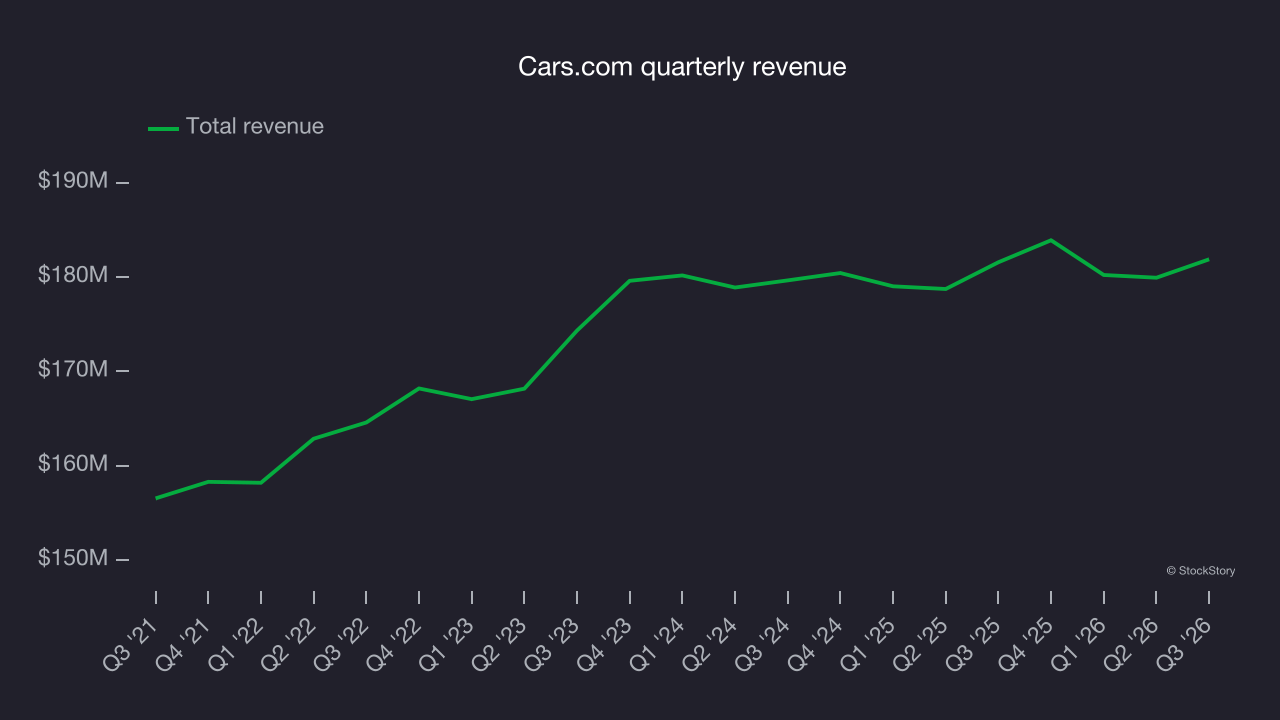
This quarter, Cars.com’s $181.9 million of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 1.8% over the next 12 months, according to S&P, similar to its three-year rate. This projection is underwhelming and implies its newer products and services will not accelerate its top-line performance yet.
Dealer customers
Buyer growth
As an online marketplace, Cars.com generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Cars.com struggled with new customer acquisition over the last two years as its dealer customers were flat at 19,251. This performance isn’t ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Cars.com wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 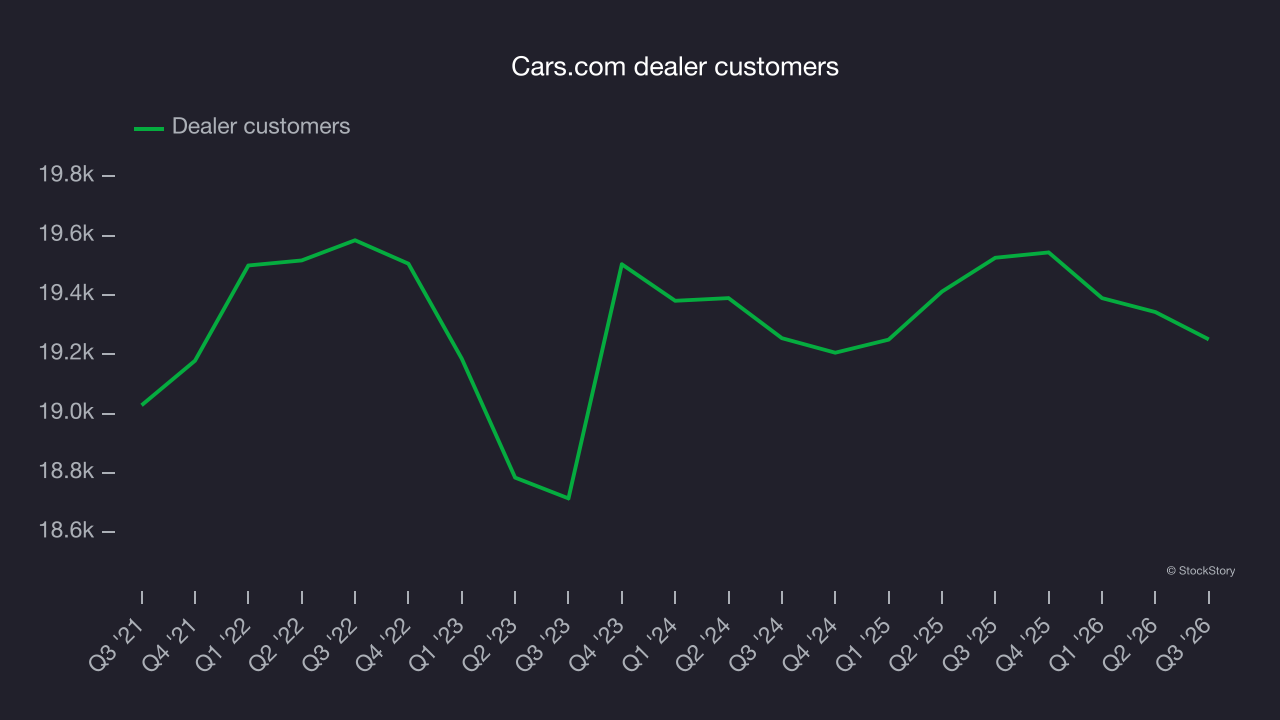
In Q3, Cars.com’s dealer customers decreased by 275, a 1.4% drop since last year. The quarterly result was weaker than its two-year performance, suggesting its new initiatives aren’t yet gaining traction with buyers.
Revenue per buyer
Average revenue per buyer, or ARPB, is a critical metric to track because it measures how much the company earns in transaction fees from each buyer. ARPB also provides insight into a user’s average order size and Cars.com’s take rate, or “cut”, on each order.
Cars.com’s ARPB has been roughly flat over the last two years. This raises questions about its platform’s health when paired with its inability to grow dealer customers. If Cars.com wants to increase its buyers, it must either develop new features or provide some existing ones for free. 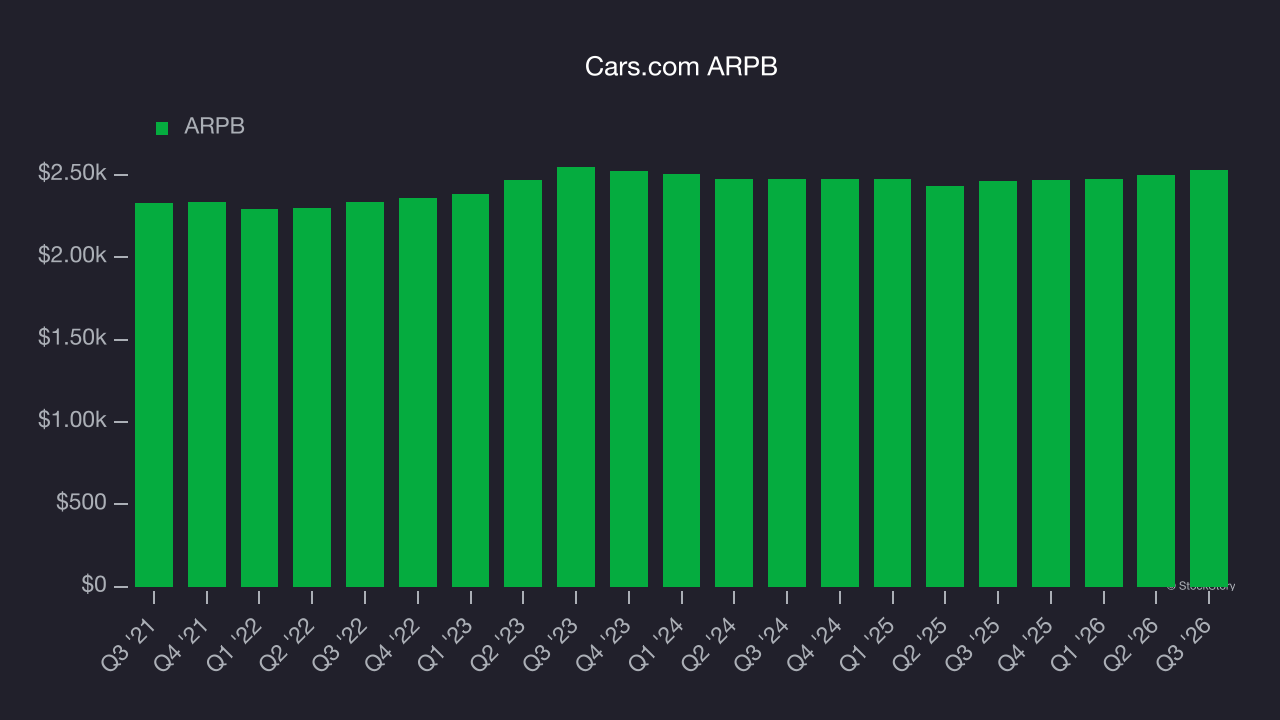
This quarter, Cars.com’s ARPB was $2,532. It grew by 2.9% year on year, faster than its dealer customers.
Key takeaways from Cars.com’s Q3 results
Cars.com’s EBITDA beat analysts’ consensus estimates, but a slight revenue miss and a decline in buyers left room for a better quarter overall. Shares remained flat at $12.69 immediately after the results.
Cars.com had a tough quarter. When deciding whether to invest at the current price, it’s important to consider its valuation, business quality and latest quarterly results. For more on those factors, read the full research report here (it’s free).