Fast-food company Yum China (NYSE: YUMC) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 8.5% year on year to $3.48 billion. Its non-GAAP profit of $0.91 per share was 1.3% above analysts’ consensus estimates.
For more on Yum China, read our free full research report.
Yum China (YUMC) Q3 2026 highlights:
- Revenue $3.48 billion vs S&P analysts’ consensus estimates of $3.50 billion (8.5% year-on-year growth, 0.5% miss)
- Adjusted EPS $0.91 vs S&P analysts’ consensus estimates of $0.90 (1.3% beat)
- Adjusted EBITDA $578 million vs analysts’ consensus estimates of $552 million (16.6% margin, 4.7% beat)
- Operating margin 13%, in line with the same quarter last year
- Free cash flow margin 10.3%, similar to the same quarter last year
- Locations 19,989 at quarter end, up from 17,514 in the same quarter last year
- Same-store sales fell 3% year on year (1% in the same quarter last year)
- Market capitalization $16.03 billion
Joey Wat, CEO of Yum China, commented, "We delivered year-over-year growth in system sales, operating profit and OP margin for the 10th consecutive quarter, despite a dynamic operating environment. Importantly, our diluted EPS has grown by double digits year-to-date and in each of the past three years, excluding the impact of mark-to-market equity investments and foreign exchange. These results demonstrate the resilience of our business model, disciplined execution, and our commitment to delivering sustainable value to shareholders. Same-store sales faced pressure from tough comparisons against last year's delivery platform subsidies and adverse weather in August. We captured incremental demand across a broader range of consumption occasions such as smaller orders and solo dining, and grew same-store transactions for the 15th consecutive quarter. To pursue significant opportunities in China, we accelerated store openings across Company-owned and franchise stores, leveraging our tailored store formats and menus and keeping us on track to surpass 20,500 stores this year."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can post a good quarter or two, but many enduring ones grow for years.
With $12.71 billion in revenue over the past 12 months, Yum China is one of the most widely recognized restaurant chains and benefits from customer loyalty, an advantage many competitors lack. Its scale also gives it negotiating leverage with suppliers, enabling it to source its ingredients at a lower cost. However, its scale is a double-edged sword because there is only so much real estate to build restaurants, placing a ceiling on its growth. To expand meaningfully, Yum China likely needs to adjust its prices, start new chains or enter new markets.
Yum China’s revenue grew at a tepid 5.6% compounded annual growth rate over the last seven years.
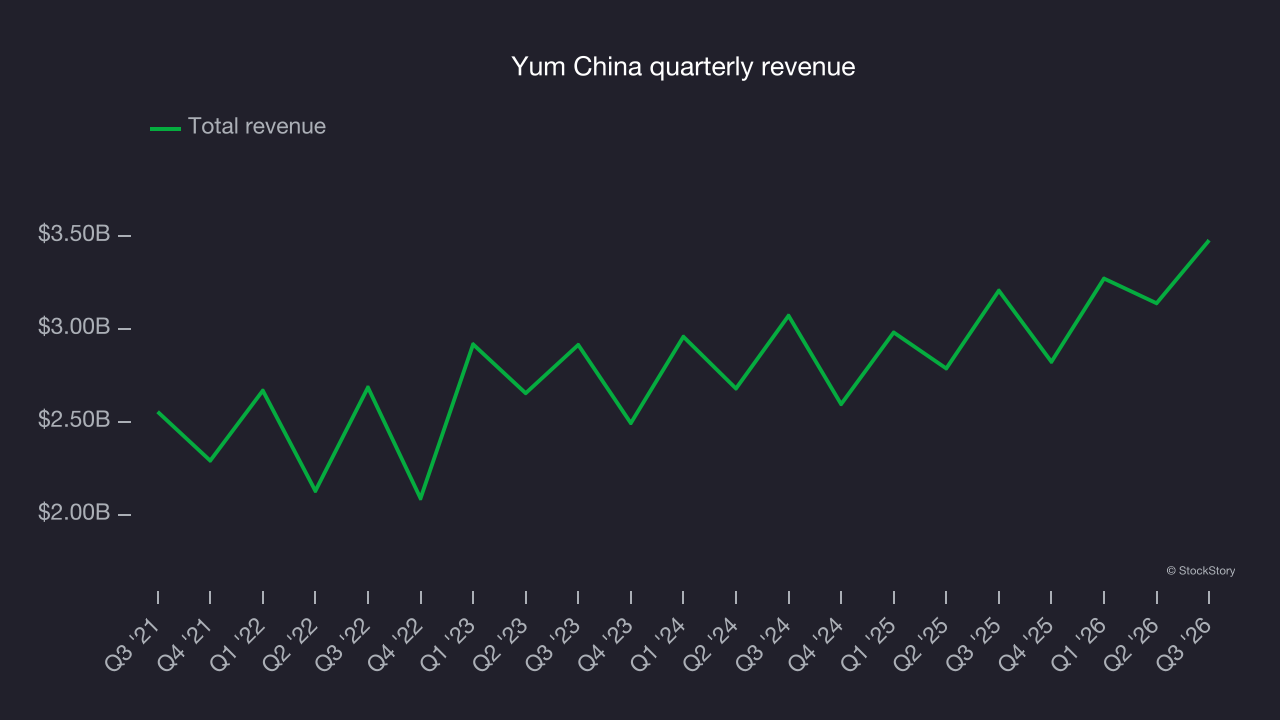
This quarter, Yum China’s revenue grew by 8.5% year on year to $3.48 billion, missing Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.9% over the next 12 months, according to S&P, similar to its seven-year rate. While this projection suggests its newer menu offerings will spur better top-line performance, it is still below average for the sector.
Restaurant performance
Number of restaurants
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
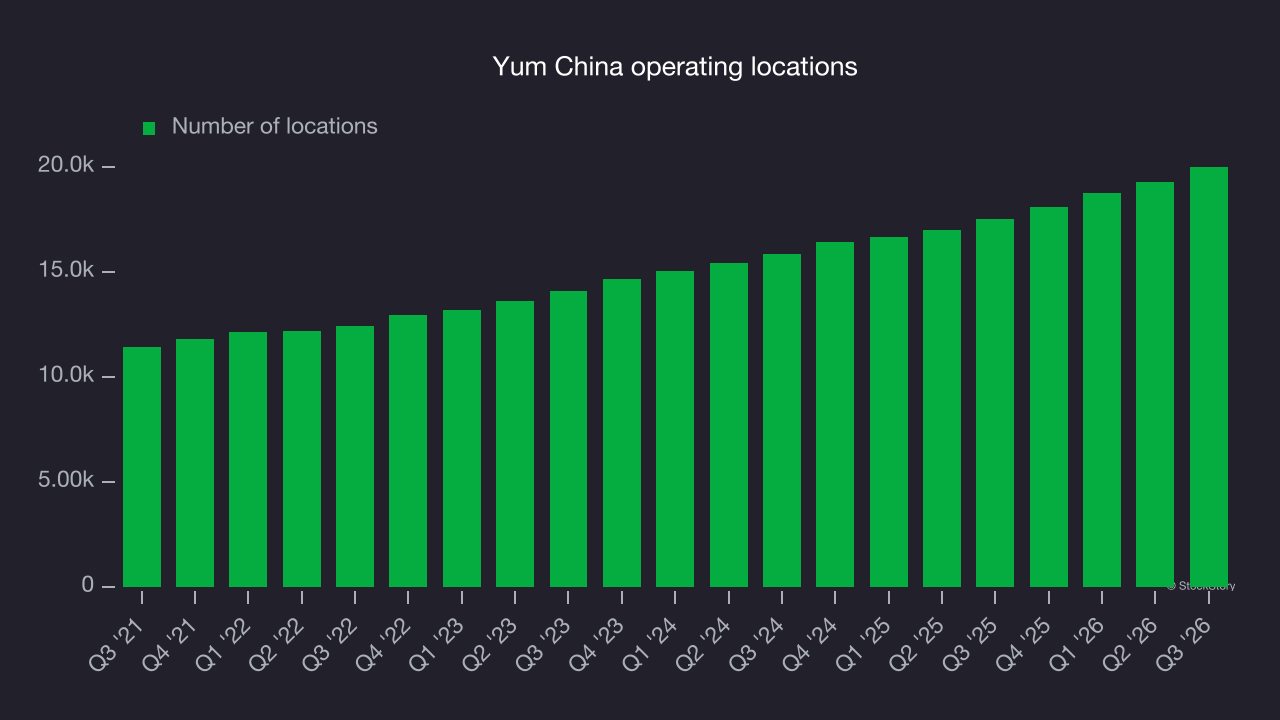
Yum China had 19,989 locations in the latest quarter. Over the last two years, its restaurant count has grown at a rapid pace, averaging 11.8% annual growth, among the fastest in the restaurant sector.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-store sales
The change in a company’s restaurant base only tells one side of the story. The other is the performance of its existing locations, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales is an industry measure of whether revenue is growing at those existing restaurants and is driven by customer visits (often called traffic) and the average spending per customer (ticket).
Yum China’s demand within its existing dining locations has barely increased over the last two years as its same-store sales were flat. Yum China should consider improving its foot traffic and efficiency before expanding its restaurant base.
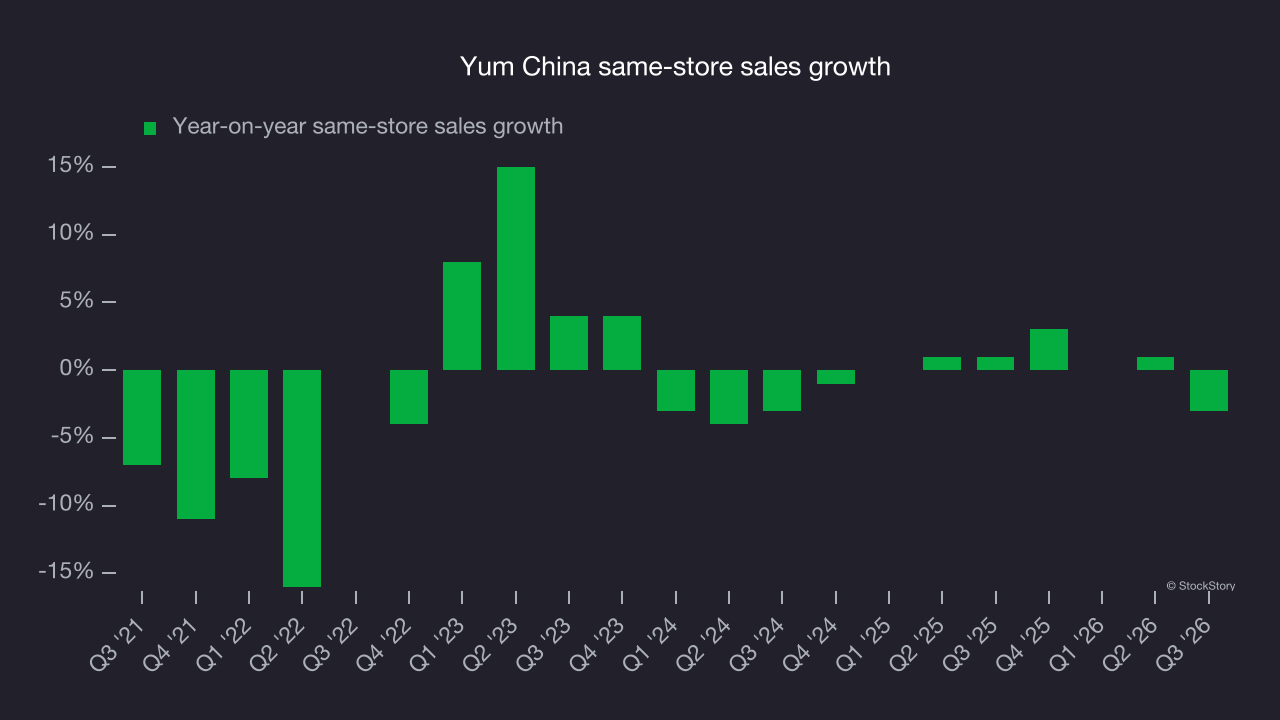
In the latest quarter, Yum China’s same-store sales fell by 3% year on year. This decline was a reversal from its historical levels.
Key takeaways from Yum China’s Q3 results
Yum China’s quarter could have been better despite beating analysts’ consensus estimates for EBITDA. Same-store sales missed expectations, and revenue came in slightly below Wall Street’s consensus. Shares remained flat at $47.09 immediately after the results.
The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read more in our full research report here (it’s free).