Affordable single-family home construction company LGI Homes (NASDAQ: LGIH) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 12.1% year on year to $444.5 million. Its non-GAAP profit of $1.05 per share was 45.8% above analysts’ consensus estimates.
For more on LGI Homes, read our free full research report.
LGI Homes (LGIH) Q3 2026 highlights:
- Revenue $444.5 million vs S&P analysts’ consensus estimates of $433.3 million (12.1% year-on-year growth, 2.6% beat)
- Adjusted EPS $1.05 vs S&P analysts’ consensus estimates of $0.72 (45.8% beat)
- Operating margin 6.1%, in line with the same quarter last year
- Backlog $273.7 million at quarter end, down 45.1% year on year
- Market capitalization $1.10 billion
“Based on our year-to-date results and current market conditions, we are narrowing our full-year closings guidance and now expect to close between 4,600 and 4,800 homes in 2026. The revised outlook reflects slower sales activity in the quarter as affordability pressures continued to weigh on demand. We continue to see interest in homeownership and are leaning into our proven sales and marketing strategies to improve sales pace while maintaining our disciplined approach to balancing affordability and profitability. We are maintaining the remainder of our full-year 2026 guidance.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can post a good quarter or two, but many enduring ones grow for years. LGI Homes struggled to consistently generate demand over the last five years as its revenue dropped at an 11.2% annual rate. That underwhelming result suggests it is a low-quality business.
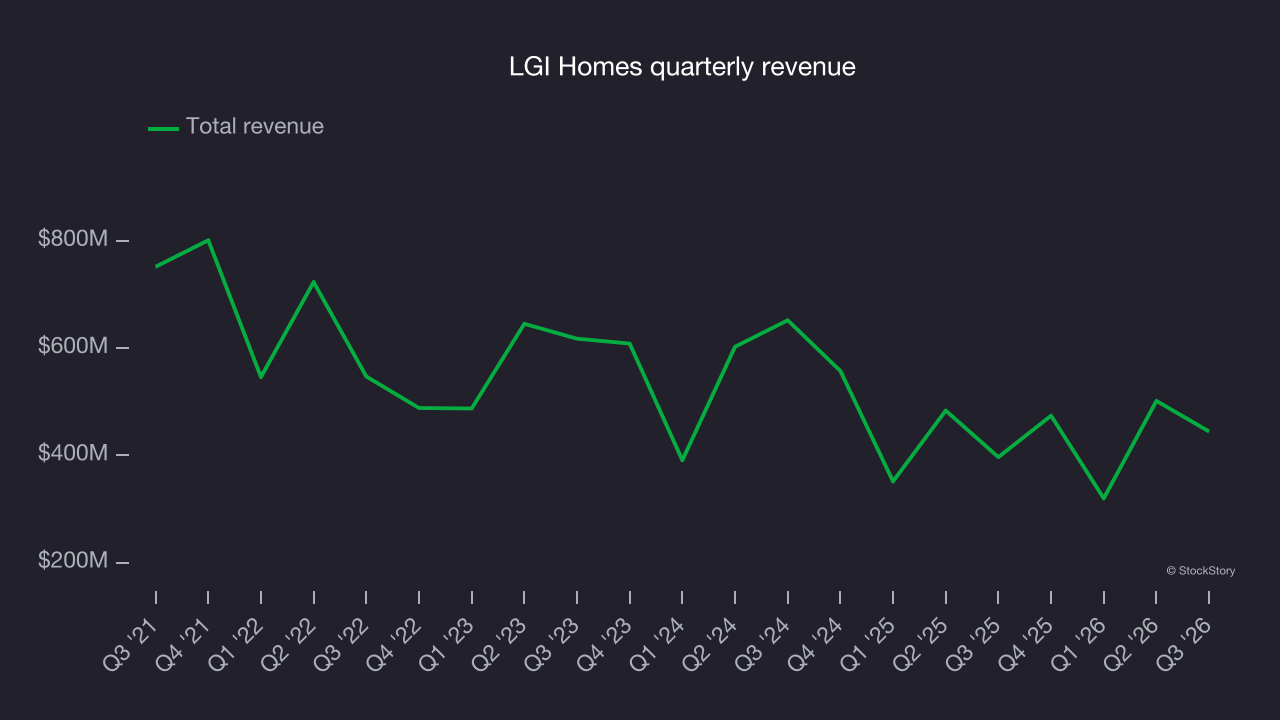
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. LGI Homes’s annualized revenue declines of 12.1% over the last two years align with its five-year trend, suggesting its demand has consistently shrunk. LGI Homes isn’t alone in its struggles as the home builders industry experienced a cyclical downturn, with many similar businesses reporting lower revenue during this period. 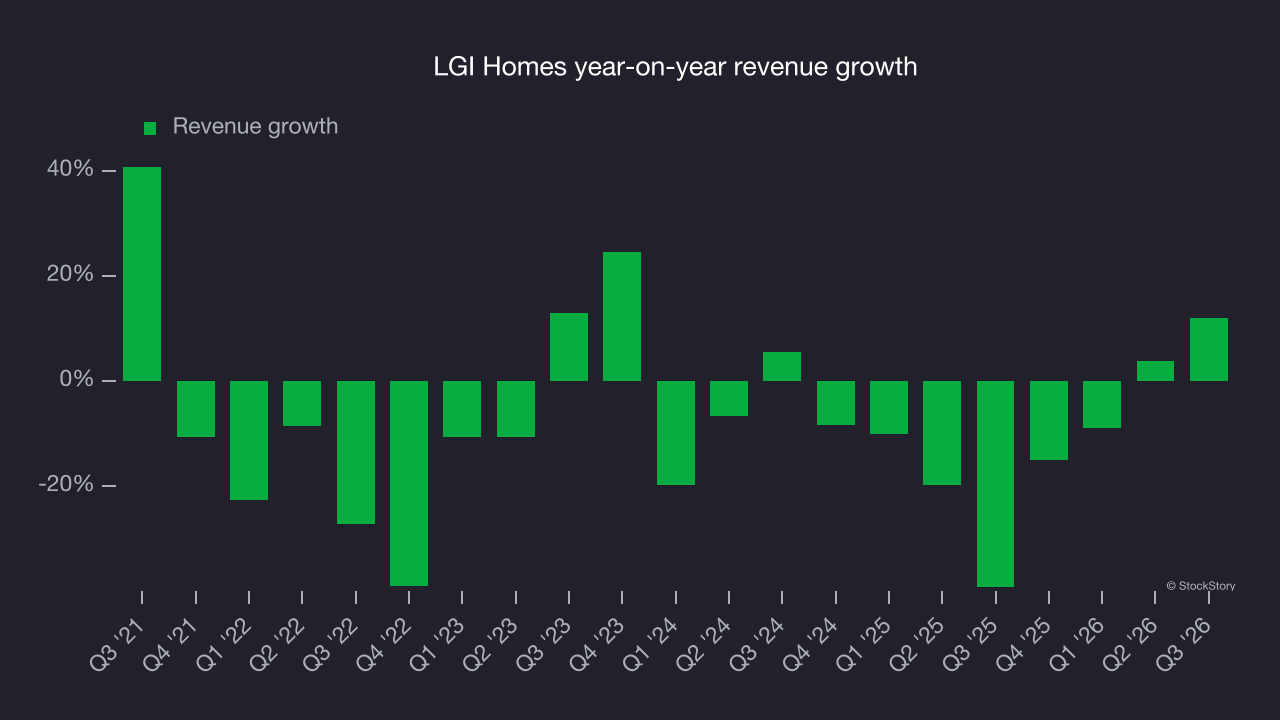
LGI Homes also reports its backlog, or the value of its outstanding orders that have not yet been executed or delivered. LGI Homes’s backlog reached $273.7 million in the latest quarter and averaged 12.9% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for LGI Homes’s products and services but raises concerns about capacity constraints. 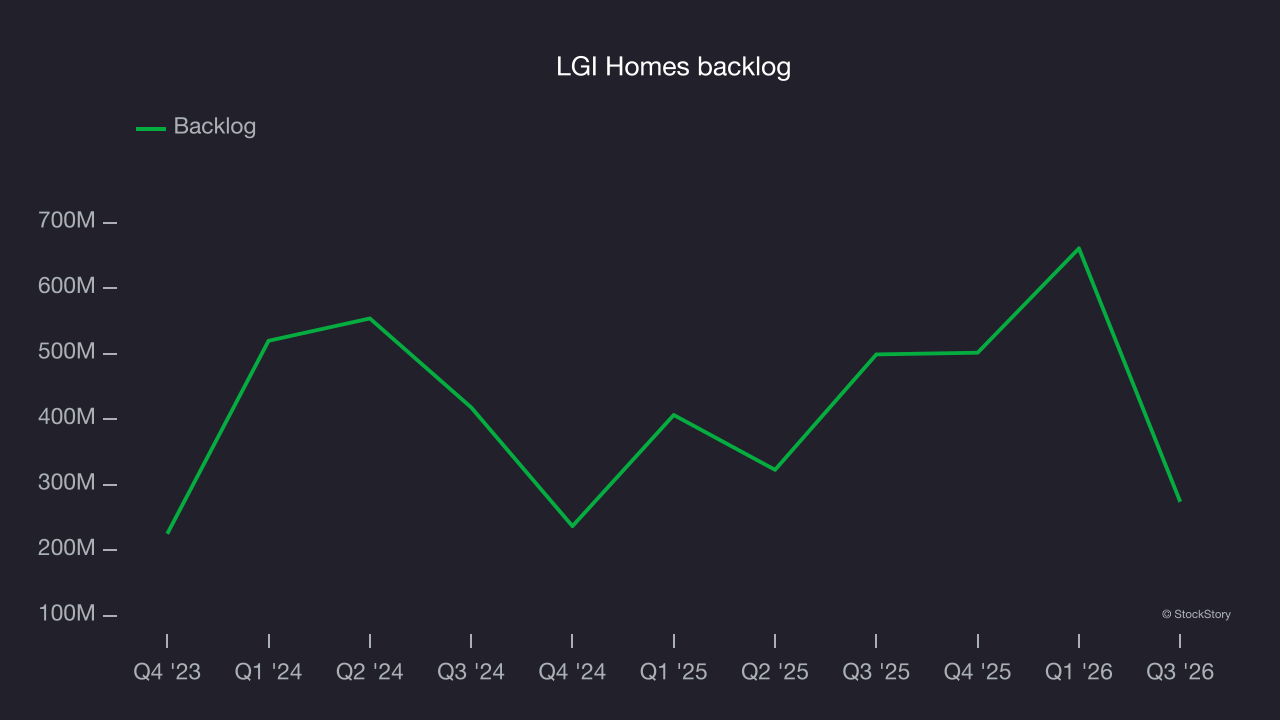
This quarter, LGI Homes reported year-on-year revenue growth of 12.1%, and its $444.5 million of revenue exceeded Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to grow 12.2% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is noteworthy and indicates its newer products and services will drive better revenue performance.
Operating margin
LGI Homes has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 10.5%. This result was particularly impressive given its low gross margin, which largely reflects what it sells and requires substantial changes to improve meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Looking at the trend in its profitability, LGI Homes’s operating margin decreased by 14.4 percentage points over the last five years. Many home builders also saw their margins fall (along with revenue, as mentioned above) because the cycle weakened. The downturn offers LGI Homes an opportunity to emerge as a stronger company by gaining market share and improving efficiency.
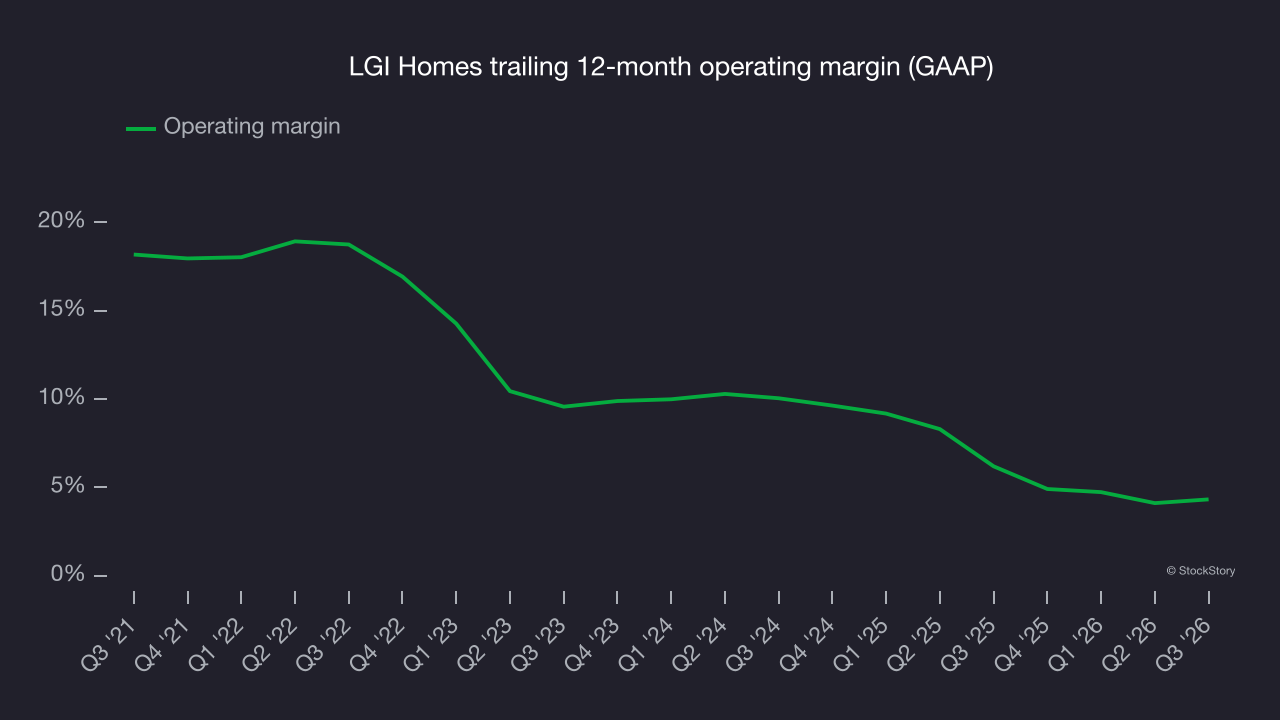
In Q3, LGI Homes generated an operating margin of 6.1%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
LGI Homes’s EPS declined by 28.2% annually over the last five years, more than its revenue. The company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
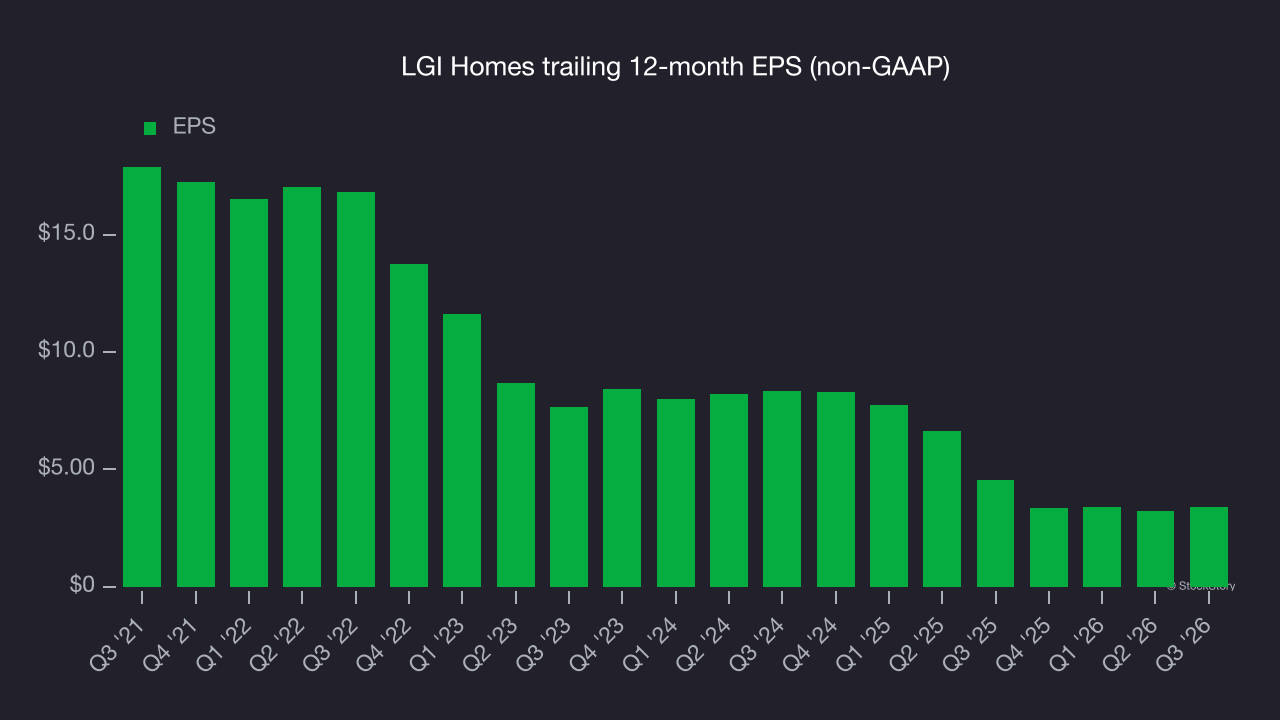
We can take a deeper look into LGI Homes’s earnings to better understand the drivers of its performance. As we mentioned earlier, LGI Homes’s operating margin was flat this quarter but declined by 14.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For LGI Homes, its two-year annual EPS declines of 36% show it’s continued to underperform. These results were poor by any measure.
In Q3, LGI Homes reported adjusted EPS of $1.05, up from $0.85 in the same quarter last year. This result comfortably beat analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects LGI Homes’s full-year EPS to shrink by 9.6% from $3.42 to $3.09, according to S&P.
Key takeaways from LGI Homes’s Q3 results
LGI Homes delivered a solid quarter, topping analysts’ consensus estimates for both EPS and revenue. Those beats were key positives in the results. Shares rose 4.5% to $49.58 immediately after the report.
LGI Homes reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. An investment decision should consider the broader picture, including its valuation, business quality and latest earnings. For more on LGI Homes, read the free full research report here.