Healthcare diagnostics company Labcorp Holdings (NYSE: LH) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 6.9% year on year to $3.81 billion. The company’s full-year revenue guidance of $14.83 billion at the midpoint came in 0.6% above analysts’ consensus estimates. Its non-GAAP profit of $4.78 per share was 2.9% above analysts’ consensus estimates.
For more on Labcorp, read our free full research report.
Labcorp (LH) Q3 2026 highlights:
- Revenue $3.81 billion vs S&P analysts’ consensus estimates of $3.76 billion (6.9% year-on-year growth, 1.2% beat)
- Adjusted EPS $4.78 vs S&P analysts’ consensus estimates of $4.64 (2.9% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $14.83 billion at the midpoint from $14.77 billion
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $18.50 at the midpoint
- Operating margin 10.6%, in line with the same quarter last year
- Free cash flow margin 10.8%, up from 7.9% in the same quarter last year
- Organic revenue rose 5.5% year on year (beat)
- Market capitalization $26.86 billion
"Labcorp delivered another strong quarter with 7% revenue growth, continued margin expansion and 14.5% adjusted EPS growth, leading to a raise in our full-year guidance," said Adam Schechter, Chairman and CEO of Labcorp. "We furthered our leadership in specialty testing by launching innovative tests for advanced melanoma, Alzheimer's disease, and hepatitis D, while expanding access through strategic acquisitions across our Diagnostics and Biopharma Laboratory Services businesses. As healthcare continues to be transformed by advances in science and technology, personalized medicine, and evolving consumer expectations, Labcorp is well positioned to capitalize on these trends and drive sustainable long-term growth."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Labcorp’s demand was weak over the last five years as its revenue fell at a 2.5% annual rate. This was below our standards and suggests it’s a lower-quality business.
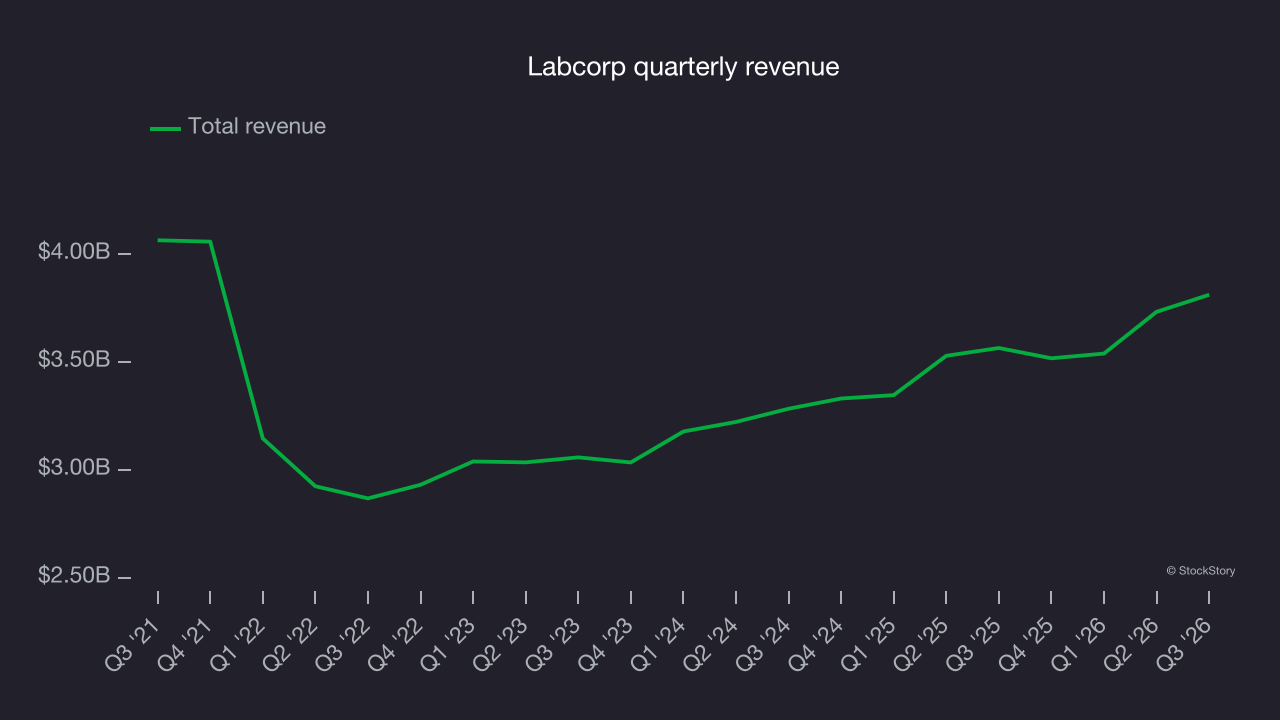
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Labcorp’s annualized revenue growth of 7.1% over the last two years is above its five-year trend, a positive sign. 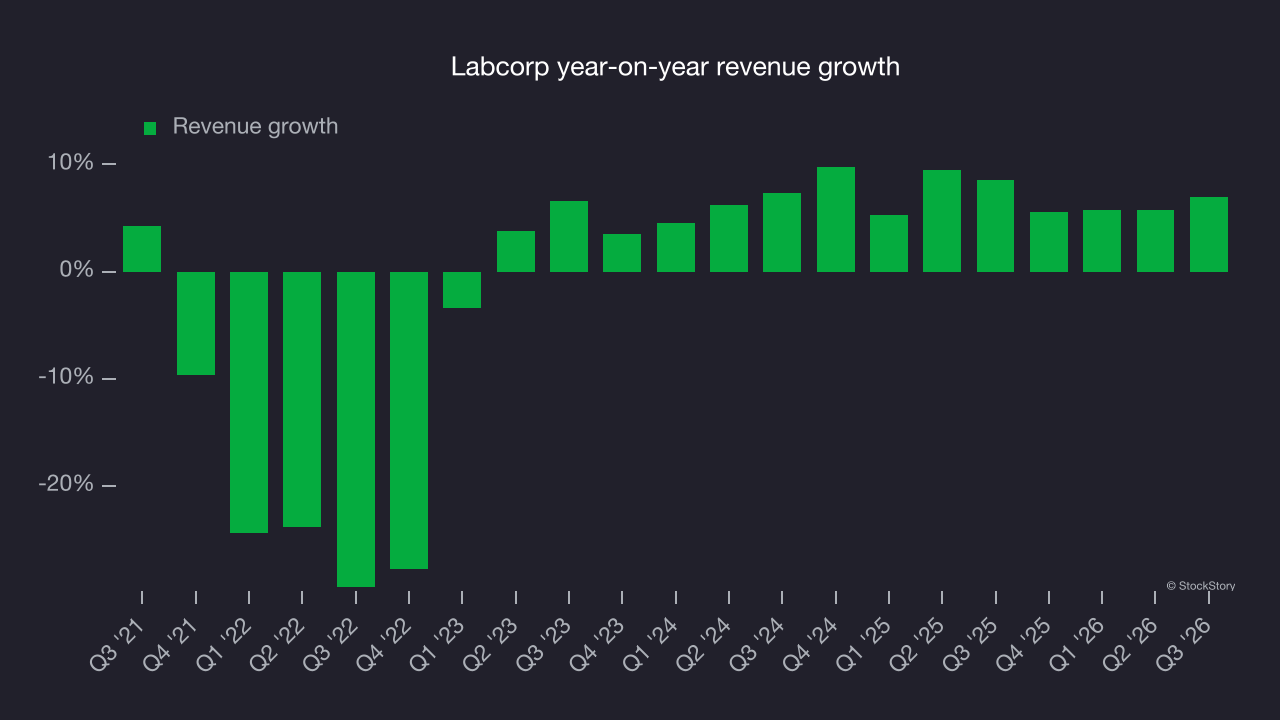
Labcorp also reports organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Labcorp’s organic revenue averaged 4.5% year-on-year growth. Total revenue growth outpaced organic growth over that period, indicating that a combination of acquisitions and foreign exchange rates boosted its headline results. 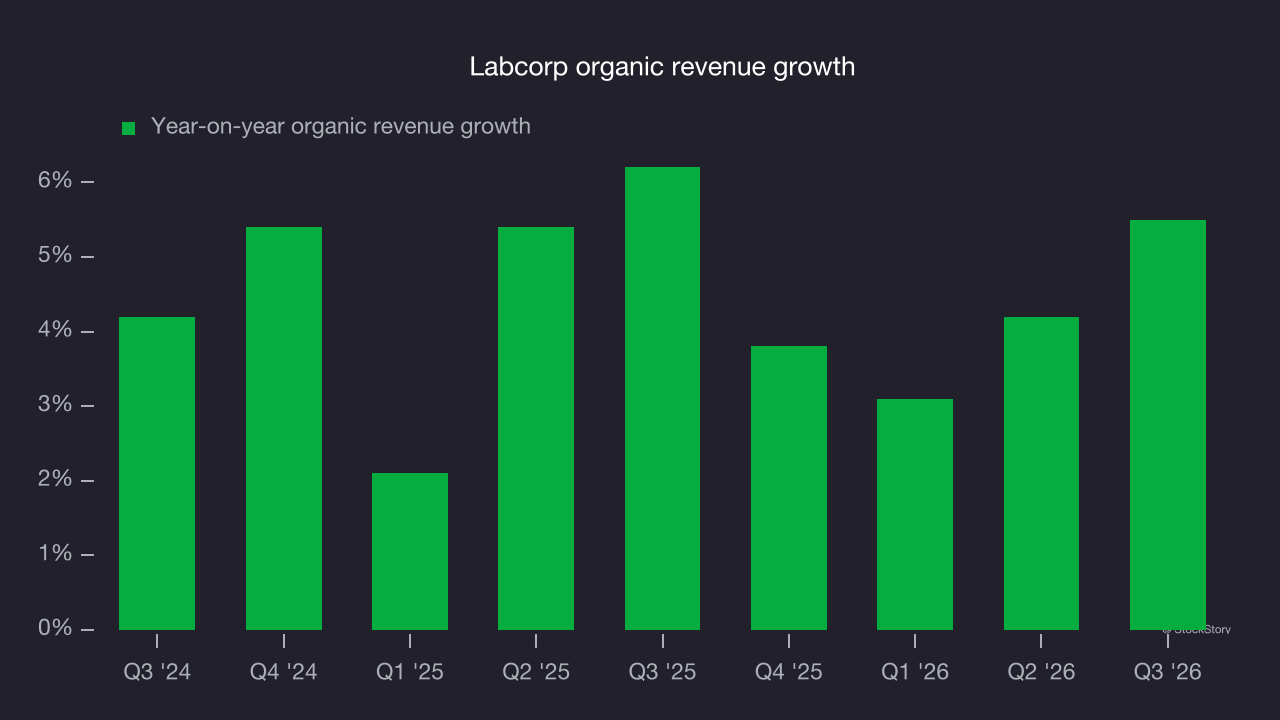
This quarter, Labcorp reported year-on-year revenue growth of 6.9%, and its $3.81 billion of revenue exceeded Wall Street’s consensus estimates by 1.2%.
Looking ahead, sell-side analysts expect revenue to grow 4.9% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand headwinds.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much a company earns after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Labcorp has managed its cost base well over the last five years. It demonstrated solid profitability for a healthcare business, producing an average adjusted operating margin of 15.3%.
Looking at the trend in its profitability, Labcorp’s adjusted operating margin decreased by 6.7 percentage points over the last five years. Even though its historical margin was healthy, shareholders will want to see Labcorp become more profitable in the future.
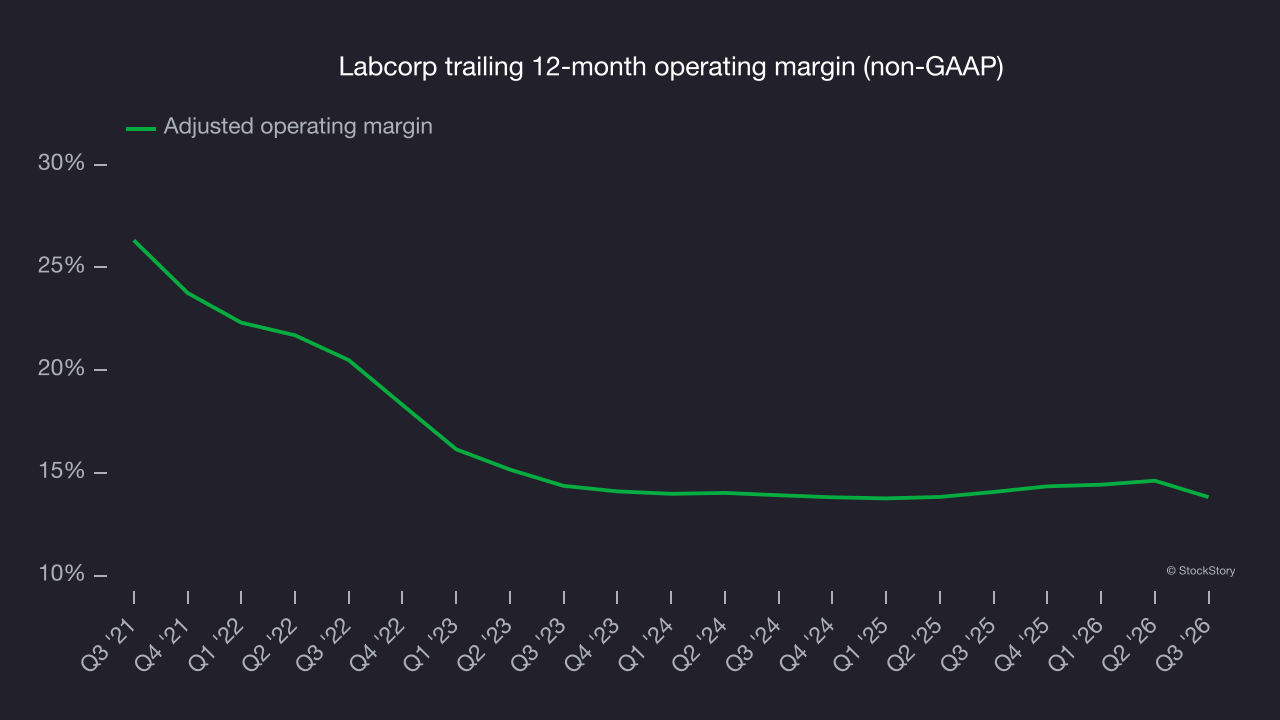
This quarter, Labcorp generated an adjusted operating margin of 11.4%, down 3 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Labcorp’s EPS declined by 10.9% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
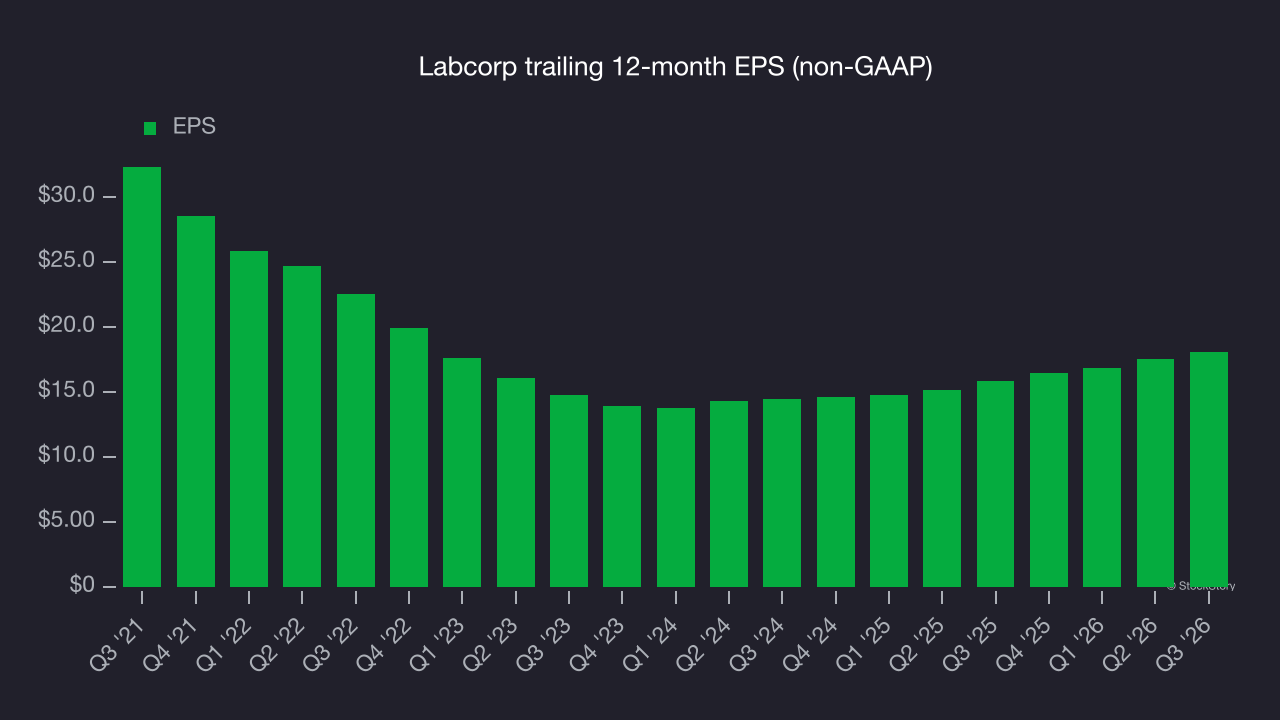
A closer look at Labcorp’s earnings helps explain its performance. As mentioned earlier, Labcorp’s adjusted operating margin declined by 6.7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but reveal less about a company’s fundamentals.
In Q3, Labcorp reported adjusted EPS of $4.78, up from $4.18 in the same quarter last year. This result beat analysts’ consensus estimates by 2.9%. Over the next 12 months, Wall Street expects Labcorp’s full-year EPS to grow 6.9% from $18.09 to $19.33, according to S&P.
Key takeaways from Labcorp’s Q3 results
Labcorp delivered modest beats on both organic revenue and total revenue, narrowly topping analysts’ consensus expectations for the former and Wall Street’s consensus estimates for the latter. Those were key positives for the quarter. Shares rose 2% to $337.75 immediately after the results.
Labcorp had a good quarter, but that alone doesn’t make it a buy. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in the stock. For more on Labcorp, read our full research report here (it’s free).