Oilfield services company Core Laboratories (NYSE: CLB) met Wall Street’s revenue expectations in Q3 2026, but revenue fell by 1.8% year on year to $132.1 million. Its non-GAAP profit of $0.16 per share was in line with analysts’ consensus estimates.
For more on Core Laboratories, read our full research report for free.
Core Laboratories (CLB) Q3 2026 highlights:
- Revenue $132.1 million vs S&P analysts’ consensus estimates of $131.6 million (1.8% year-on-year decline, in line)
- Adjusted EPS $0.16 vs S&P analysts’ consensus estimates of $0.16 (in line)
- Operating margin 9.1%, down from 11.9% in the same quarter last year
- Free cash flow margin 1.3%, down from 4.1% in the same quarter last year
- Market capitalization $474 million
Revenue growth
Cyclical industries such as energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Core Laboratories’s revenue grew at a weak 2.4% compounded annual growth rate over the last five years, falling short of our benchmarks.
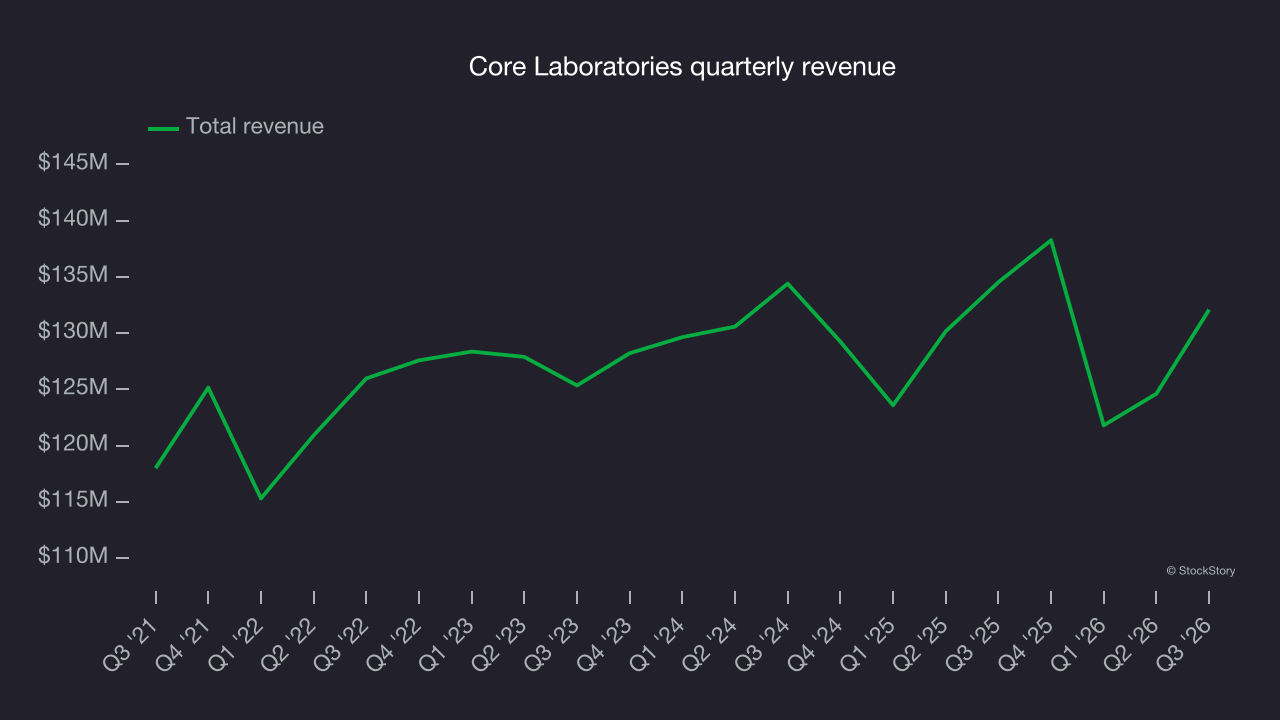
Within energy, a single time frame, even a long one, only sheds light on how well a company rode the last commodity cycle. An even longer, ten-year view helps assess whether a company compounds through cycles. Core Laboratories’s performance shows it grew over the past five years but relinquished its gains over the last ten years, as its revenue fell by 1.9% annually.
This quarter, Core Laboratories reported an uninspiring 1.8% year-on-year revenue decline to $132.1 million, in line with Wall Street’s consensus estimates.
Adjusted EBITDA margin
Core Laboratories was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 13.8% was among the worst in the energy upstream and integrated energy sector.
Core Laboratories’s EBITDA margin decreased by 1.1 percentage points over the last year. Its performance was poor, showing that costs were rising and it couldn’t pass them on to its customers.
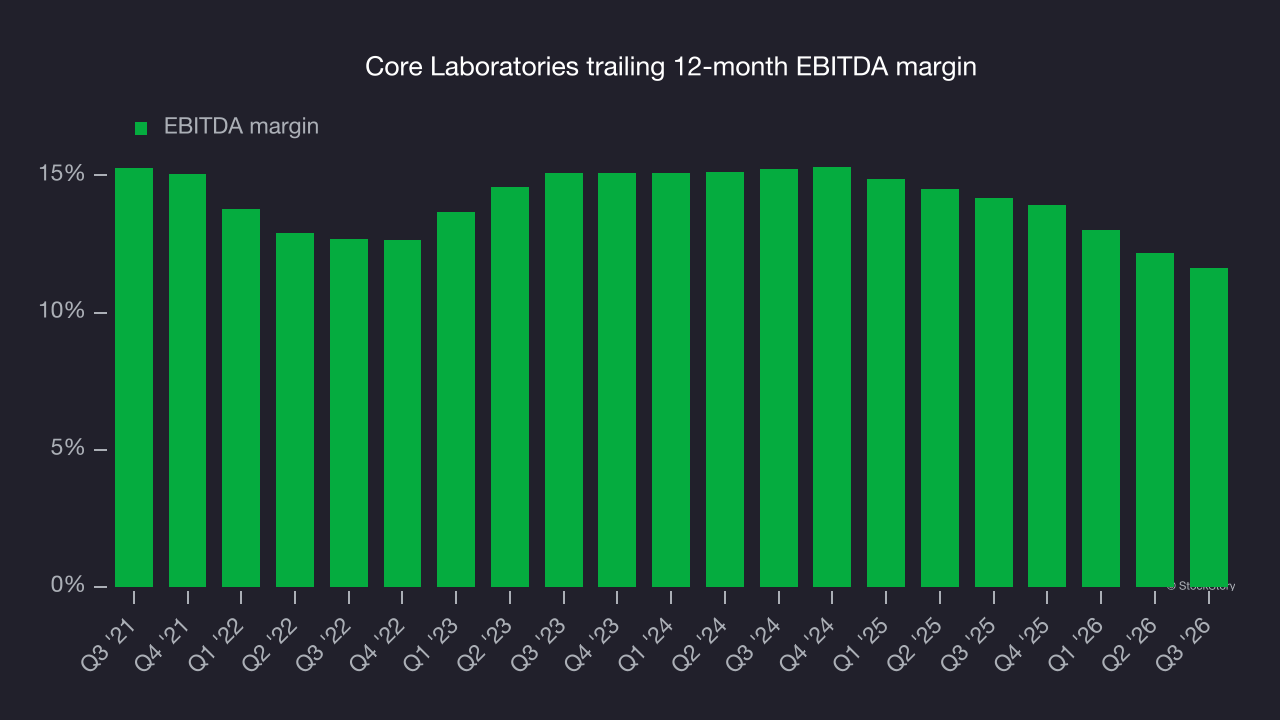
This quarter, Core Laboratories generated an EBITDA margin of 12.9%, down 2.1 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue. Adjusted EBITDA beat Wall Street’s consensus estimates by 1.6%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Core Laboratories has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 4%, below expectations for an upstream and integrated energy business.
While the level of free cash flow margins is important, their consistency matters just as much.
Core Laboratories’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 8.4 (lower is better), indicating reasonable insulation from commodity swings.
Why use free cash flow to assess stability against commodity prices rather than compare revenue or EBITDA to WTI crude prices in the case of Core Laboratories? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
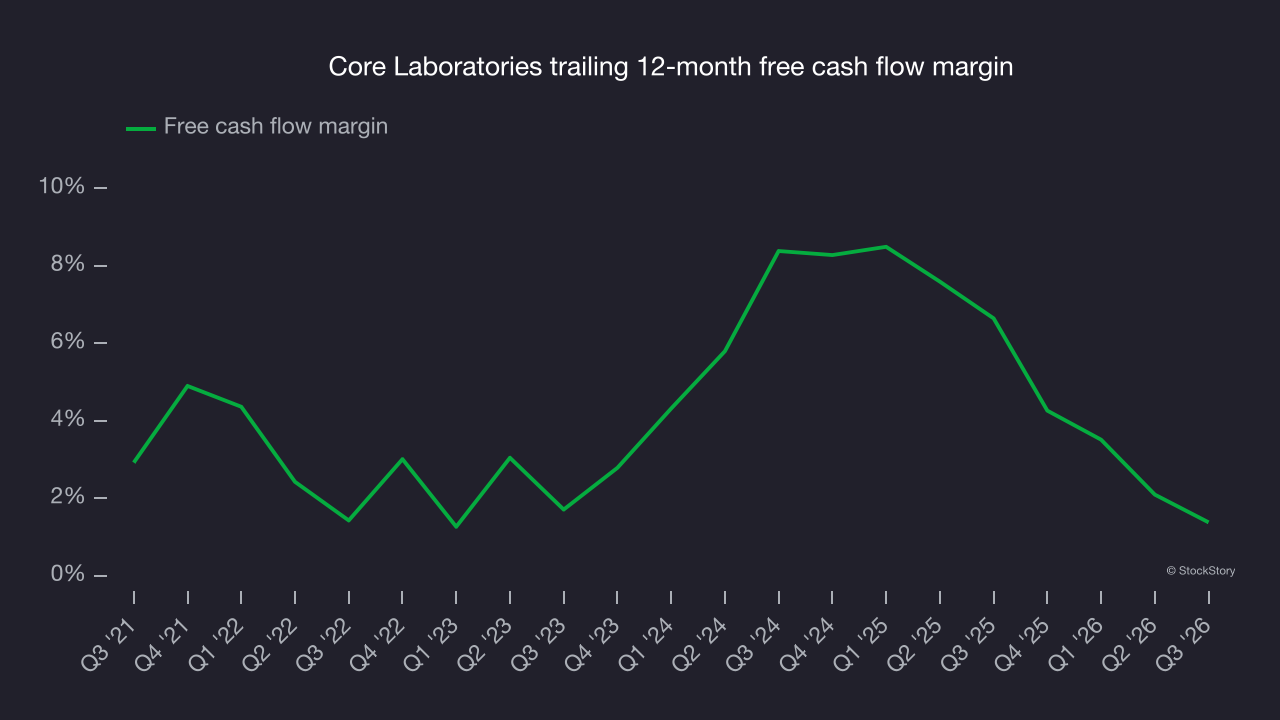
Core Laboratories’s free cash flow totaled $1.72 million in Q3, equivalent to a 1.3% margin. The company’s cash profitability deteriorated as its margin was 2.8 percentage points lower than in the same quarter last year, warranting closer attention. Short-term fluctuations typically aren’t a major concern because investment needs can be seasonal, but whether the trend continues in future quarters bears watching.
Key takeaways from Core Laboratories’s Q3 results
Revenue and EPS were both just in line with expectations. Investors were likely hoping for more, and shares traded down 3.7% to $10.12 immediately following the results.
When deciding whether to buy the stock, consider the bigger picture of valuation and business quality as well as the latest earnings. Read the full research report here for more on those factors (it’s free).