RV Manufacturer Winnebago (NYSE: WGO) fell short of the market’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), with sales falling 17% year on year to $645.1 million. The company’s full-year revenue guidance of $2.73 billion at the midpoint came in 2.8% below analysts’ estimates. Its non-GAAP profit of $0.49 per share was 5.3% above analysts’ consensus estimates.
Is now the time to buy Winnebago? Find out by accessing our full research report, it’s free.
Winnebago (WGO) Q3 CY2026 highlights:
- Revenue: $645.1 million vs analyst estimates of $660.9 million (17% year-on-year decline, 2.4% miss)
- Adjusted EPS: $0.49 vs analyst estimates of $0.47 (5.3% beat)
- Adjusted EBITDA: $32.6 million vs analyst estimates of $31.48 million (5.1% margin, 3.6% beat)
- Adjusted EPS guidance for the upcoming financial year 2027 is $1.95 at the midpoint, missing analyst estimates by 17.3%
- Operating Margin: 2.7%, in line with the same quarter last year
- Free Cash Flow Margin: 21%, down from 22% in the same quarter last year
- Market Capitalization: $655 million
“Even as market pressure across our segments persisted, we began to see encouraging early signs across several strategic initiatives: real traction in the Winnebago Motorhome transformation, stabilizing share trends and improving market share at Grand Design Towables, growing market penetration for Grand Design Motorized, and impressive share growth at Winnebago Towables,” Happe said. “We took actions to rationalize capacity, drive operational efficiency, and better align our manufacturing footprint with market demand. These initiatives remain at different stages of development, and we expect their financial contribution to build gradually, with greater value accruing in future years. Together with the strong continued growth of Barletta's market presence in pontoons and our growing portable power offerings, this progress reinforces our confidence in the long-term earnings potential of our portfolio.
Company overview
Created to provide high-quality, affordable RVs to the post-war American family, Winnebago (NYSE: WGO) is a manufacturer of recreational vehicles, providing a range of motorhomes, travel trailers, and fifth-wheel products for outdoor and adventure lifestyles.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Winnebago’s demand was weak over the last five years as its sales fell at a 5.7% annual rate. This wasn’t a great result and suggests it’s a low quality business.
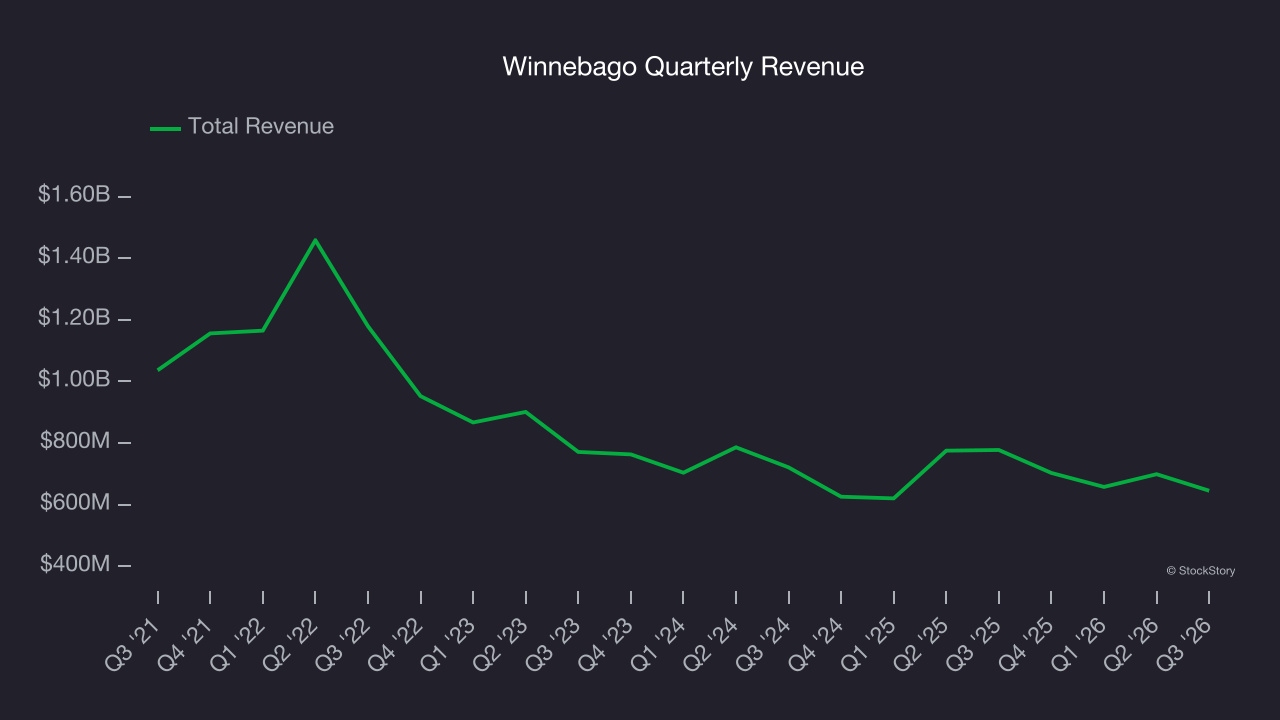
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Winnebago’s annualized revenue declines of 4.6% over the last two years suggest its demand continued shrinking. 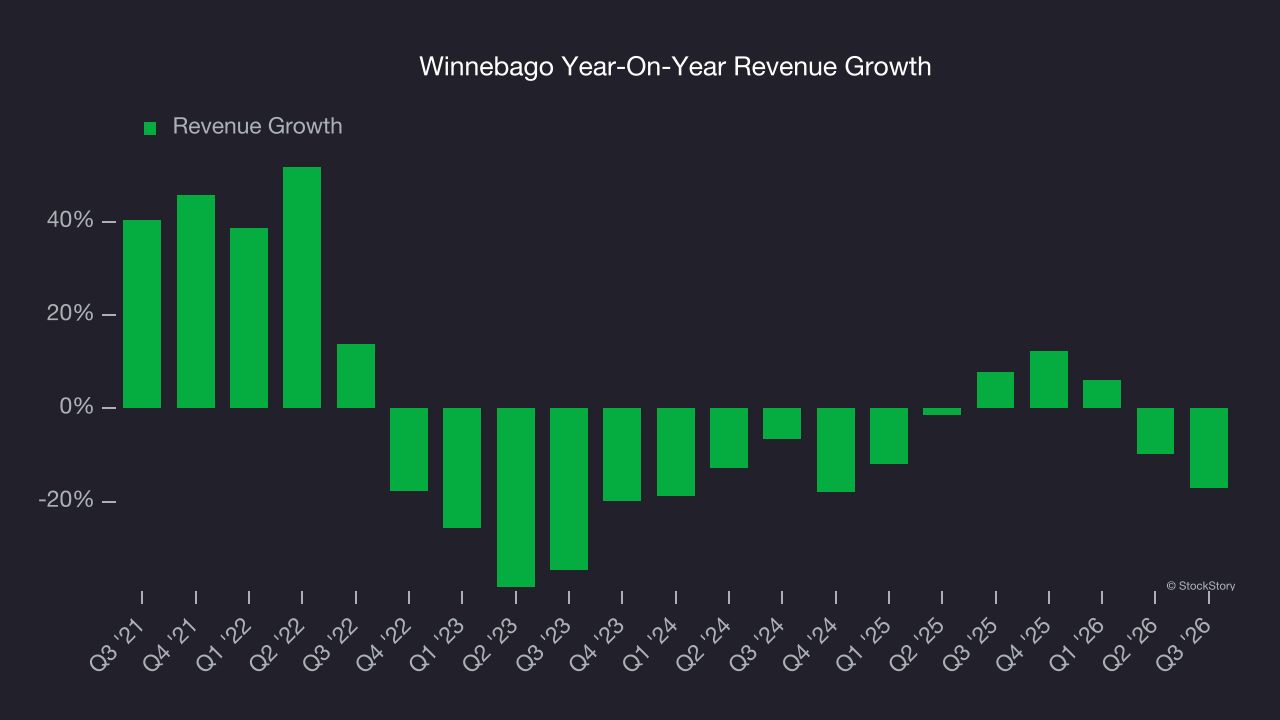
Winnebago also breaks out the revenue for its most important segments, Motorhomes and Towables, which are 50.2% and 34.1% of revenue. Over the last two years, Winnebago’s Motorhomes revenue (homes on wheels) averaged 3.8% year-on-year growth. On the other hand, its Towables revenue (non-motorized vehicles) averaged 7.6% declines. 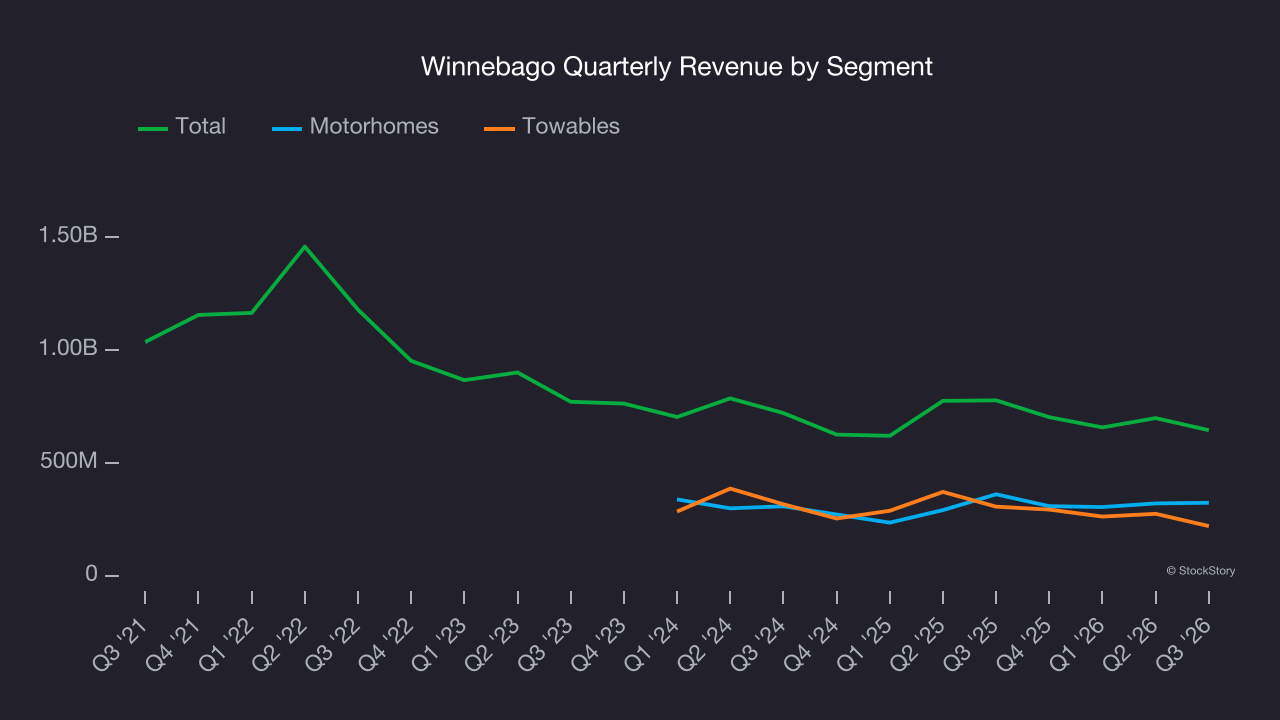
This quarter, Winnebago missed Wall Street’s estimates and reported a rather uninspiring 17% year-on-year revenue decline, generating $645.1 million of revenue.
Looking ahead, sell-side analysts expect revenue to grow 4.2% over the next 12 months. Although this projection suggests its newer products and services will catalyze better top-line performance, it is still below the sector average.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Winnebago was profitable over the last five years but held back by its large cost base. Its average operating margin of 6.5% was weak for an industrials business. This result isn’t too surprising given its low gross margin as a starting point.
Analyzing the trend in its profitability, Winnebago’s operating margin decreased by 9.3 percentage points over the last five years. Winnebago’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers.
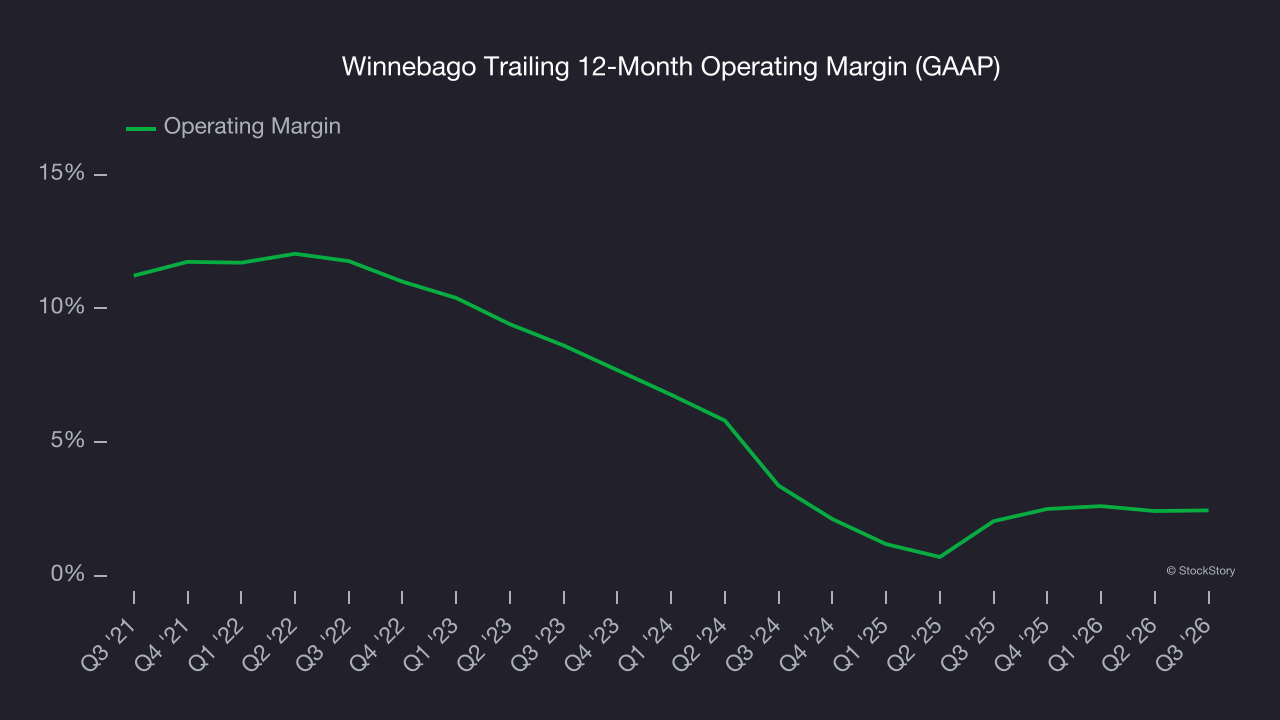
This quarter, Winnebago generated an operating margin profit margin of 2.7%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Sadly for Winnebago, its EPS declined by 26.8% annually over the last five years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
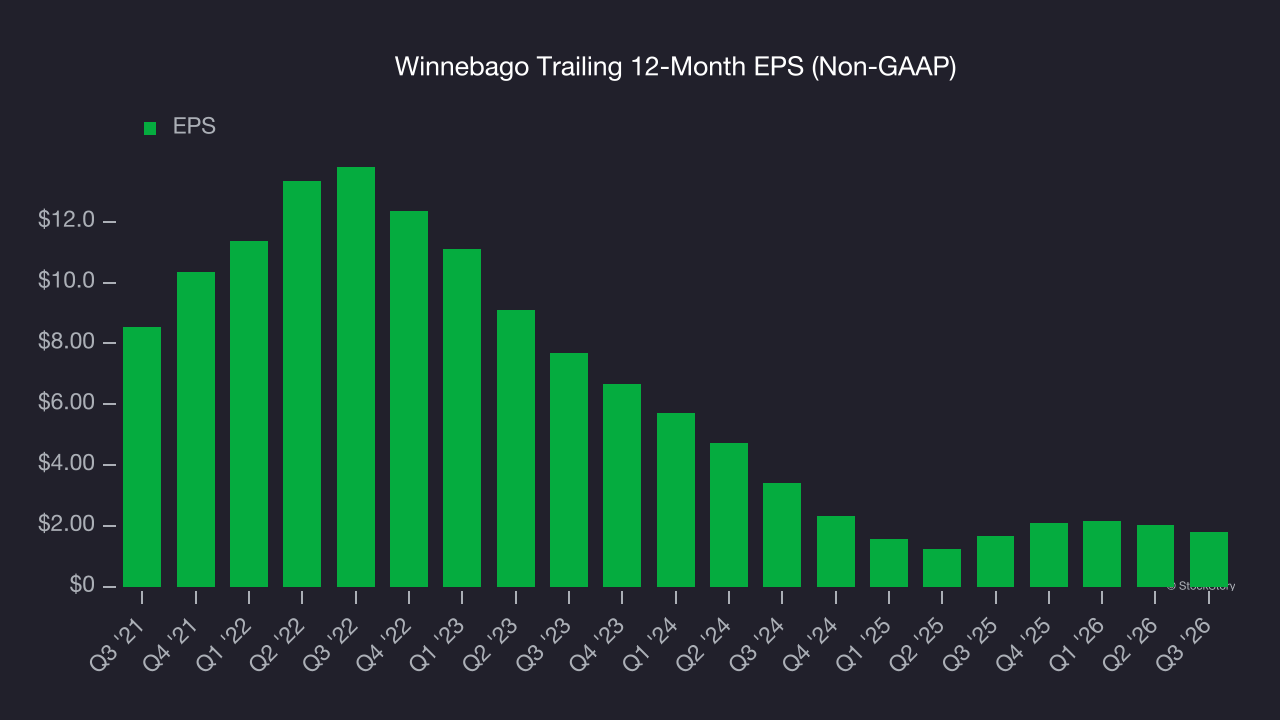
Diving into the nuances of Winnebago’s earnings can give us a better understanding of its performance. As we mentioned earlier, Winnebago’s operating margin was flat this quarter but declined by 9.3 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Winnebago, its two-year annual EPS declines of 27.2% are similar to its five-year trend. These results were bad no matter how you slice the data.
In Q3, Winnebago reported adjusted EPS of $0.49, down from $0.71 in the same quarter last year. Despite falling year on year, this print beat analysts’ estimates by 5.3%. Over the next 12 months, Wall Street expects Winnebago’s full-year EPS to grow 30.8% from $1.80 to $2.35.
Key takeaways from Winnebago’s Q3 results
It was encouraging to see Winnebago beat analysts’ EBITDA expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its full-year EPS guidance missed and its revenue fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock traded up 4.8% to $24.29 immediately after reporting.
So do we think Winnebago is an attractive buy at the current price? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).