Energy infrastructure company Kinder Morgan (NYSE: KMI) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 9.3% year on year to $4.53 billion. Its non-GAAP profit of $0.35 per share was 6.3% above analysts’ consensus estimates.
Is now the time to buy Kinder Morgan? Find out by accessing our full research report, it’s free.
Kinder Morgan (KMI) Q3 2026 highlights:
- Revenue: $4.53 billion vs analyst estimates of $3.73 billion (9.3% year-on-year growth, 21.5% beat)
- Adjusted EPS: $0.35 vs analyst estimates of $0.33 (6.3% beat)
- Operating Margin: 25.6%, in line with the same quarter last year
- Free Cash Flow Margin: 12%, down from 15% in the same quarter last year
- Market Capitalization: $74.75 billion
“We are equally proud of the financial and operational excellence that resulted in a record third quarter. Strong financial contributions from our business segments delivered third quarter 2026 net income attributable to KMI of $764 million, 22% higher than the third quarter of 2025, while Adjusted EPS and Adjusted EBITDA were 21% and 9% higher, respectively, than the third quarter of 2025.”
Company overview
Operating what amounts to the toll roads of the energy industry, Kinder Morgan (NYSE: KMI) transports natural gas, refined petroleum products, and crude oil through its pipeline network across North America.
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Over the last five years, Kinder Morgan grew its sales at a weak 3.7% compounded annual growth rate. This wasn’t a great result compared to the rest of the energy upstream and integrated energy sector, but there are still things to like about Kinder Morgan.
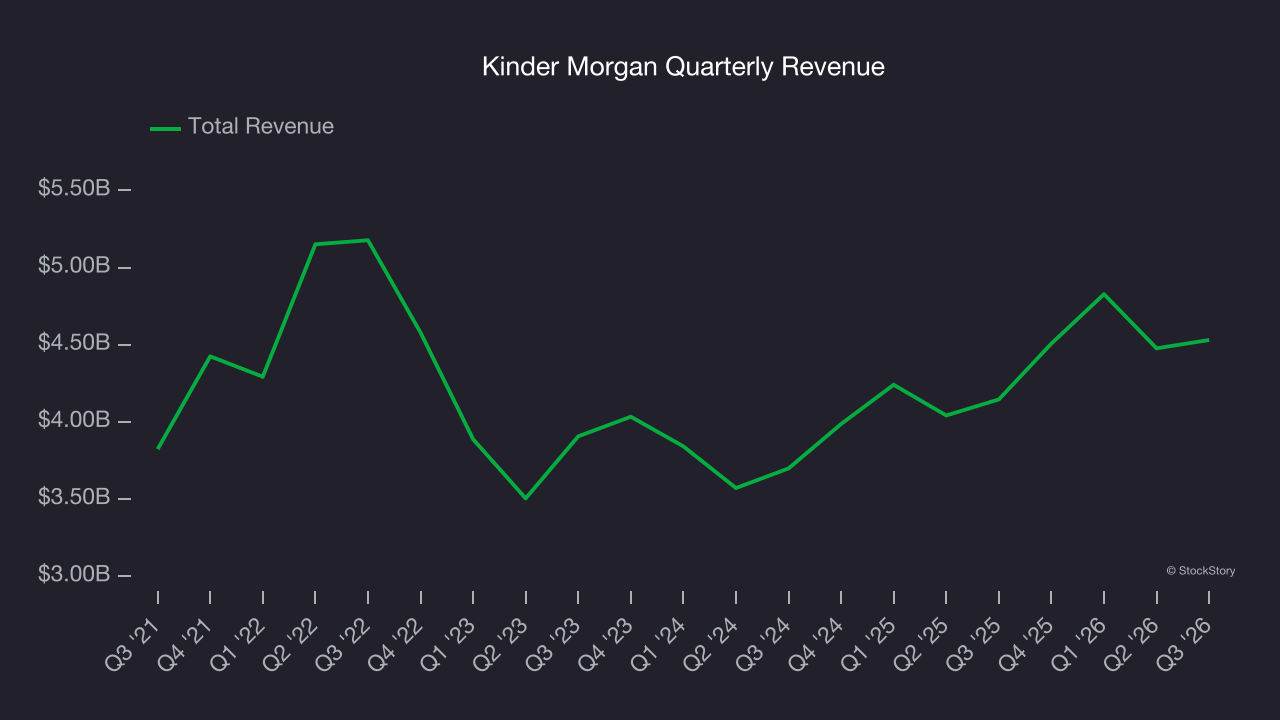
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. Kinder Morgan’s annualized revenue growth of 3.3% over the last ten years aligns with its five-year trend, suggesting its demand was stable.
This quarter, Kinder Morgan reported year-on-year revenue growth of 9.3%, and its $4.53 billion of revenue exceeded Wall Street’s estimates by 21.5%.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted EBITDA margin
Adjusted EBITDA margin captures the true operating profitability of an energy producer by removing accounting noise around depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Kinder Morgan has been an efficient company over the last five years. It was one of the more profitable businesses in the energy upstream and integrated energy sector, boasting an average EBITDA margin of 46.8%.
Looking at the trend in its profitability, Kinder Morgan’s EBITDA margin rose by 9.3 percentage points over the last year, as its sales growth gave it operating leverage.
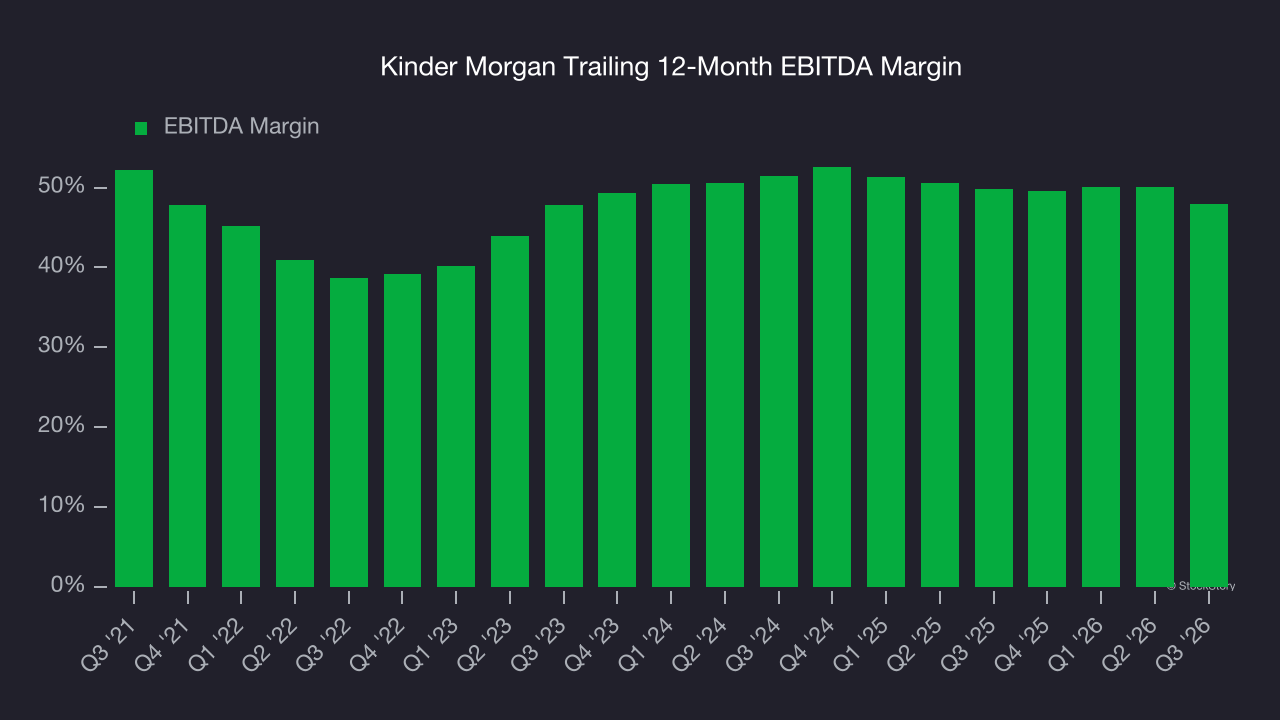
In Q3, Kinder Morgan generated an EBITDA margin profit margin of 39.5%, down 8.6 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. This adjusted EBITDA fell short of Wall Street’s estimates.
Cash is king
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Kinder Morgan has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 19.5% over the last five years.
Absolute FCF margin levels matter but so does stability of free cash flow. All else equal, we’d prefer a 25.0% average free cash flow margin that is quite steady no matter how commodity prices behave rather than extremely high margins when times are good and negative ones when they’re tough.
Kinder Morgan’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 2.4 (lower is better), indicating excellent insulation from commodity swings. This stability supports superior capital access in downturns and positions Kinder Morgan to act as a consolidator when weaker peers are forced to retrench.
You may be asking why we wait until the free cash flow line to perform this stability analysis versus commodity prices. Why not compare revenue or EBITDA to WTI Crude prices in the case of Kinder Morgan? Because what ultimately matters is not how much revenue or profit you earn when prices are high but how much cash you can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging prowess to growth and maintenance capex to management behavior during good times and bad.
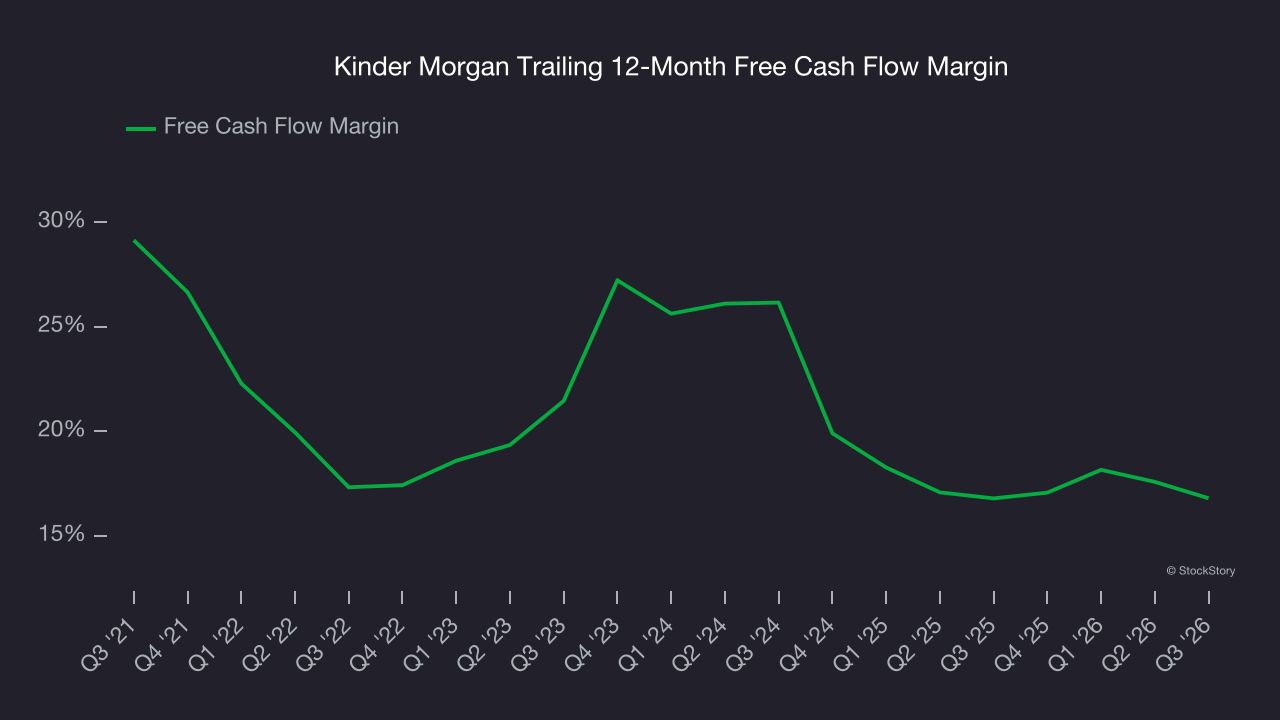
Kinder Morgan’s free cash flow clocked in at $545 million in Q3, equivalent to a 12% margin. The company’s cash profitability regressed as it was 3 percentage points lower than in the same quarter last year, but we wouldn’t put too much weight on the short term because investment needs can be seasonal, causing temporary swings. Long-term trends carry greater meaning.
Key takeaways from Kinder Morgan’s Q3 results
We were impressed by how significantly Kinder Morgan blew past analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Zooming out, we think this quarter featured some important positives. The stock traded up 1.6% to $34.54 immediately after reporting.
Sure, Kinder Morgan had a solid quarter, but if we look at the bigger picture, is this stock a buy? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).