Technology and consulting giant IBM (NYSE: IBM) reported revenue ahead of Wall Street’s expectations in Q3 2026, with sales up 4.7% year on year to $17.1 billion. Its non-GAAP profit of $2.95 per share was 2.7% above analysts’ consensus estimates.
Is now the time to buy IBM? Find out by accessing our full research report, it’s free.
IBM (IBM) Q3 2026 highlights:
- Revenue: $17.1 billion vs analyst estimates of $16.79 billion (4.7% year-on-year growth, 1.9% beat)
- Adjusted EPS: $2.95 vs analyst estimates of $2.87 (2.7% beat)
- Adjusted EBITDA: $4.9 billion vs analyst estimates of $4.67 billion (28.6% margin, 4.9% beat)
- Maintained full-year revenue growth guidance of "constant currency revenue growth in the range of four-to-five percent. At current foreign exchange rates, currency is expected to be neutral to growth for the year"
- Raised full-year free cash flow guidance to "increase by more than $1 billion year-over-year" (prior was just "increase by about $1 billion year-over-year")
- Free Cash Flow Margin: 17.7%, up from 14.5% in the same quarter last year
- Market Capitalization: $227.9 billion
"Disciplined execution throughout the quarter drove accelerated revenue growth and strong free cash flow. Our clients are now deploying Super Intelligence in ways that transform entire operating models, instead of simply addressing narrow or novel problems. IBM's technology and expertise are helping organizations drive growth and serve customers with greater speed, precision and efficiency than ever before," said Arvind Krishna, IBM chairman, president and chief executive officer. "For the full year, we continue to expect constant currency revenue growth in the range of four-to-five percent, and we now expect free cash flow to increase by more than $1 billion year-over-year."
Company overview
With a corporate history spanning over a century and once known for its iconic mainframe computers, IBM (NYSE: IBM) provides hybrid cloud computing platforms, AI solutions, consulting services, and enterprise infrastructure to help businesses modernize their operations.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
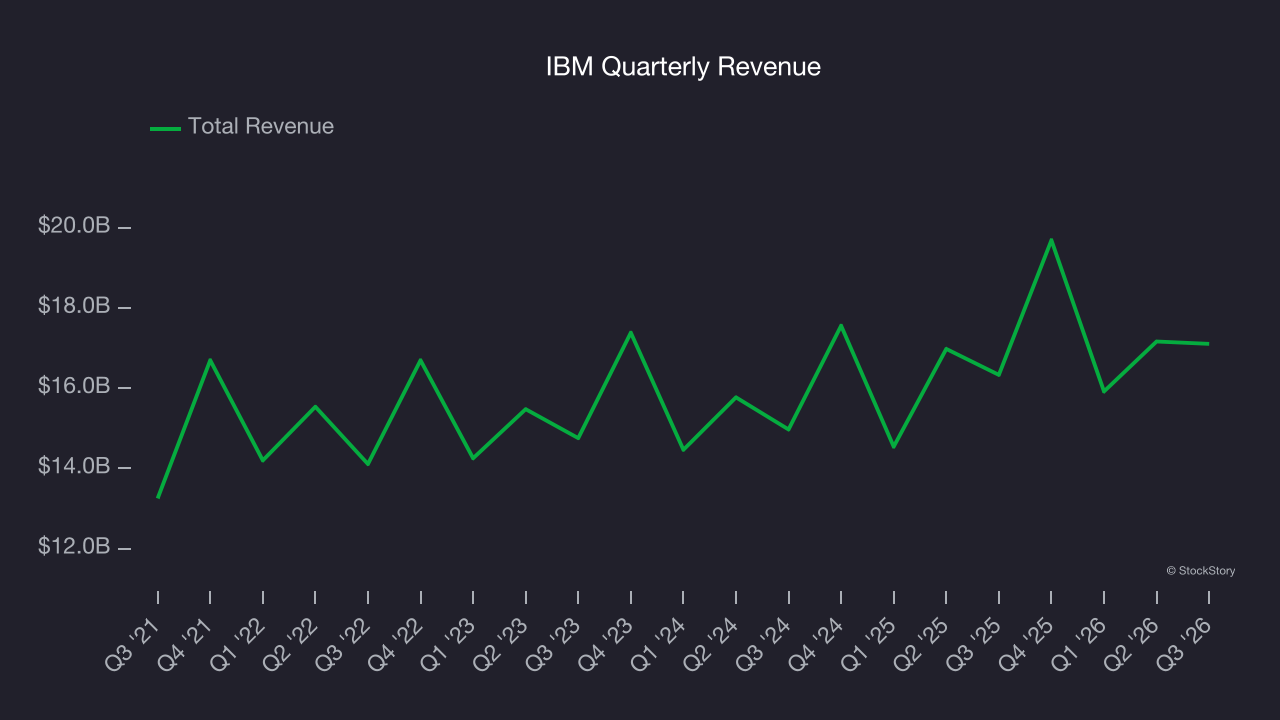
With $69.87 billion in revenue over the past 12 months, IBM is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s challenging to maintain high growth rates when you’ve already captured a large portion of the addressable market. For IBM to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
As you can see below, IBM’s 4.4% annualized revenue growth over the last five years was mediocre. This shows it couldn’t generate demand in any major way and is a tough starting point for our analysis.
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. IBM’s annualized revenue growth of 5.7% over the last two years is above its five-year trend, suggesting some bright spots. 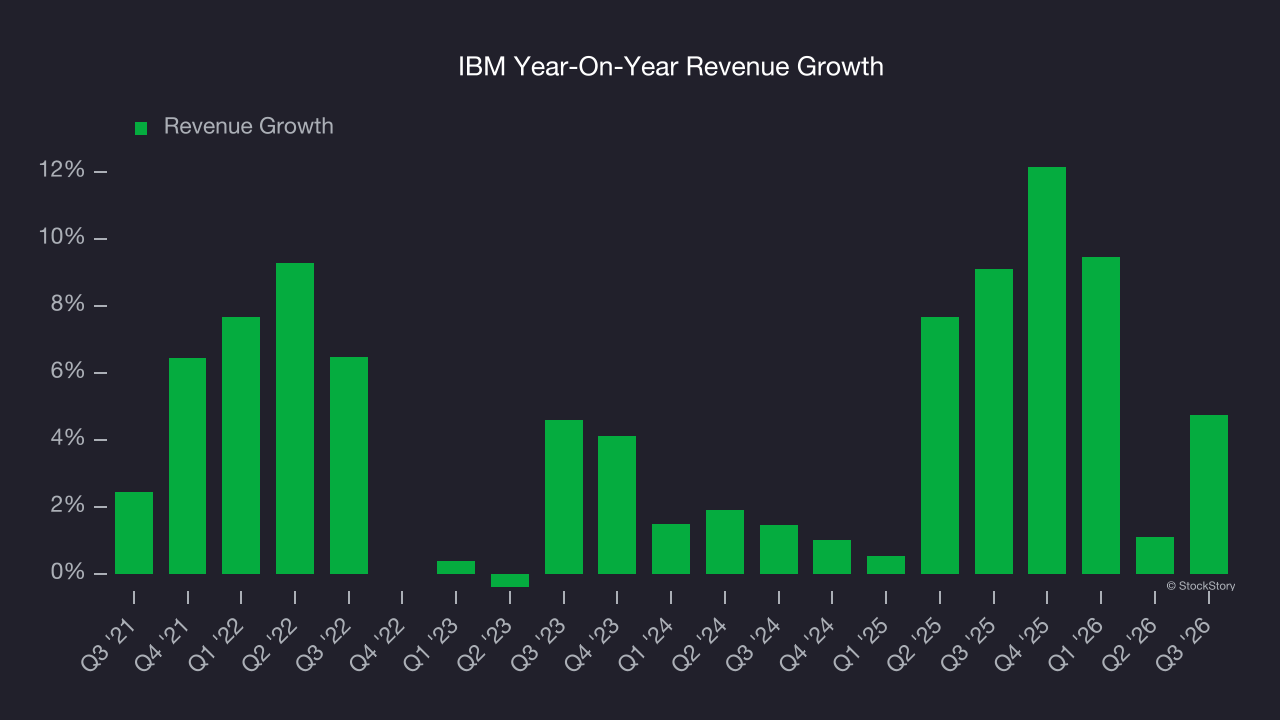
We can better understand the company’s revenue dynamics by analyzing its most important segment, Software. Over the last two years, IBM’s Software revenue averaged 9.4% year-on-year growth. This segment has outperformed its total sales during the same period, lifting the company’s performance. 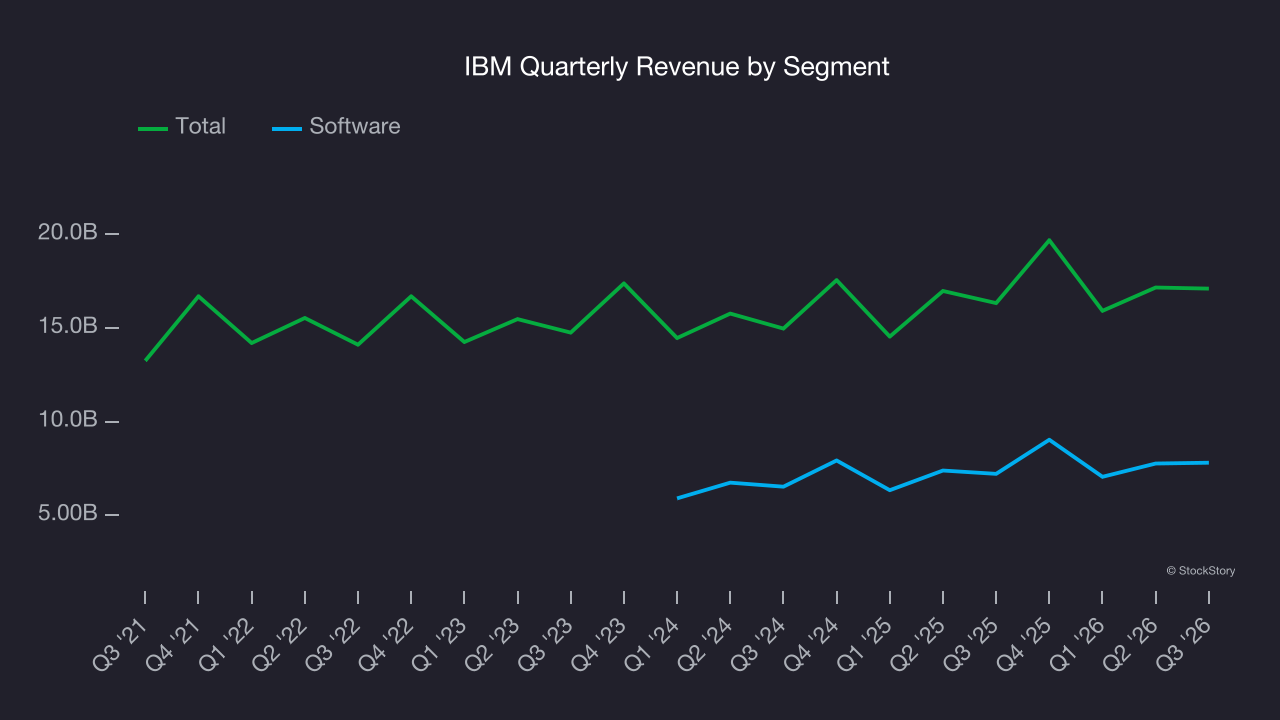
This quarter, IBM reported modest year-on-year revenue growth of 4.7% but beat Wall Street’s estimates by 1.9%.
Looking ahead, sell-side analysts expect revenue to grow 4.3% over the next 12 months, similar to its two-year rate. This projection is underwhelming and suggests its products and services will see some demand headwinds.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
IBM has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, boasting an average operating margin of 15.4%.
Looking at the trend in its profitability, IBM’s operating margin rose by 3.9 percentage points over the last five years, as its sales growth gave it operating leverage.
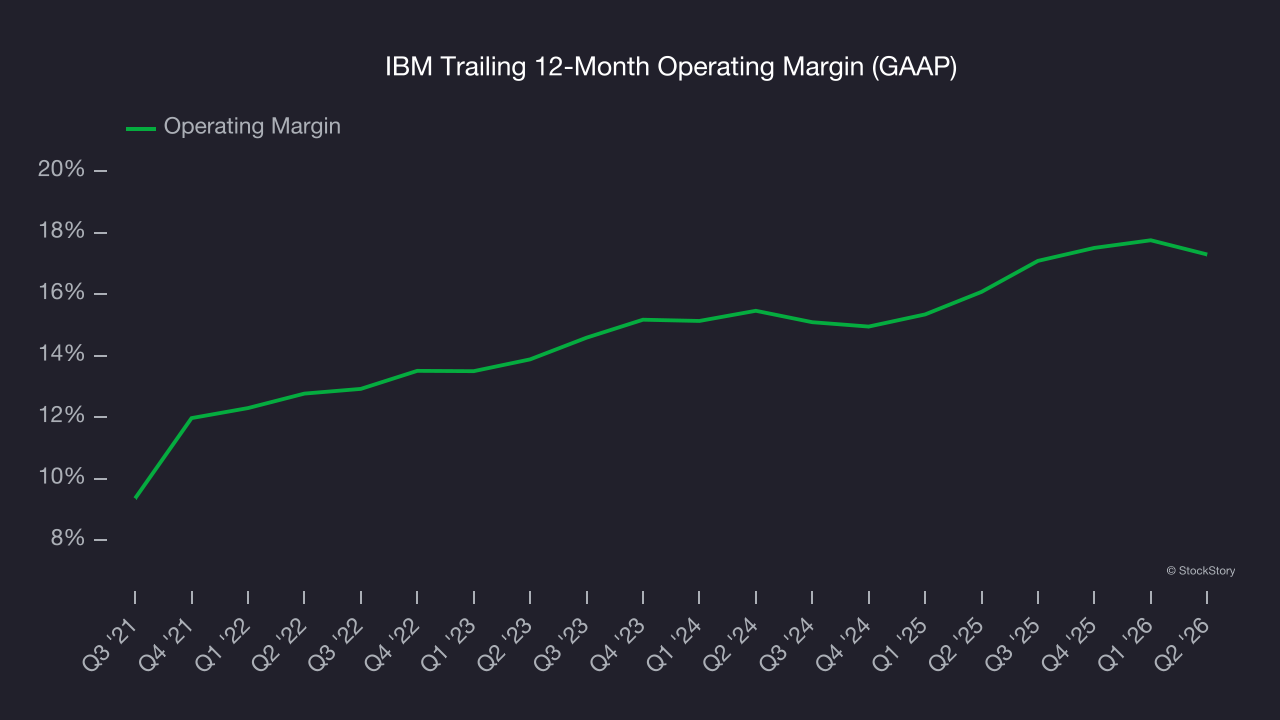
in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
IBM’s EPS grew at 7.2% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 4.4% annualized revenue growth and tells us the company became more profitable on a per-share basis as it expanded.
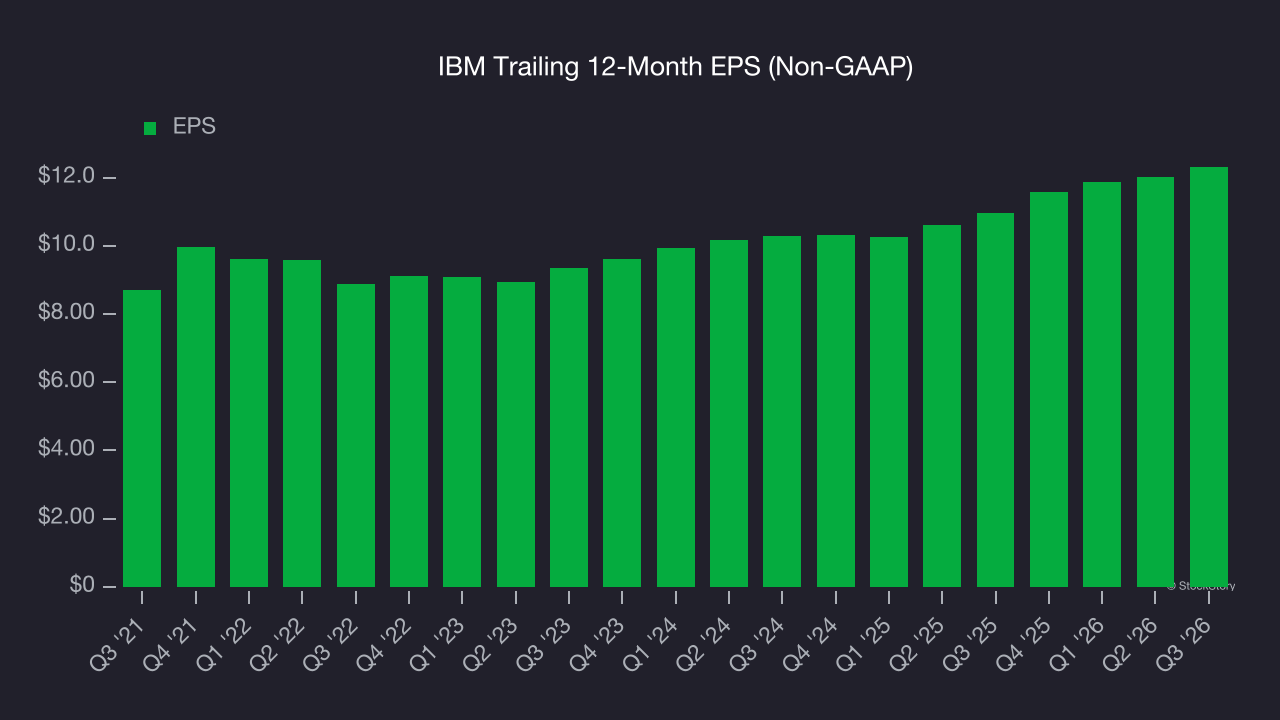
We can take a deeper look into IBM’s earnings to better understand the drivers of its performance. As we mentioned earlier, IBM’s operating margin expanded by 3.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For IBM, its two-year annual EPS growth of 9.4% was higher than its five-year trend. Accelerating earnings growth is almost always an encouraging data point.
In Q3, IBM reported adjusted EPS of $2.95, up from $2.65 in the same quarter last year. This print beat analysts’ estimates by 2.7%. Over the next 12 months, Wall Street expects IBM’s full-year EPS to grow 4.9% from $12.31 to $12.92.
Key takeaways from IBM’s Q3 results
It was encouraging to see IBM beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Looking ahead, while revenue growth guidance for the full year was maintained, free cash flow guidance for the same period was raised. Overall, this print had some key positives. The stock traded up 7.4% to $269.50 immediately after reporting.
IBM may have had a good quarter, but does that mean you should invest right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).