Fluid and coating equipment company Graco (NYSE: GGG) missed Wall Street’s revenue expectations in Q3 2026, but sales rose 7.9% year on year to $586.4 million. Next quarter’s revenue guidance of $625 million underwhelmed, coming in 3.6% below analysts’ estimates. Its non-GAAP profit of $0.81 per share was 3.1% below analysts’ consensus estimates.
Is now the time to buy Graco? Find out by accessing our full research report, it’s free.
Graco (GGG) Q3 2026 highlights:
- Revenue: $586.4 million vs analyst estimates of $590.5 million (7.9% year-on-year growth, 0.7% miss)
- Adjusted EPS: $0.81 vs analyst expectations of $0.84 (3.1% miss)
- Revenue Guidance for Q4 2026 is $625 million at the midpoint, below analyst estimates of $648.5 million
- Operating Margin: 25.3%, down from 30.3% in the same quarter last year
- Market Capitalization: $13.13 billion
“Graco delivered a solid quarter, with broad-based performance across our businesses and geographies. Growth in professional paint, powder finishing and semiconductor applications, together with contributions from recent acquisitions, demonstrates the diversity of our portfolio and the strength of our market positions,” said Mark Sheahan, President and Chief Executive Officer. “We are pleased with the consistency of our execution and remain focused on building on that momentum. We were encouraged that incoming organic orders increased 7% in the quarter and 4% for the year-to-date, with all three segments contributing to year-to-date order growth.”
Company overview
Founded in 1926, Graco (NYSE: GGG) is an industrial company specializing in the development and manufacturing of fluid-handling systems and products.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, Graco’s 3.8% annualized revenue growth over the last five years was sluggish. This fell short of our benchmark for the industrials sector and is a tough starting point for our analysis.
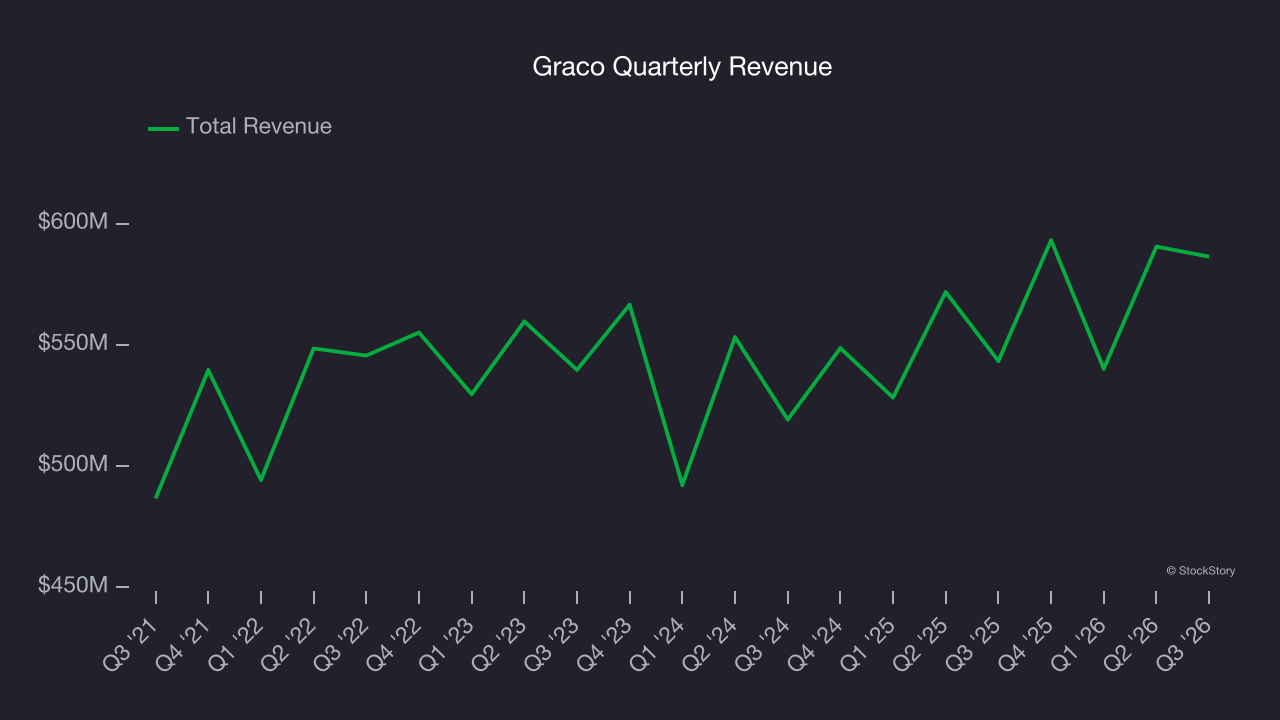
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Graco’s annualized revenue growth of 4.1% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 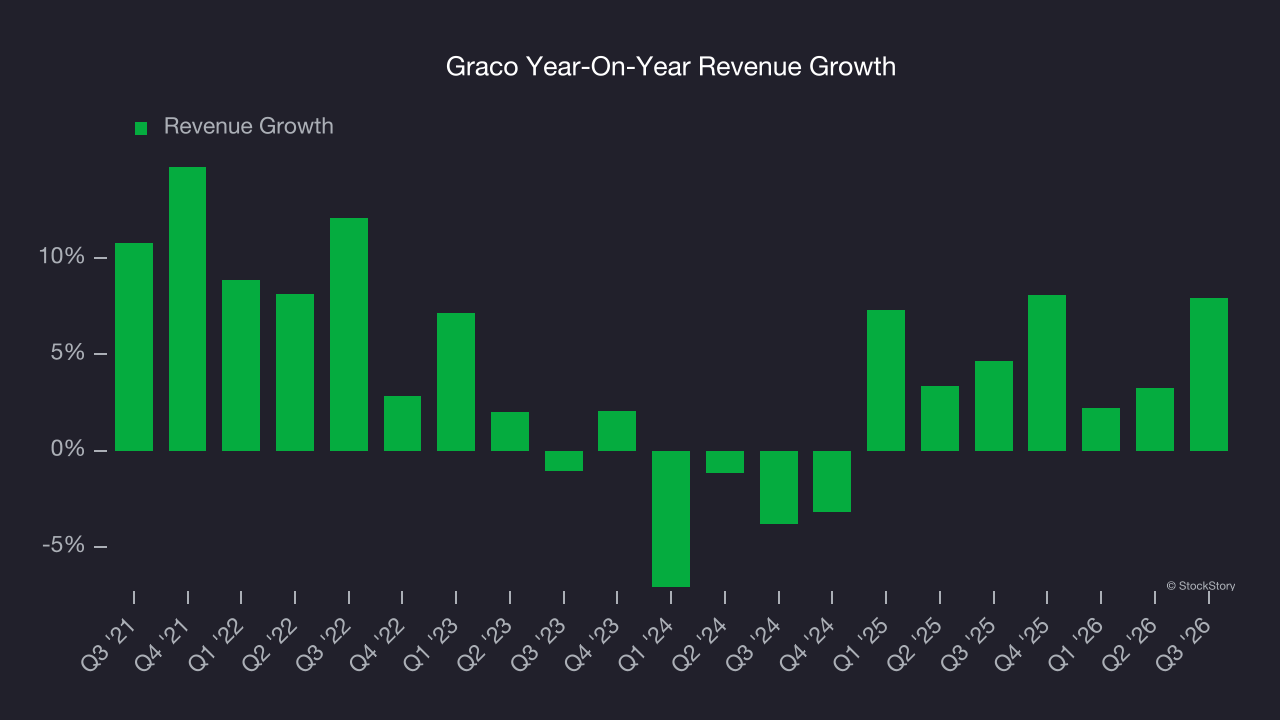
We can dig further into the company’s revenue dynamics by analyzing its most important segments, Contractor and Process, which are 47.1% and 45.1% of revenue. Over the last two years, Graco’s Contractor revenue averaged 6.4% year-on-year growth while its Process revenue (pumps, valves, hoses) averaged 49% growth. 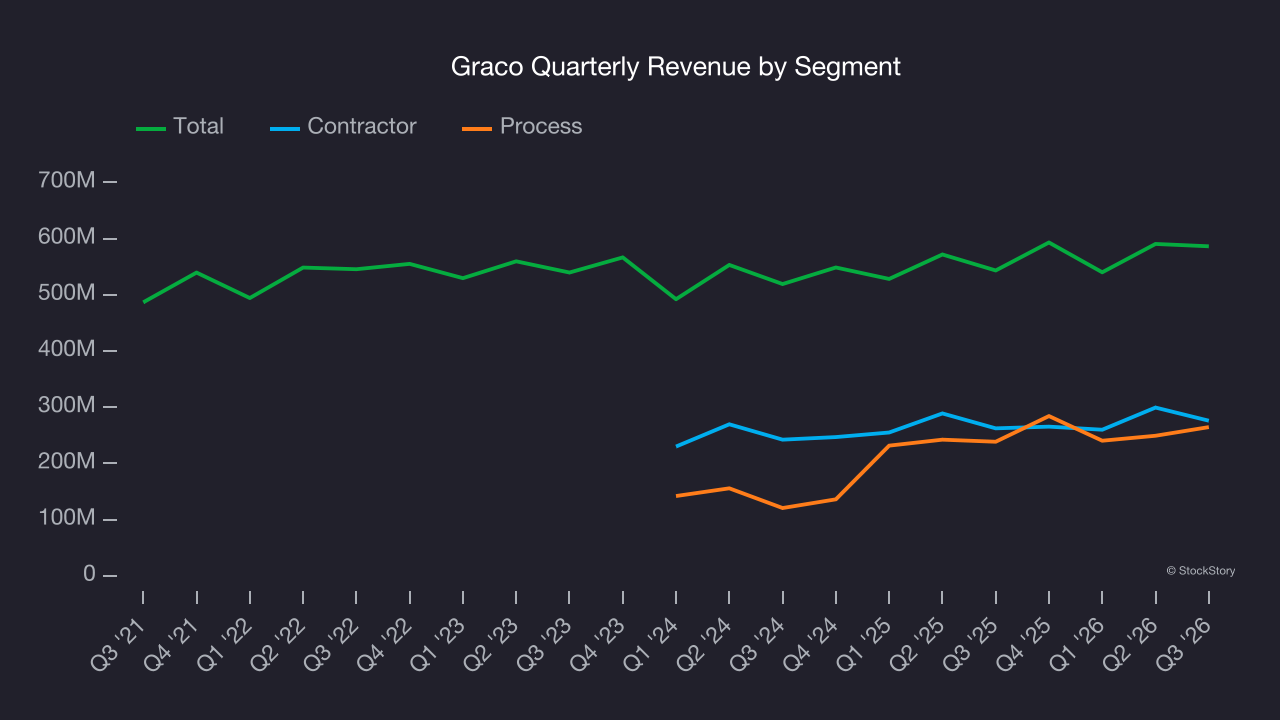
This quarter, Graco’s revenue grew by 7.9% year on year to $586.4 million, missing Wall Street’s estimates. Company management is currently guiding for a 5.4% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.4% over the next 12 months, an improvement versus the last two years. This projection is above the sector average and indicates its newer products and services will spur better top-line performance.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating margin
Graco’s operating margin has more or less stayed the same over the last 12 months , averaging 27.6% over the last five years. This profitability was elite for an industrials business thanks to its efficient cost structure and economies of scale. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Analyzing the trend in its profitability, Graco’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
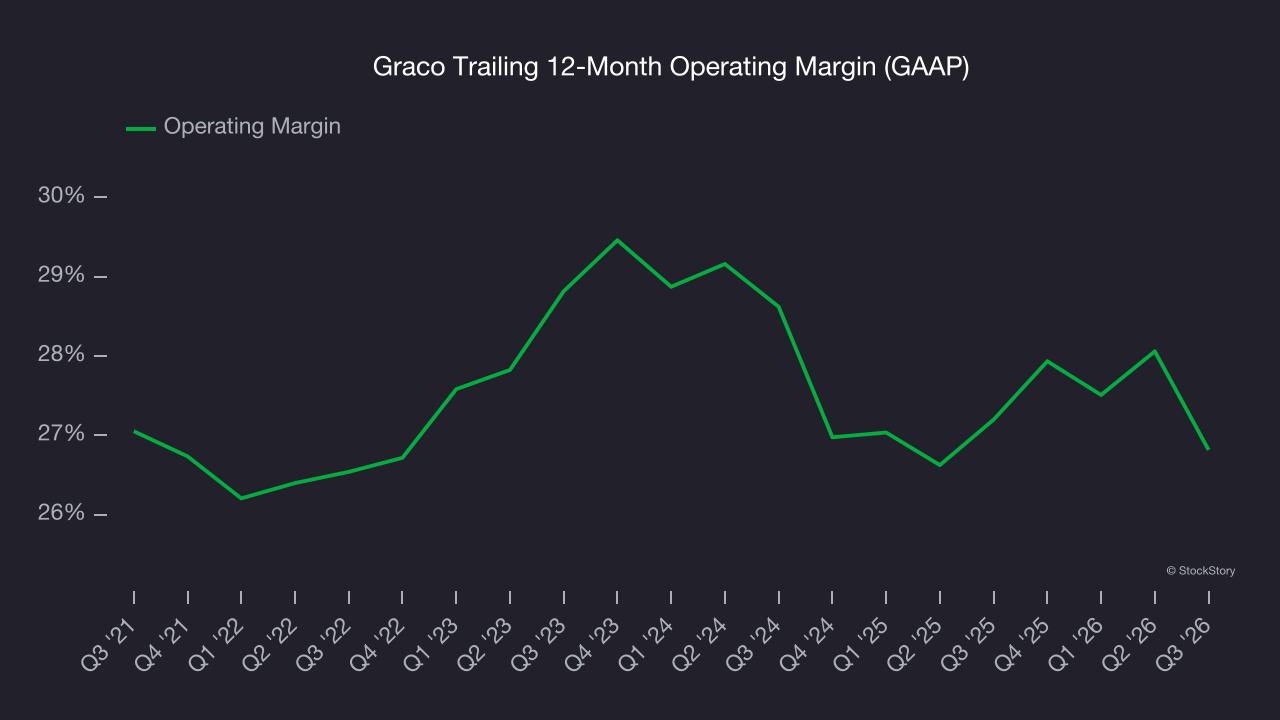
This quarter, Graco generated an operating margin profit margin of 25.3%, down 5.1 percentage points year on year. Since Graco’s operating margin decreased more than its gross margin, we can assume it was less efficient because expenses such as marketing, R&D, and administrative overhead increased.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Graco’s unimpressive 5.8% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
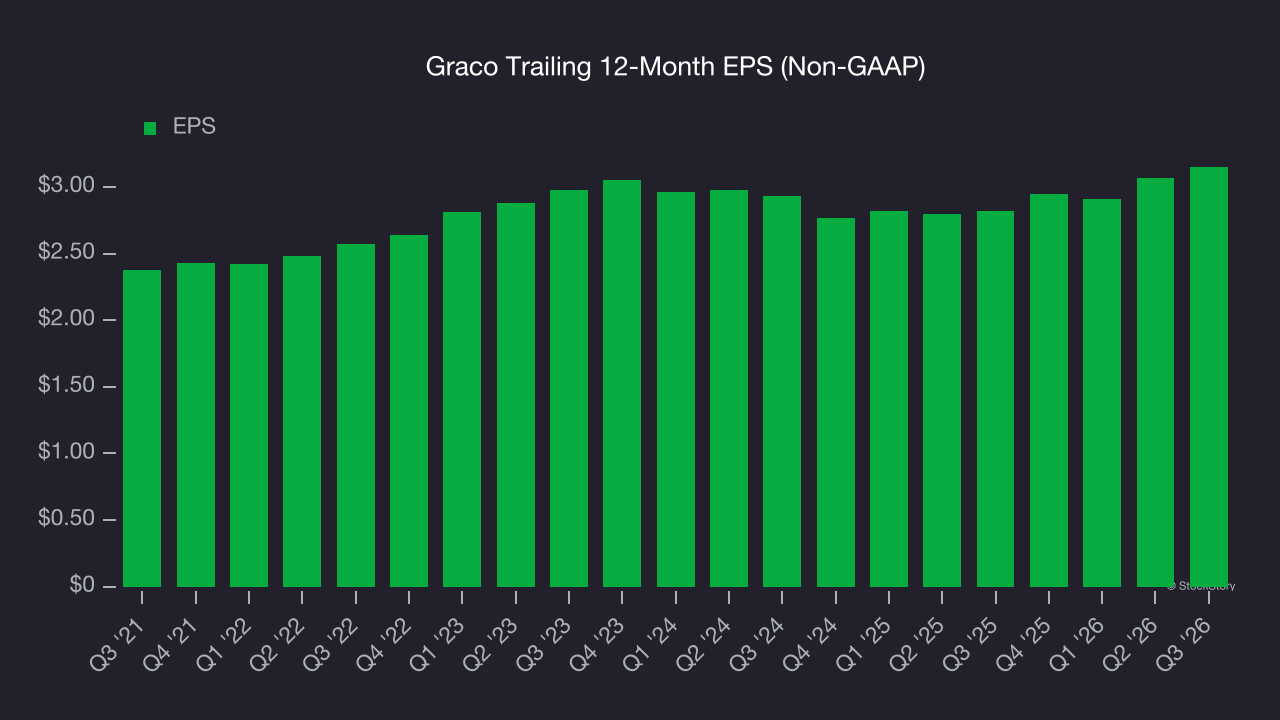
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Graco, its two-year annual EPS growth of 3.7% was lower than its five-year trend. We hope its growth can accelerate in the future.
In Q3, Graco reported adjusted EPS of $0.81, up from $0.73 in the same quarter last year. Despite growing year on year, this print missed analysts’ estimates. Over the next 12 months, Wall Street expects Graco’s full-year EPS to grow 11.8% from $3.15 to $3.52.
Key takeaways from Graco’s Q3 results
We struggled to find many positives in these results. Its revenue guidance for next quarter missed and its EPS fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock traded down 6.8% to $76.26 immediately following the results.
Graco’s earnings report left more to be desired. Let’s look forward to see if this quarter has created an opportunity to buy the stock. We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).