What a time it’s been for agilon health. In the past six months alone, the company’s stock price has increased by a massive 275%, reaching $91.76 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now still a good time to buy AGL? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why Does agilon health Spark Debate?
Transforming how doctors care for seniors by shifting financial incentives from volume to outcomes, agilon health (NYSE: AGL) provides a platform that helps primary care physicians transition to value-based care models for Medicare patients through long-term partnerships and global capitation arrangements.
Two Positive Attributes:
1. Skyrocketing Revenue Shows Strong Momentum
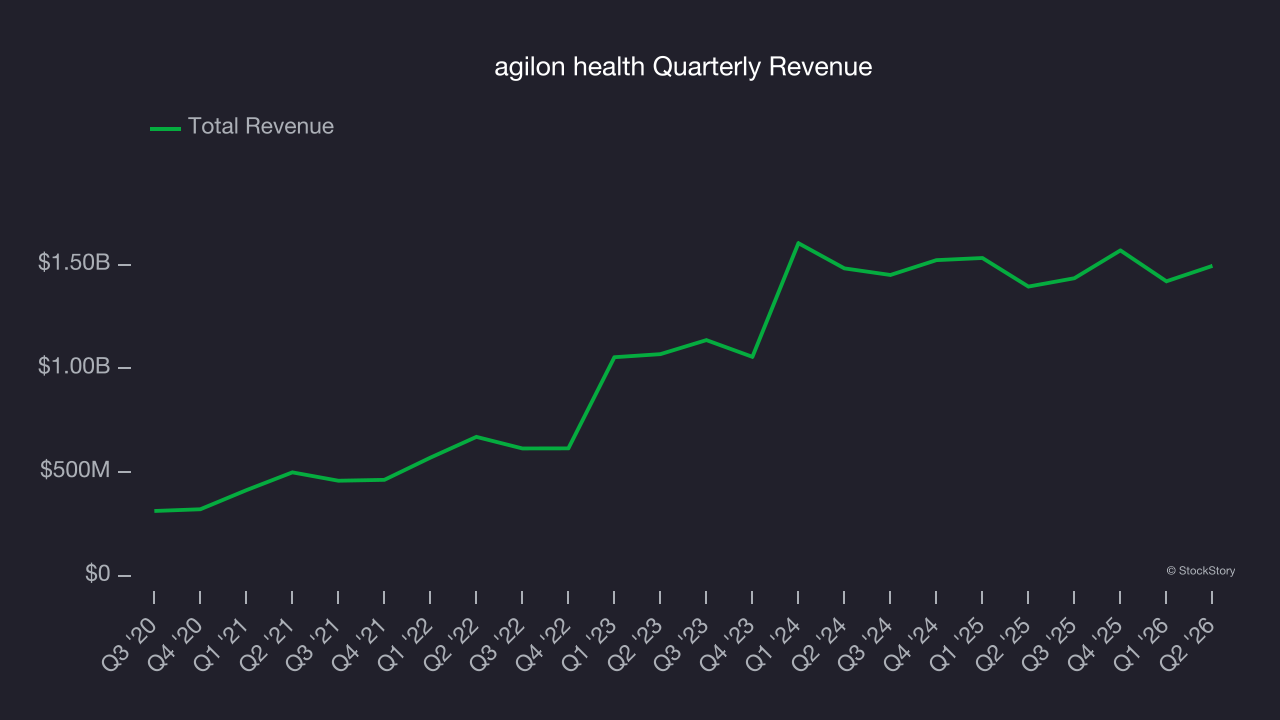
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Luckily, agilon health’s sales grew at an incredible 30.8% compounded annual growth rate over the last five years. Its growth beat the average healthcare company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
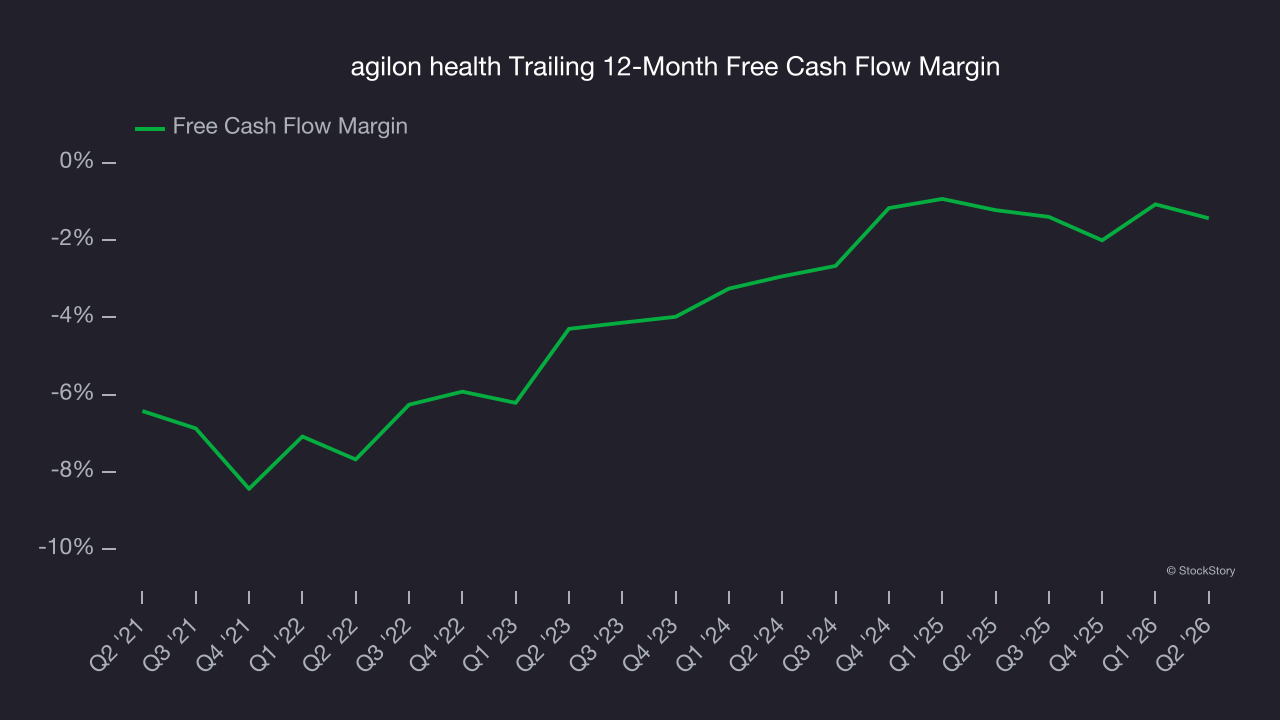
As you can see below, agilon health’s margin expanded by 6.2 percentage points over the last five years. agilon health’s free cash flow margin for the trailing 12 months was negative 1.4%, and continued increases could help it achieve long-term cash profitability.
One Reason to Be Careful:
Declining Customer Base Reflects Product and Sales Weakness
Revenue growth can be broken down into the number of customers and the average spend per customer. Both are important because an increasing customer base leads to more upselling opportunities while the revenue per customer shows how successful a company was in executing its upselling strategy.
agilon health’s total customers came in at 549,000 in the latest quarter, and over the last two years, their count averaged 3.1% year-on-year declines. This performance was underwhelming and shows the company lost deals and renewals. It also suggests there may be increasing competition or market saturation. 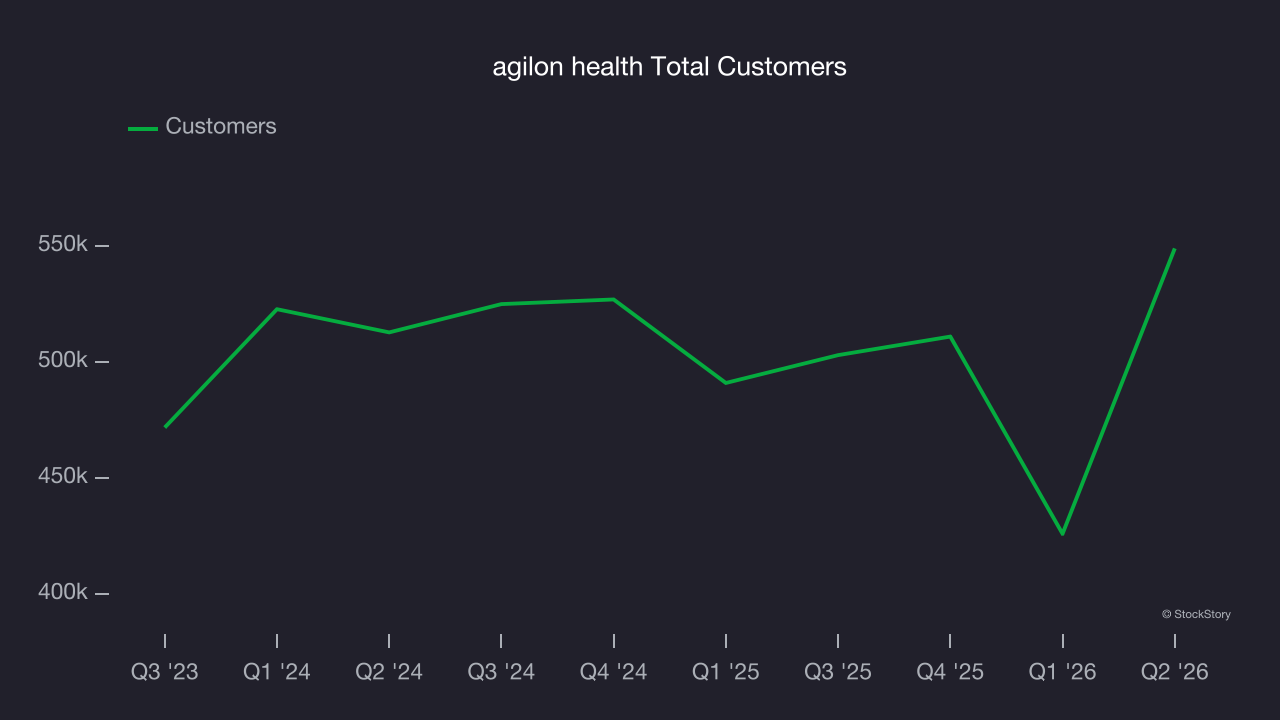
Final Judgment
agilon health’s merits more than compensate for its flaws, and with the recent surge, the stock trades at 54.6× forward P/E (or $91.76 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than agilon health
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.