Financial services giant U.S. Bancorp (NYSE: USB) met Wall Street’s revenue expectations in Q3 2026, with sales up 8.6% year on year to $7.97 billion. Its GAAP profit of $1.34 per share was 1.7% above analysts’ consensus estimates.
Is now the time to buy U.S. Bancorp? Find out by accessing our full research report, it’s free.
U.S. Bancorp (USB) Q3 2026 Highlights:
- Net Interest Income: $4.47 billion vs analyst estimates of $4.49 billion (5.1% year-on-year growth, in line)
- Net Interest Margin: 2.8% vs analyst estimates of 2.8% (2.4 basis point beat)
- Revenue: $7.97 billion vs analyst estimates of $8.01 billion (8.6% year-on-year growth, in line)
- Efficiency Ratio: 55.9% vs analyst estimates of 56.4% (54.8 basis point beat)
- EPS (GAAP): $1.34 vs analyst estimates of $1.32 (1.7% beat)
- Tangible Book Value per Share: $29.34 vs analyst estimates of $30.37 (8.6% year-on-year growth, 3.4% miss)
- Market Capitalization: $87.66 billion
Company Overview
With roots dating back to 1863 and a presence across 26 states primarily in the Midwest and West, U.S. Bancorp (NYSE: USB) is one of America's largest banks providing lending, deposit services, wealth management, payment processing, and merchant services to individuals and businesses.
Sales Growth
In general, banks make money from two primary sources. The first is net interest income, which is interest earned on loans, mortgages, and investments in securities minus interest paid out on deposits. The second source is non-interest income, which can come from bank account, credit card, wealth management, investment banking, and trading fees. Over the last five years, U.S. Bancorp grew its revenue at a sluggish 6% compounded annual growth rate. This was below our standard for the banking sector and is a tough starting point for our analysis.
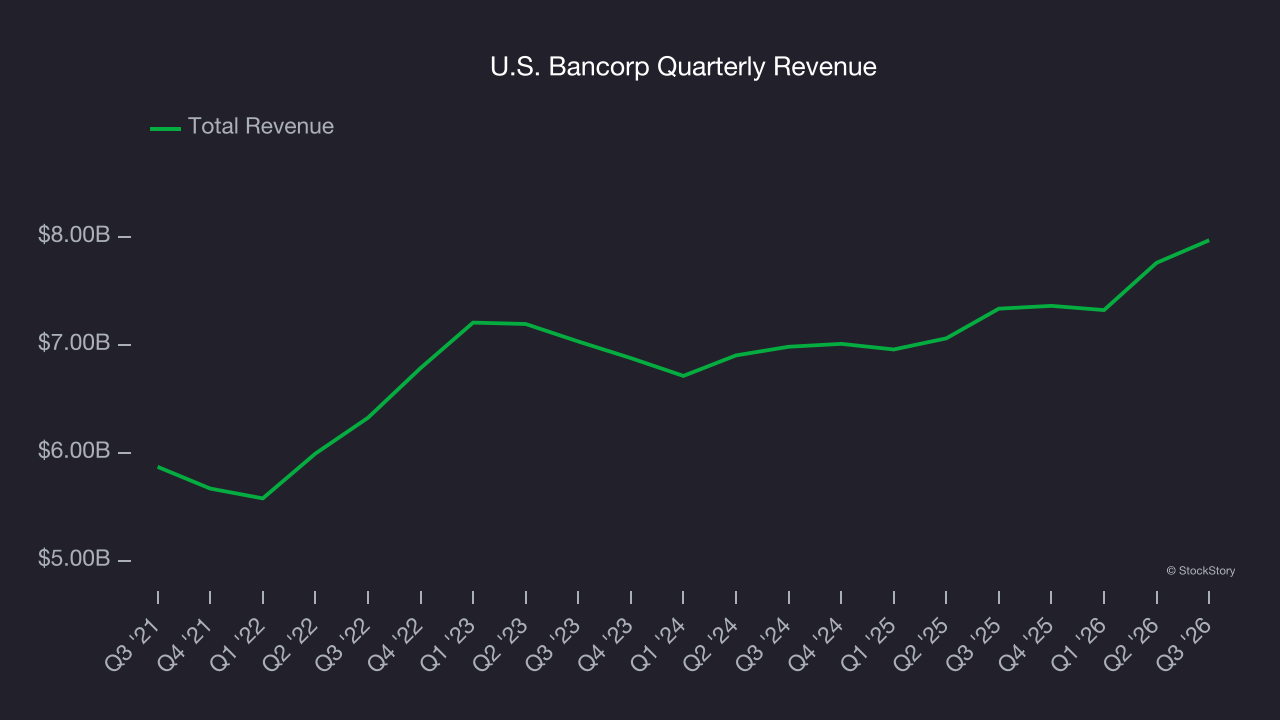
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. U.S. Bancorp’s annualized revenue growth of 5.2% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 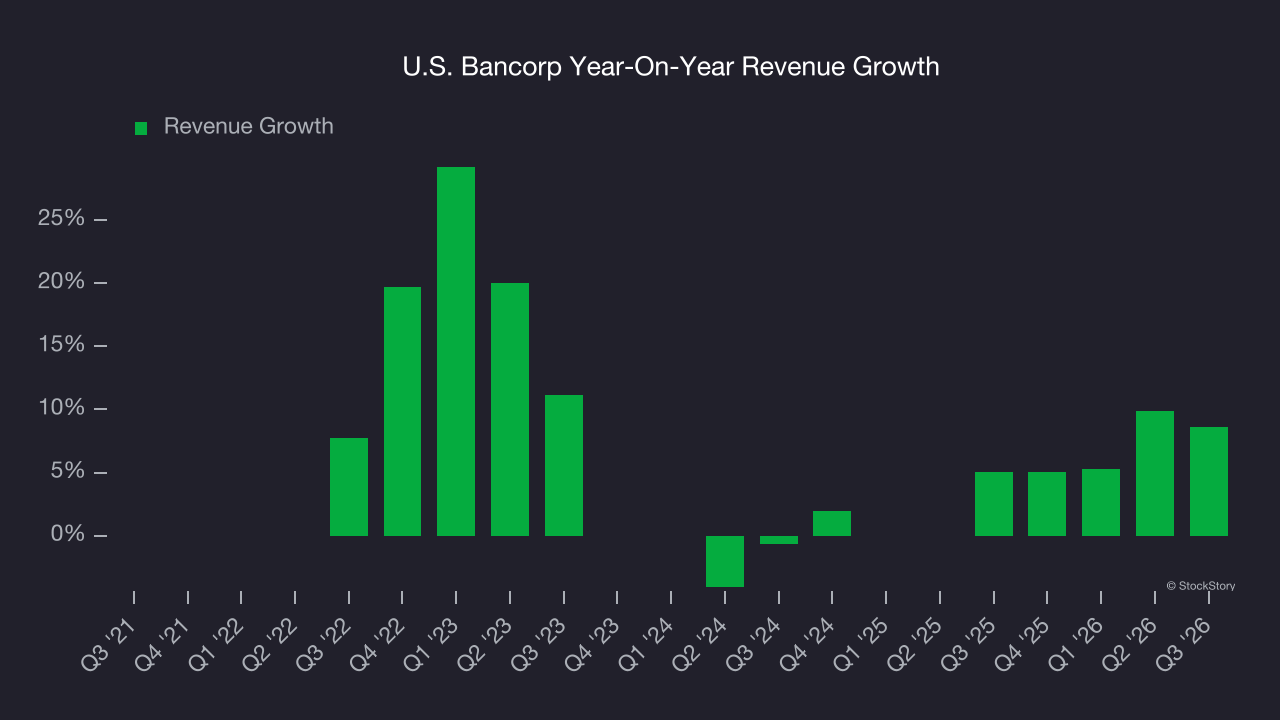 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, U.S. Bancorp grew its revenue by 8.6% year on year, and its $7.97 billion of revenue was in line with Wall Street’s estimates.
Net interest income made up 58.9% of the company’s total revenue during the last five years, meaning U.S. Bancorp’s growth drivers strike a balance between lending and non-lending activities.
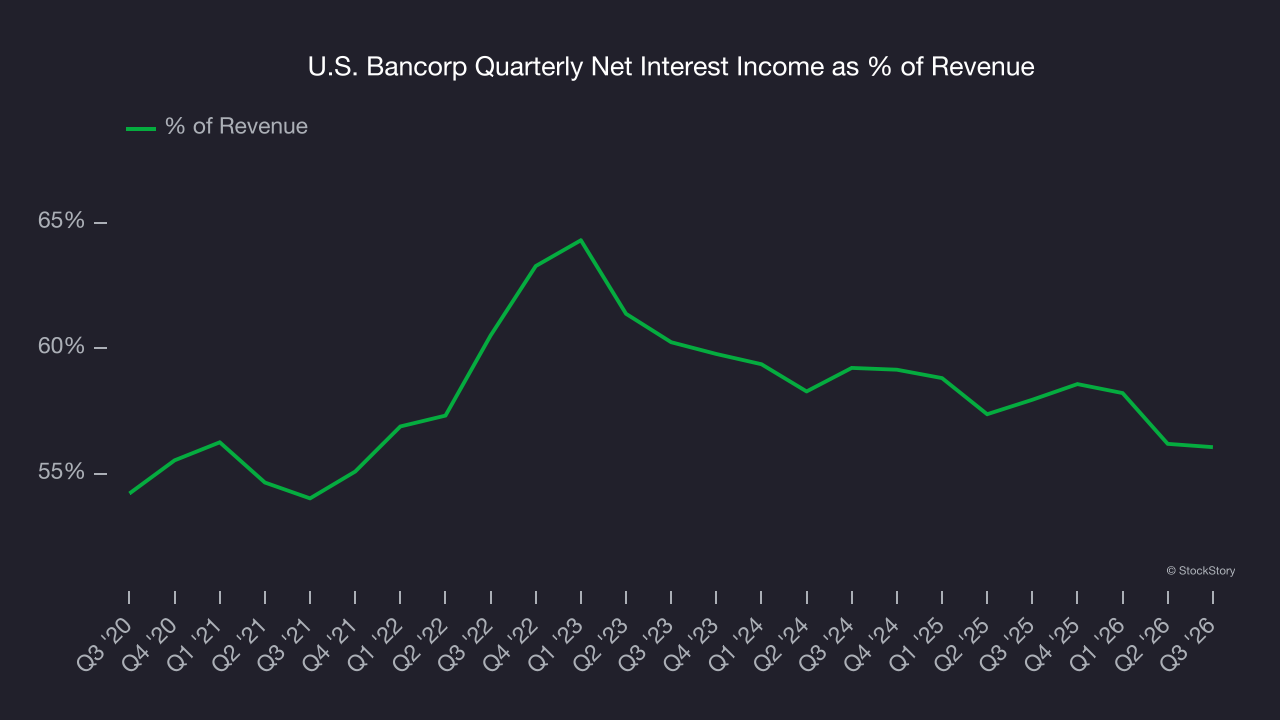
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Tangible Book Value Per Share (TBVPS)
Banks operate as balance sheet businesses, with profits generated through borrowing and lending activities. Valuations reflect this reality, emphasizing balance sheet strength and long-term book value compounding ability.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value by removing intangible assets of debatable liquidation worth. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
U.S. Bancorp’s TBVPS grew at a tepid 3.2% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 11% annually over the last two years from $23.82 to $29.34 per share.
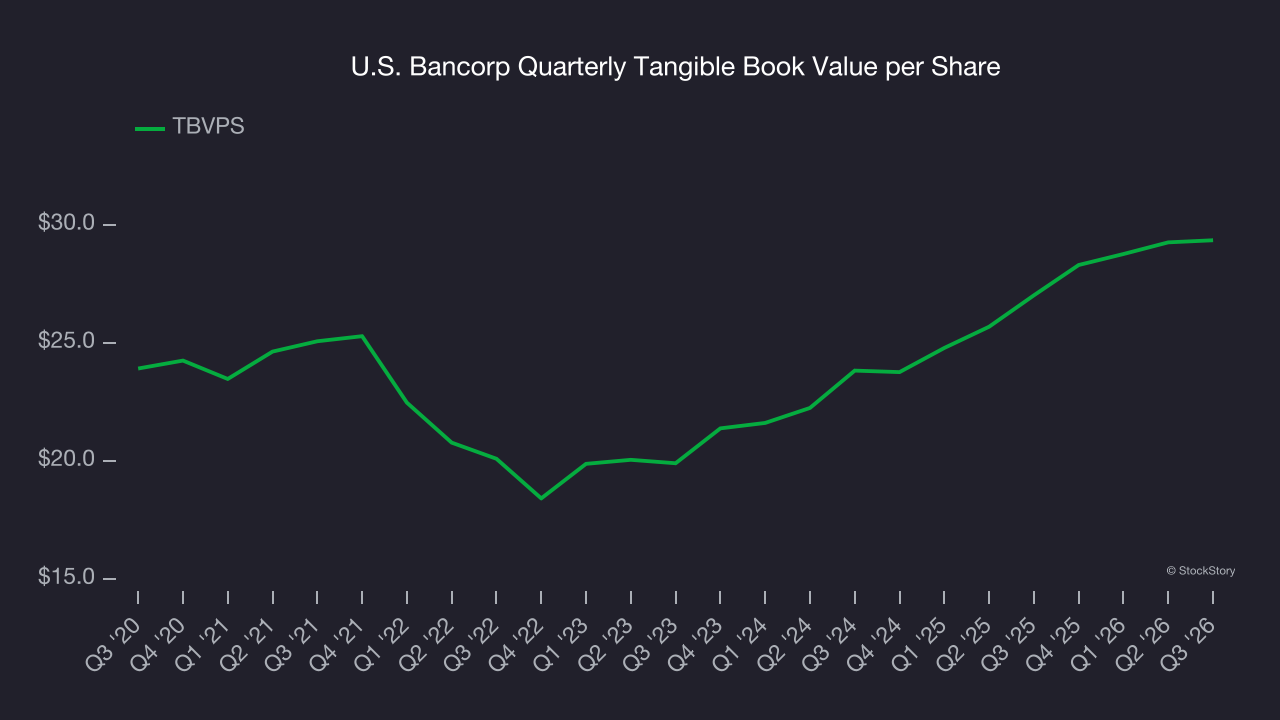
Over the next 12 months, Consensus estimates call for U.S. Bancorp’s TBVPS to grow by 14.8% to $33.69, decent growth rate.
Key Takeaways from U.S. Bancorp’s Q3 Results
U.S. Bancorp's tangible book value per share missed but its EPS slightly exceeded Wall Street’s estimates. Overall, this was a mixed quarter. The stock remained flat at $56.29 immediately following the results.
Is U.S. Bancorp an attractive investment opportunity right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).