Over the last six months, Saia’s shares have sunk to $334.81, producing a disappointing 17.2% loss - a stark contrast to the S&P 500’s 12% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Saia, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Saia Not Exciting?
Even with the cheaper entry price, we’re cautious about Saia. Here are three reasons why SAIA doesn’t excite us, plus one stock we’d rather own.
1. Weak Sales Volumes Indicate Waning Demand
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Ground Transportation company because there’s a ceiling to what customers will pay.
Saia’s tons shipped came in at 1.71 million in the latest quarter, and over the last two years, averaged 2.6% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 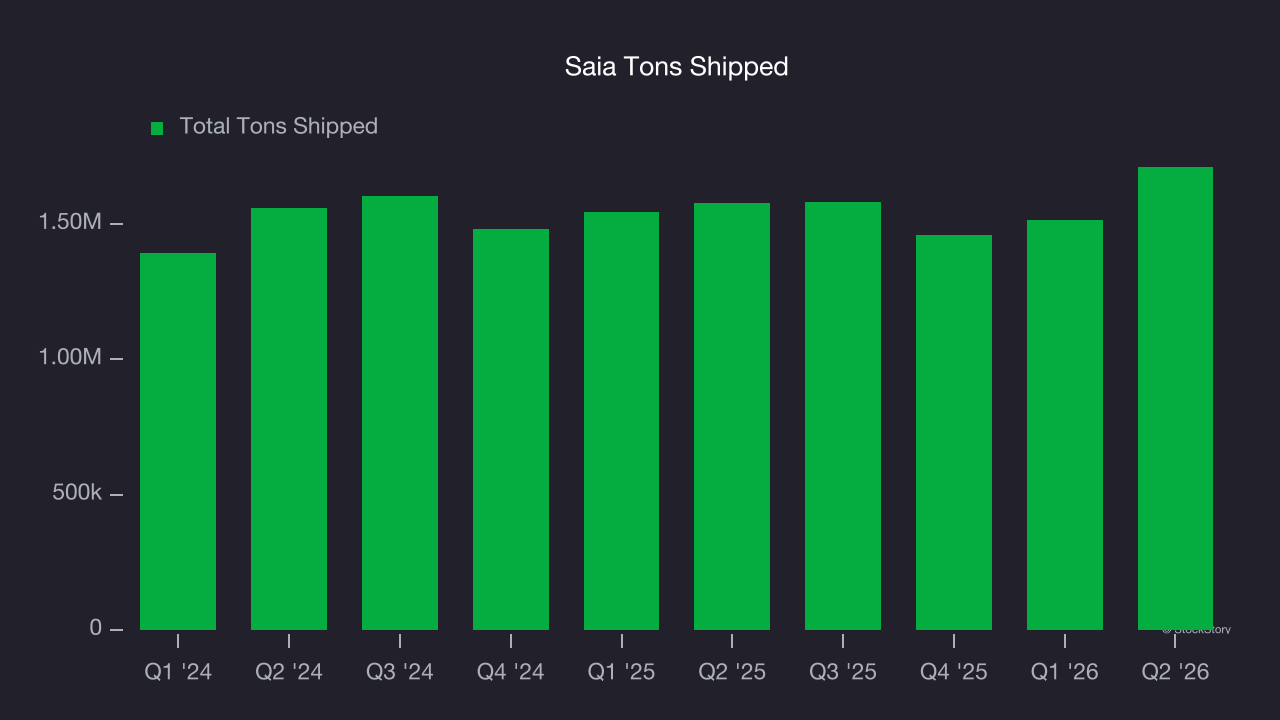
2. EPS Barely Growing
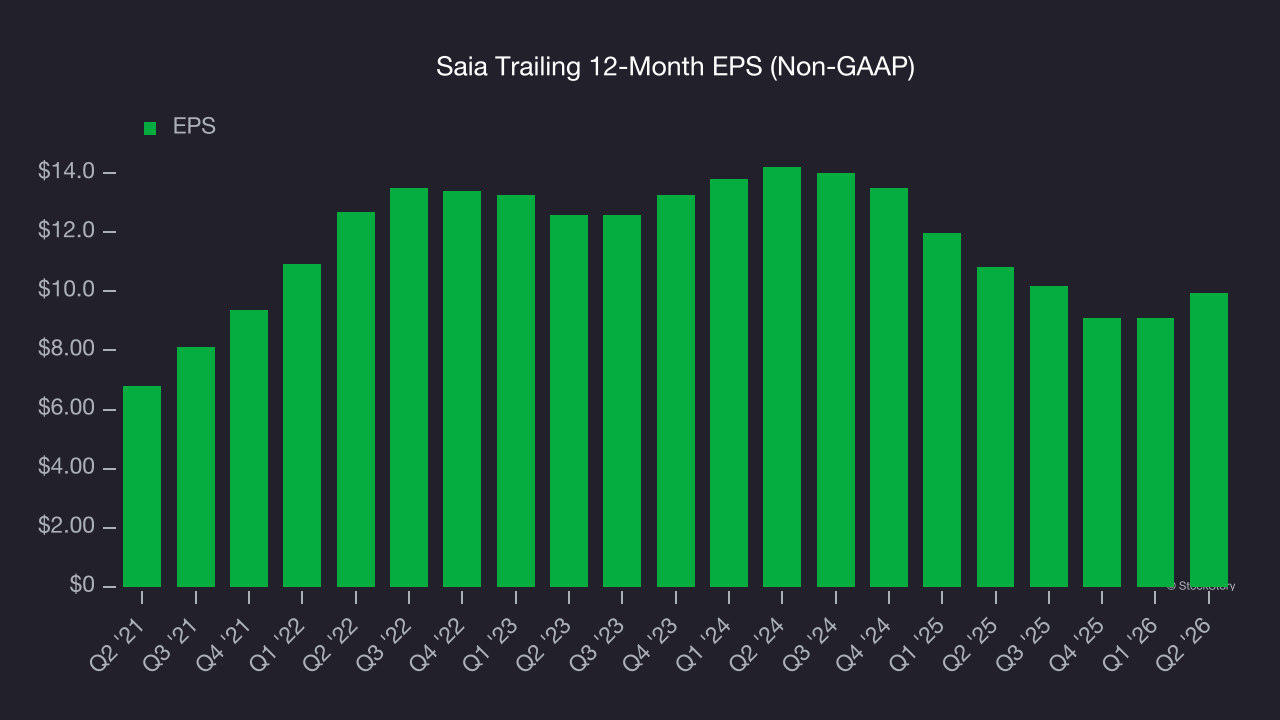
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Saia’s EPS grew at an unimpressive 7.9% compounded annual growth rate over the last five years, lower than its 11% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
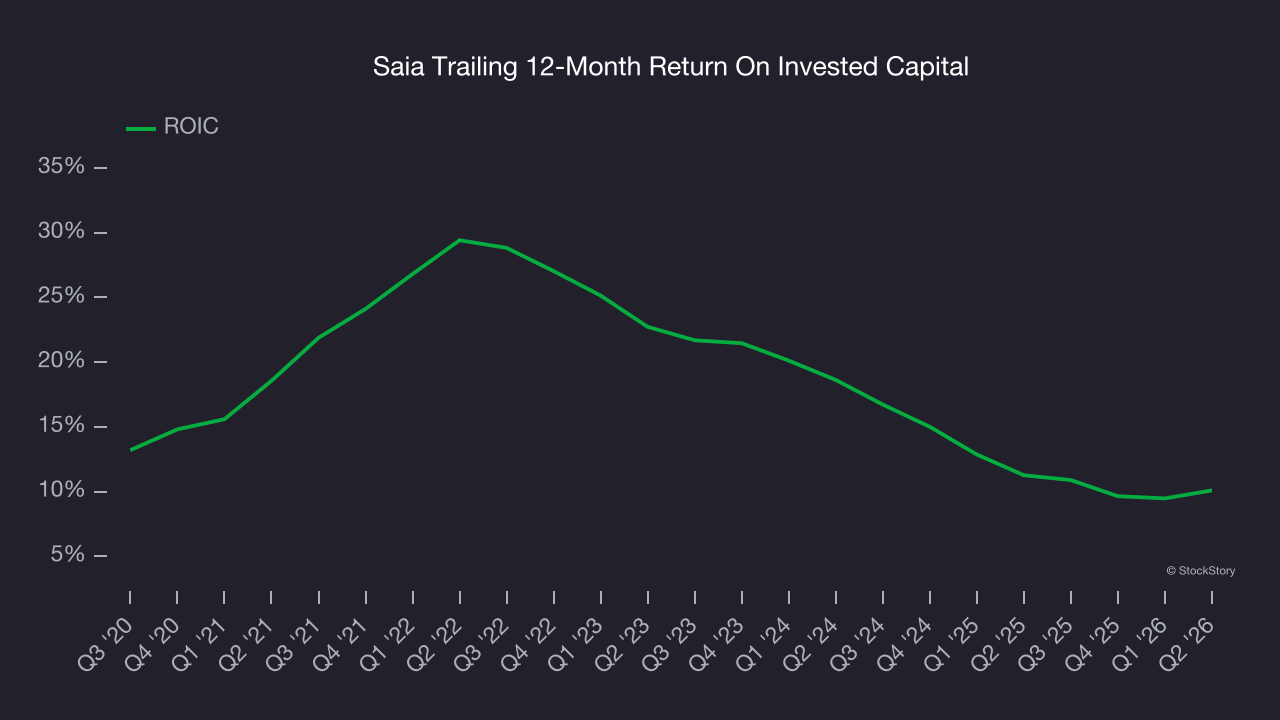
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, Saia’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Saia isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 26.2× forward P/E (or $334.81 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. Let us point you toward the most dominant software business in the world.
Stocks We Would Buy Instead of Saia
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.