

Marketing technology company Zeta Global (NYSE: ZETA) announced better-than-expected revenue in Q3 2026, with revenue up 46.1% year on year to $492.7 million. Revenue guidance for next quarter was $523 million at the midpoint, 2.4% above analysts’ consensus estimates. Its GAAP profit of $0.14 per share was significantly above analysts’ consensus estimates.
For more on Zeta Global, read our full research report for free.
Zeta Global (ZETA) Q3 2026 highlights:
- Revenue $492.7 million vs analysts' consensus estimates of $471.2 million, according to S&P (46.1% year-on-year growth, 4.6% beat)
- EPS (GAAP) $0.14 vs analysts' consensus estimates of $0.05 (significant beat)
- Adjusted EBITDA $121 million vs analysts' consensus estimates of $115.6 million (24.6% margin, 4.7% beat)
- Revenue guidance $523 million at the midpoint for Q4 2026, above analysts' consensus estimates of $510.6 million
- EBITDA guidance $414.7 million at the midpoint for the full year, above analysts' consensus estimates of $405.5 million
- Operating margin 9.3%, up from 2.6% in the same quarter last year
- Free cash flow margin 16.5%, up from 13.1% in the previous quarter
- Billings $498.9 million at quarter end, up 47.9% year on year
- Market capitalization $7.79 billion
“Delivering 46% revenue growth and achieving the rule of 71 demonstrate the strength and demand for Zeta’s intelligent AI infrastructure,” said David A. Steinberg, co-founder, chairman and CEO of Zeta. “With AthenaOS and our expanding partnership ecosystem, we are extending our proprietary data and native AI into a broader enterprise intelligence opportunity. We have the free cash flow to fund this next chapter and believe our opportunity is greater than ever.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Zeta Global grew its revenue at a strong 31.6% compounded annual growth rate. Its growth beat the average software company and shows its offerings resonate with customers.
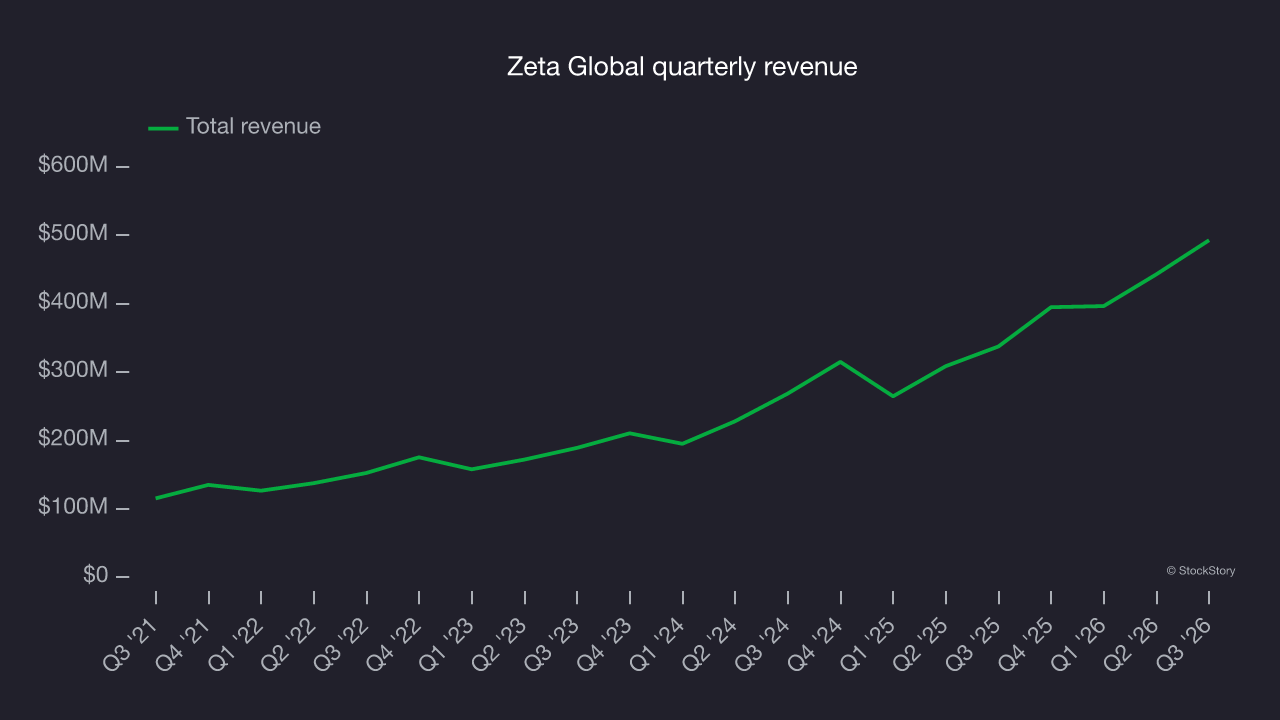
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Zeta Global’s annualized revenue growth of 38.4% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 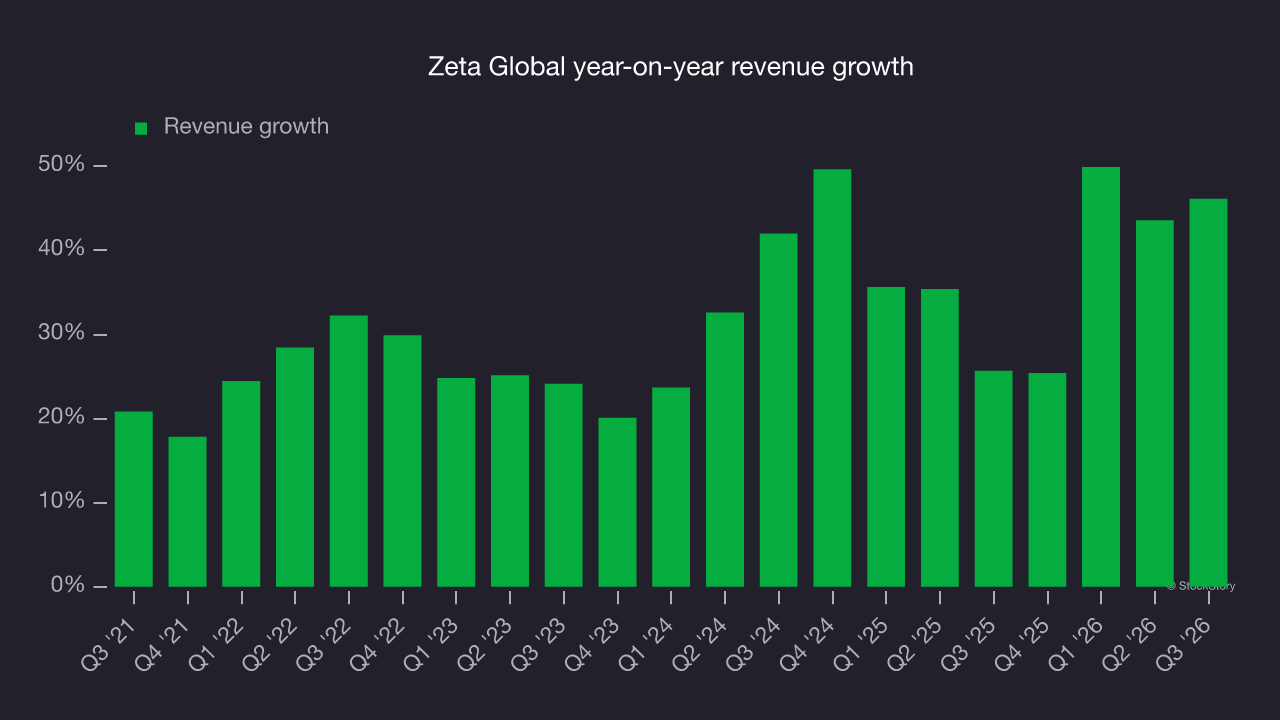
This quarter, Zeta Global reported rapid year-on-year revenue growth of 46.1%, and its $492.7 million of revenue beat Wall Street’s consensus estimates by 4.6%. Company management is guiding for a 32.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 17.8% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, that would still be a strong pace of growth, implying the market sees success for its products and services.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Zeta Global’s billings totaled $498.9 million in Q3, and over the last four quarters, growth was strong, averaging 44.2% year on year. This alternative top-line metric grew faster than total revenue, meaning the company collects cash upfront and then recognizes the revenue over the length of its contracts, supporting its liquidity and future revenue prospects. 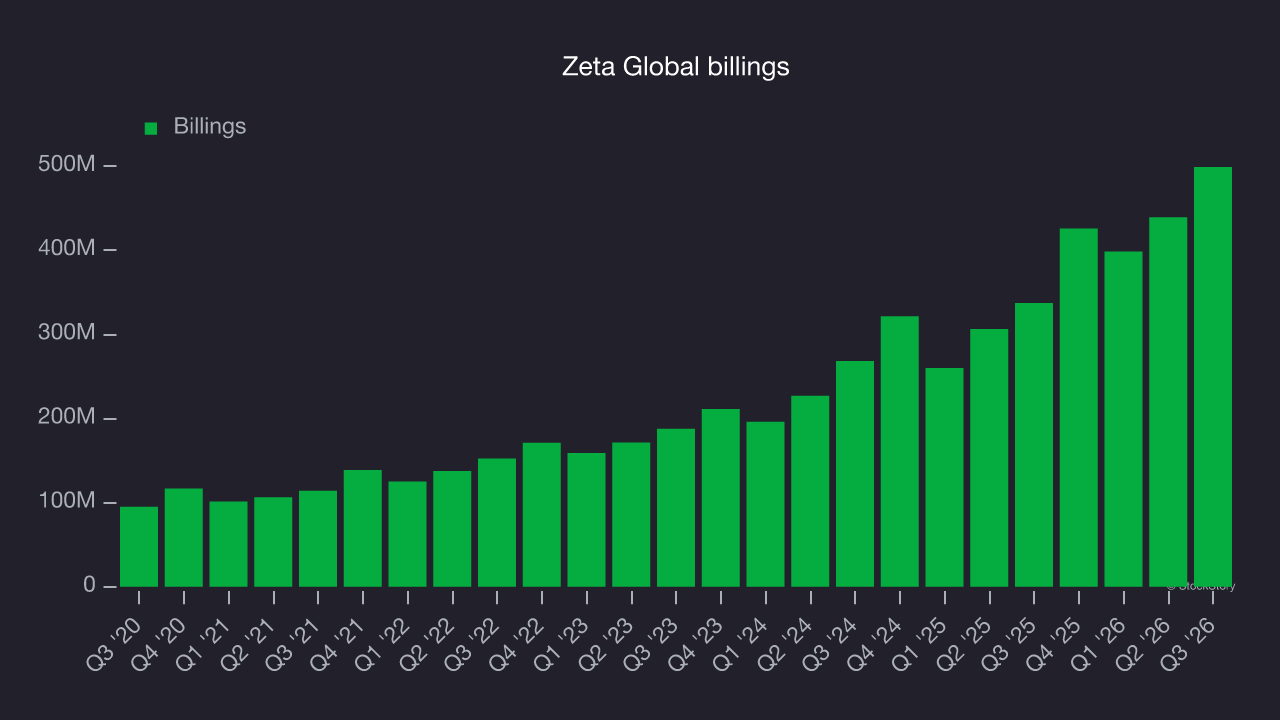
Customer acquisition efficiency
The customer acquisition cost, or CAC, payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
It’s relatively expensive for Zeta Global to acquire new customers as its CAC payback period was 78.2 months this quarter. The company’s slow recovery of its sales and marketing expenses indicates it operates in a highly competitive market and must invest to stand out, even if the return on that investment is low.
Key takeaways from Zeta Global’s Q3 results
Billings were a highlight of Zeta Global’s Q3 results, coming in well ahead of analysts’ consensus estimates, and full-year EBITDA guidance also topped Wall Street’s consensus. Those were key positives in a good quarter, but the market seemed to be hoping for more. Shares edged lower 1.1% to $32.34 immediately after the report.
Is Zeta Global a buy at its current price? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on those factors, read our full research report here (it’s free).




