

Telehealth company Hims & Hers Health (NYSE: HIMS) met Wall Street’s revenue expectations in Q3 2026, with revenue up 48.6% year on year to $890.4 million. On the other hand, next quarter’s revenue guidance of $885 million was less impressive, coming in 7.1% below analysts’ consensus estimates. Its GAAP loss of $0.14 per share was significantly below analysts’ consensus estimates.
For more on Hims & Hers Health, read our free full research report.
Hims & Hers Health (HIMS) Q3 2026 highlights:
- Revenue $890.4 million vs analysts' consensus estimates of $892.5 million, according to S&P (48.6% year-on-year growth, in line)
- EPS (GAAP) -$0.14 vs analysts' consensus estimates of $0.06 (significant miss)
- Adjusted EBITDA $82.39 million vs analysts' consensus estimates of $85.36 million (9.3% margin, 3.5% miss)
- Revenue guidance $885 million at the midpoint for Q4 2026, below analysts' consensus estimates of $953.1 million
- EBITDA guidance $267 million at the midpoint for the full year, below analysts' consensus estimates of $294.3 million
- Operating margin -7.4%, down from 2% in the same quarter last year
- Free cash flow margin 2.9%, down from 13.2% in the same quarter last year
- Customers 2.79 million, down from 2.89 million in the previous quarter
- Market capitalization $6.07 billion
“In healthcare, whoever owns the customer relationship wins, and that’s exactly what we’re building toward at Hims & Hers. Today, customers want real choice, real value, and a care team that knows them,” said Andrew Dudum, co-founder and CEO. “Everything we’re doing, from expanding the treatments and specialties we make available, to rolling out an AI-native experience to support every customer’s care, informed by leading minds in health and science, is designed to meet that higher bar. The platform people can rely on for their health every day, in every category, and every market, is the platform that will transform the industry. We believe we are building that platform.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Hims & Hers Health’s revenue grew at a strong 65.9% compounded annual growth rate over the last five years. Its growth beat the average healthcare company and shows its offerings resonate with customers.
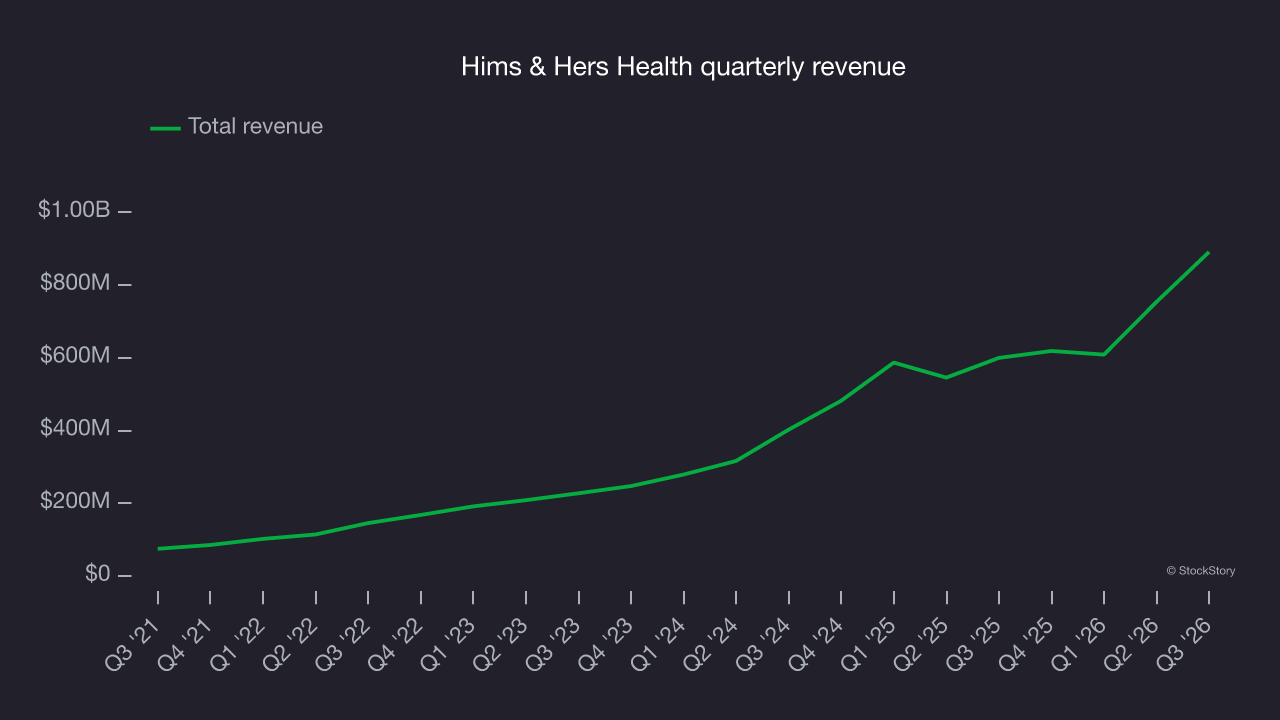
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Hims & Hers Health’s annualized revenue growth of 52% over the last two years is below its five-year trend, but the results still suggest healthy demand. 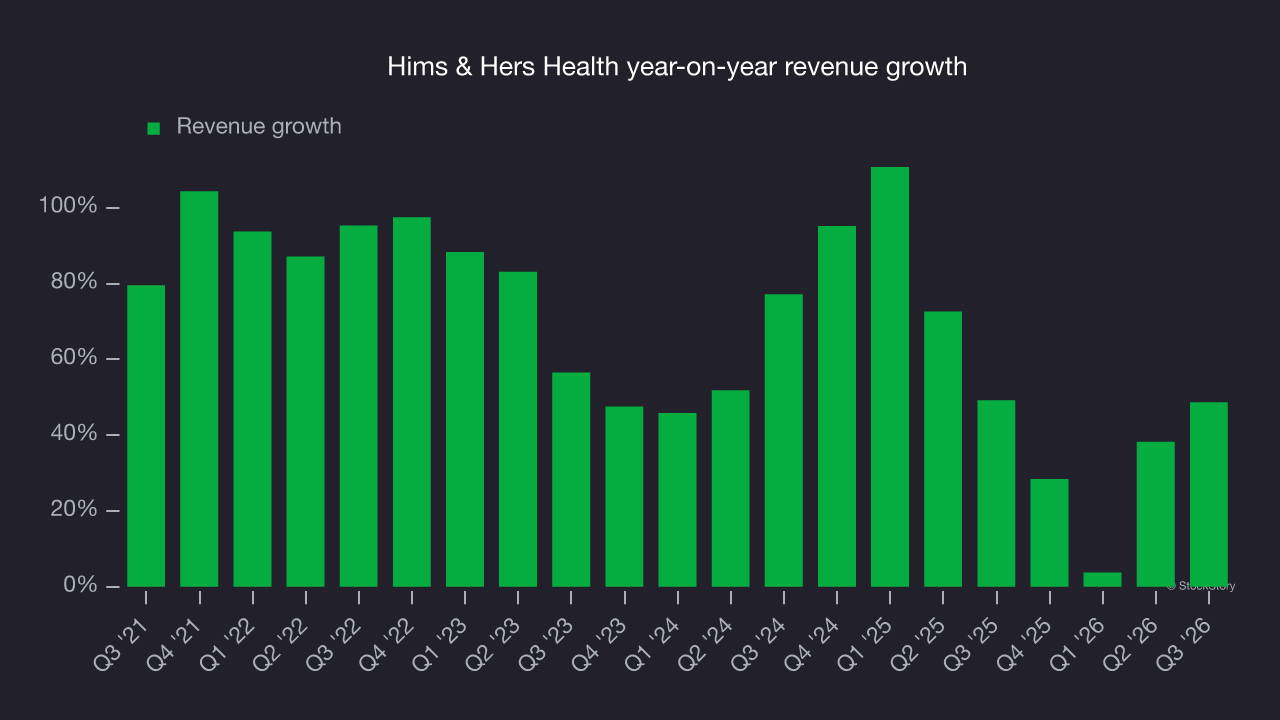
The company’s customer count, which reached 2.79 million in the latest quarter, provides more detail on its revenue dynamics. Over the last two years, Hims & Hers Health’s customer base averaged 23.5% year-on-year growth. Revenue growth outpaced customer growth, indicating that the average customer spent more each year on the company’s products and services. 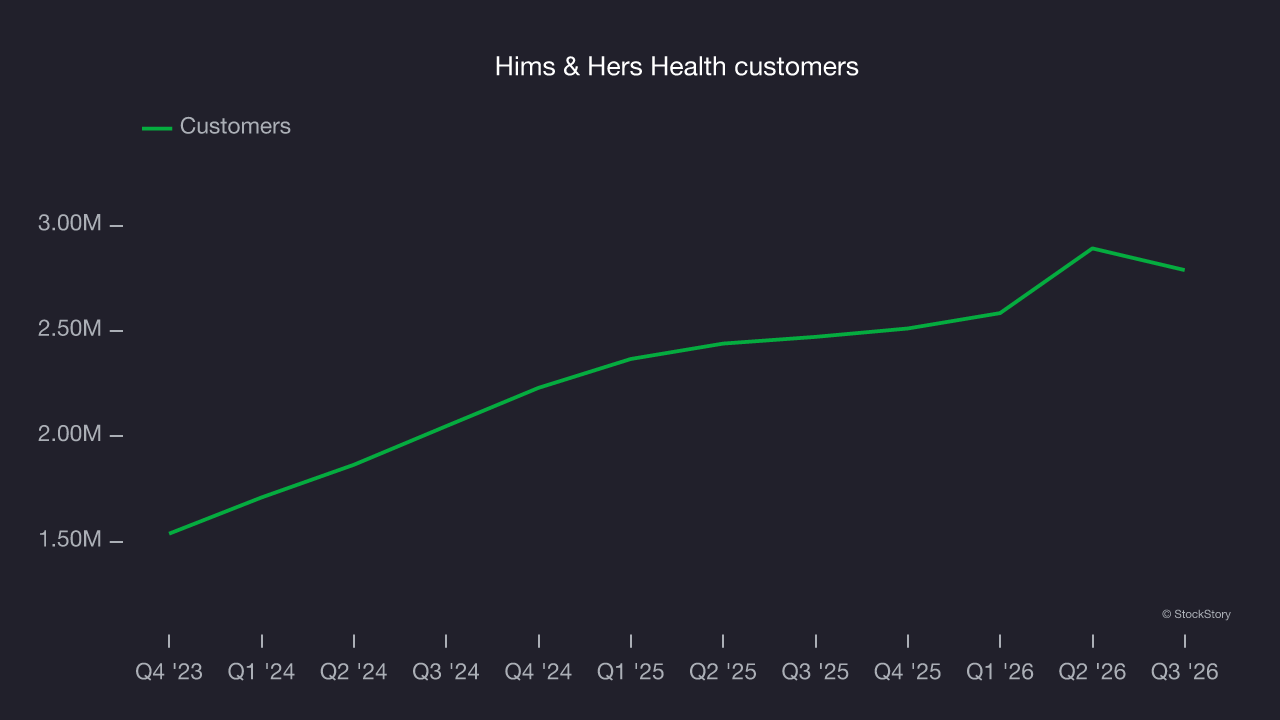
This quarter, Hims & Hers Health’s year-on-year revenue growth of 48.6% was strong, and its $890.4 million of revenue was in line with Wall Street’s consensus estimates. Management is guiding for a 43.2% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 34.8% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is substantial and implies the market expects success for its products and services.
Adjusted operating margin
Hims & Hers Health was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 5.8% was weak for a healthcare business.
On the positive side, Hims & Hers Health’s adjusted operating margin rose by 11.2 percentage points over the last five years, as its revenue growth provided operating leverage. More recently, however, the company’s margin has decreased by 7.3 percentage points over two years. Given its business quality, Hims & Hers Health should be able to correct course and return to margin expansion.
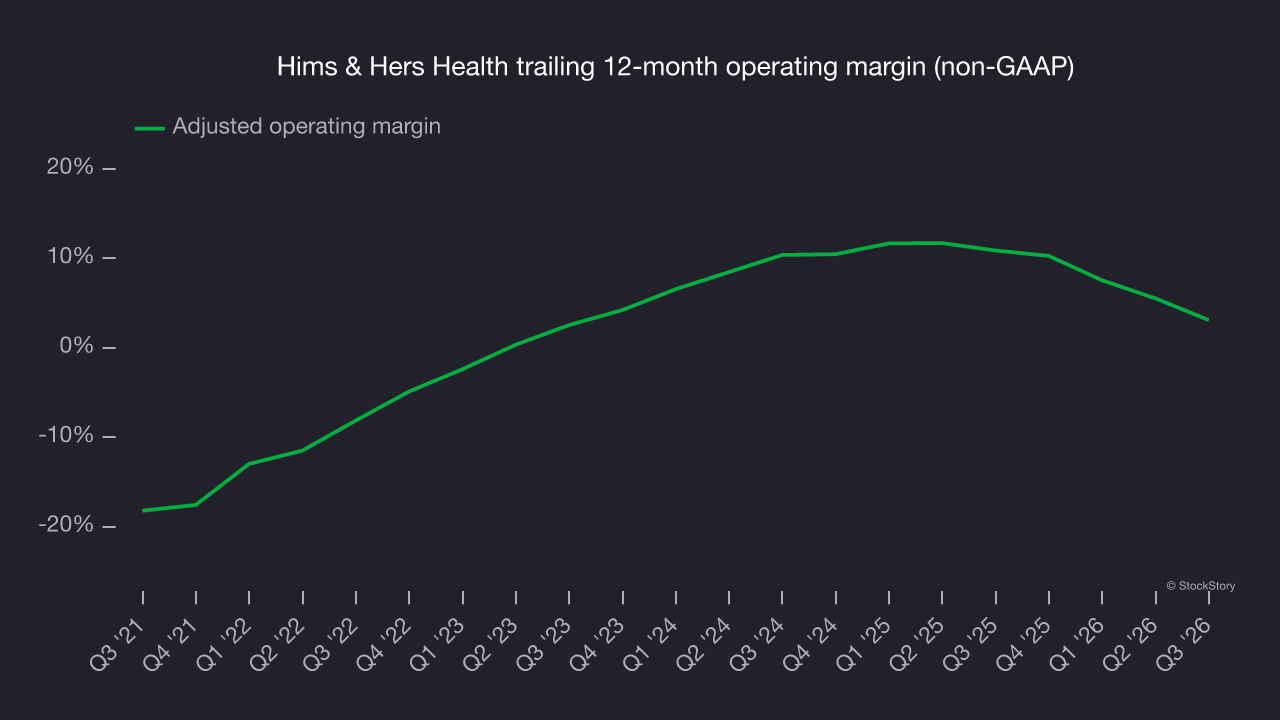
In Q3, Hims & Hers Health’s breakeven margin was -0.2%, down 8.9 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Hims & Hers Health’s losses deepened over the last five years as its EPS dropped 6.5% annually. Diminishing earnings could imply changing secular trends and preferences.
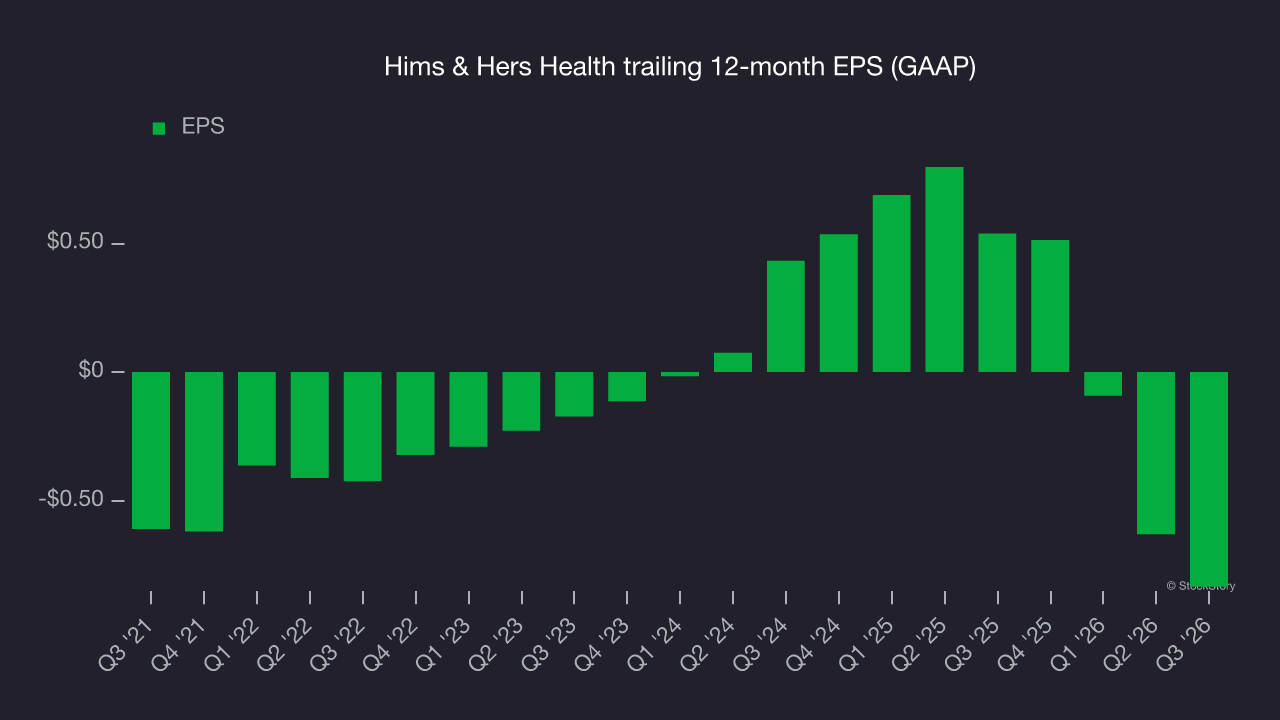
In Q3, Hims & Hers Health reported EPS of negative $0.14, down from $0.06 in the same quarter last year. This result missed analysts’ consensus estimates. Wall Street expects a return to profitability over the next 12 months, with analysts forecasting Hims & Hers Health’s full-year EPS will turn positive, from negative $0.83 to $0.54, according to S&P.
Key takeaways from Hims & Hers Health’s Q3 results
An EPS miss against Wall Street’s consensus estimates and below-consensus revenue guidance for next quarter left few positives in Hims & Hers Health’s Q3 report. It was a weaker quarter overall, and shares edged lower 1.5% to $22.68 immediately after the release.
Hims & Hers Health’s earnings report left more to be desired. To assess whether this quarter has created a buying opportunity, consider valuation, business quality and the latest earnings. Read our full research report here (it’s free).




