Temporary space provider WillScot (NASDAQ: WSC) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 6.1% year on year to $601.3 million. The company’s full-year revenue guidance of $2.34 billion at the midpoint came in 1.2% above analysts’ consensus estimates. Its non-GAAP profit of $0.29 per share was in line with analysts’ consensus estimates.
For more on WillScot Mobile Mini, read the full research report for free.
WillScot Mobile Mini (WSC) Q3 2026 highlights:
- Revenue $601.3 million vs S&P analysts’ consensus estimates of $586 million (6.1% year-on-year growth, 2.6% beat)
- Adjusted EPS $0.29 vs S&P analysts’ consensus estimates of $0.28 (in line)
- Adjusted EBITDA $233.6 million vs analysts’ consensus estimates of $232.8 million (38.8% margin, in line)
- Revenue guidance The company lifted its revenue guidance for the full year to $2.34 billion at the midpoint from $2.3 billion, a 1.7% increase
- EBITDA guidance $920 million at the midpoint for the full year, in line with analysts’ consensus expectations
- Operating margin 21%, in line with the same quarter last year
- Free cash flow margin 13%, down from 21.6% in the same quarter last year
- Market capitalization $3.50 billion
Boswell concluded, "We are supporting continued strong order activity with organic growth investments in our most highly utilized fleet categories where we see attractive returns and lease durations. These investments are strengthening our leasing revenue run-rate heading into next year, while continuing to generate strong free cash flow in the quarter. Overall, our improving run-rate, organic growth investments, and margin initiatives support mid-single digit percentage growth in Adjusted EBITDA in 2027. We believe this is a balanced initial outlook given potential risks to the pace of data center build-outs and potential upside if strength in modular activation activity continues or the demand profile broadens. We are excited about these fundamental improvements to our business trajectory and intend to execute against these opportunities on behalf of our shareholders."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. WillScot Mobile Mini’s revenue grew at a tepid 5.5% compounded annual growth rate over the last five years, falling short of the industrials sector standard.
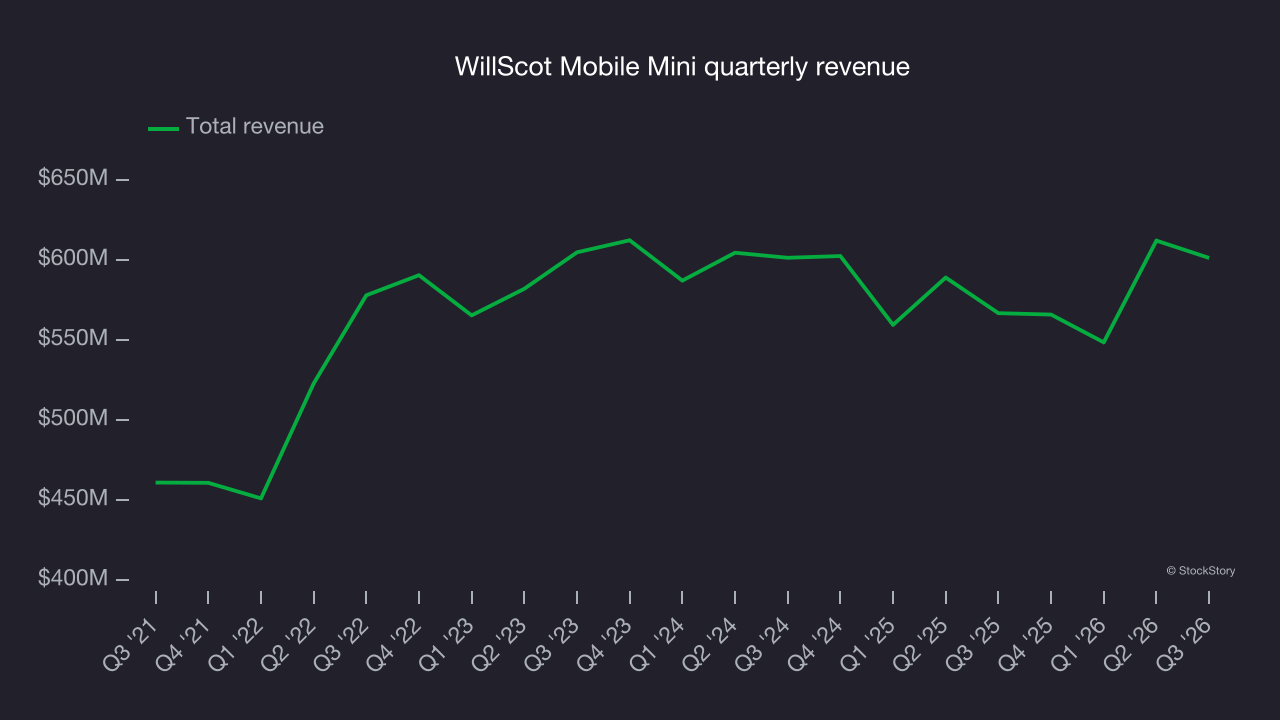
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. WillScot Mobile Mini’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 1.6% annually. 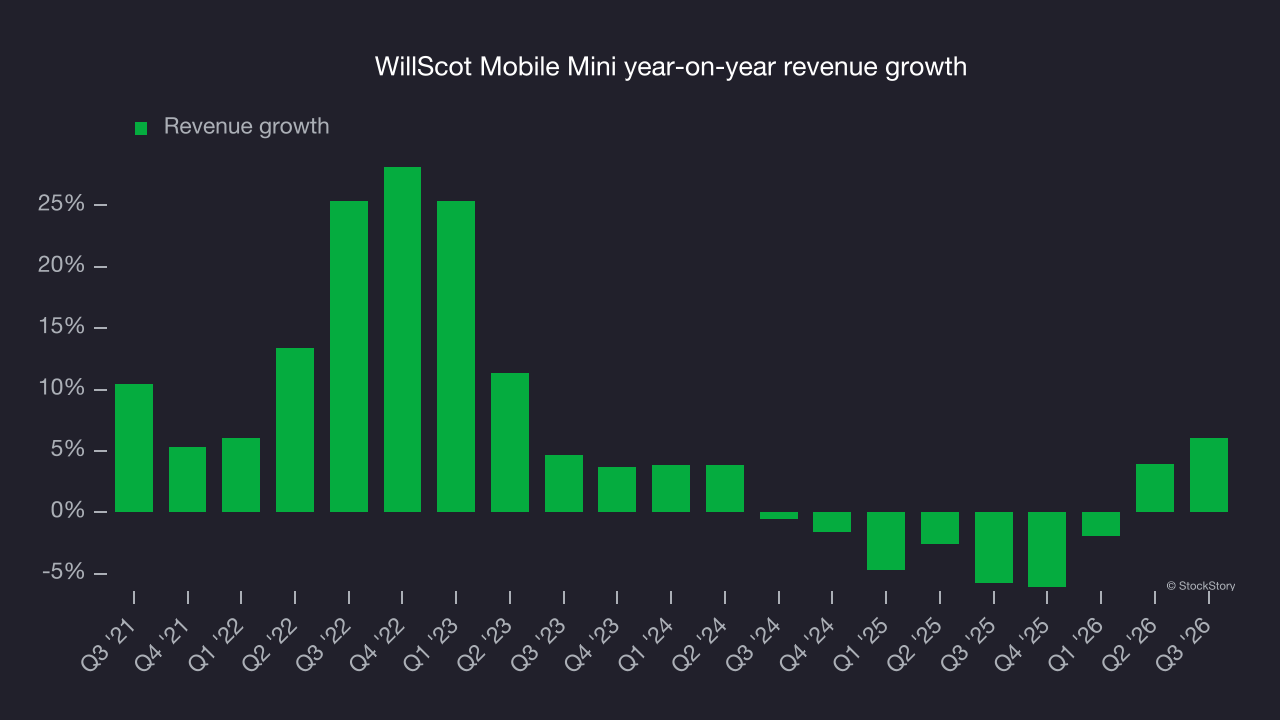
Analyzing the company’s most important segments, Leasing and Delivery and Installation, helps explain its revenue dynamics. These segments account for 75.1% and 20.1% of revenue, respectively. Over the last two years, WillScot Mobile Mini’s Leasing revenue (recurring) averaged 2.4% year-on-year declines. On the other hand, its Delivery and Installation revenue (non-recurring) averaged 3.2% growth. 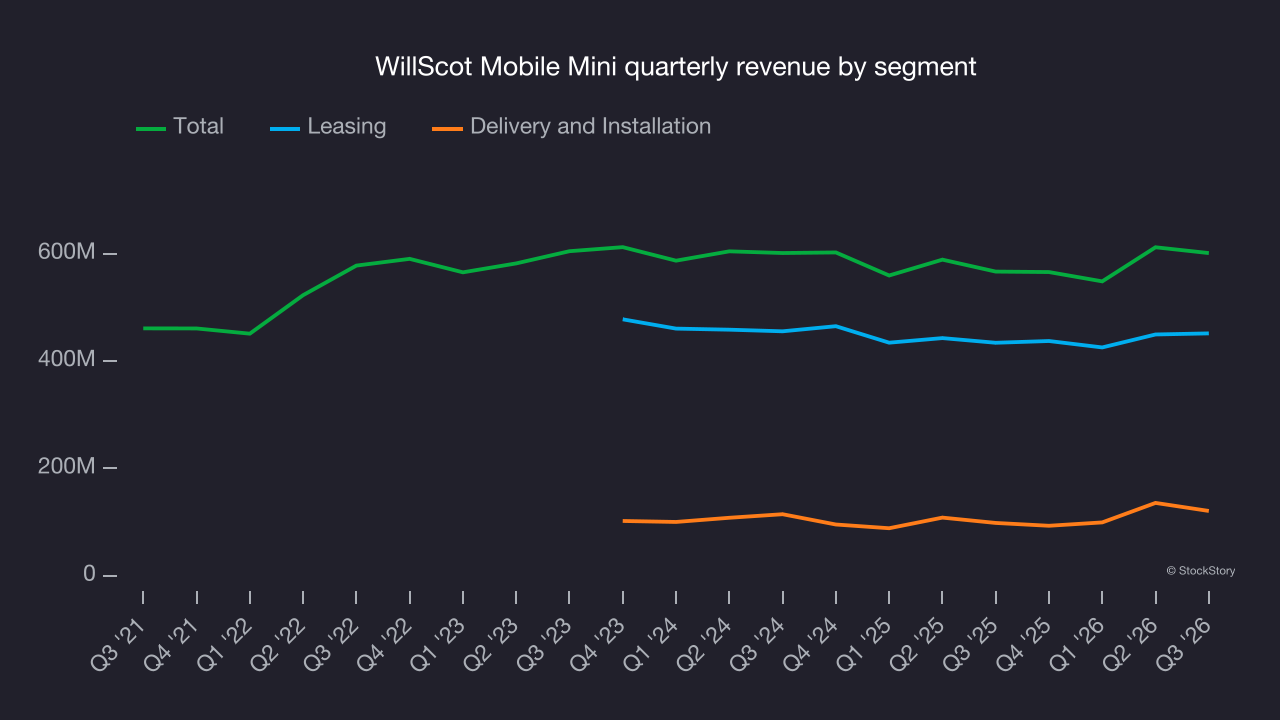
This quarter, WillScot Mobile Mini reported year-on-year revenue growth of 6.1%, and its $601.3 million of revenue exceeded Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. Although this projection suggests its newer products and services will lead to better revenue performance, it is still below average for the sector.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
WillScot Mobile Mini has performed well over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 18.2%. That outcome is unsurprising given its high gross margin baseline.
Looking at the trend in its profitability, WillScot Mobile Mini’s operating margin decreased by 15.2 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
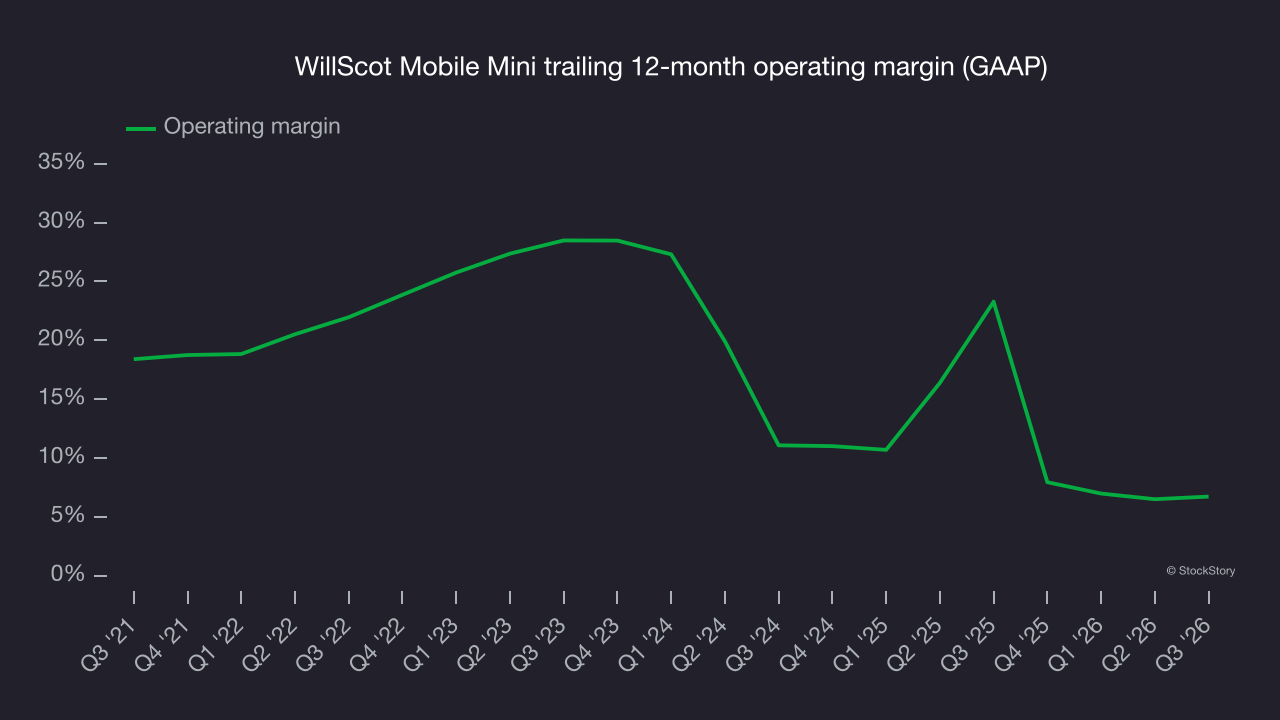
This quarter, WillScot Mobile Mini generated an operating margin of 21%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
WillScot Mobile Mini’s EPS declined by 1.8% annually over the last five years while its revenue grew by 5.5%. The difference stemmed from higher interest expenses or taxes, as the company improved its operating margin and repurchased its shares during this time.
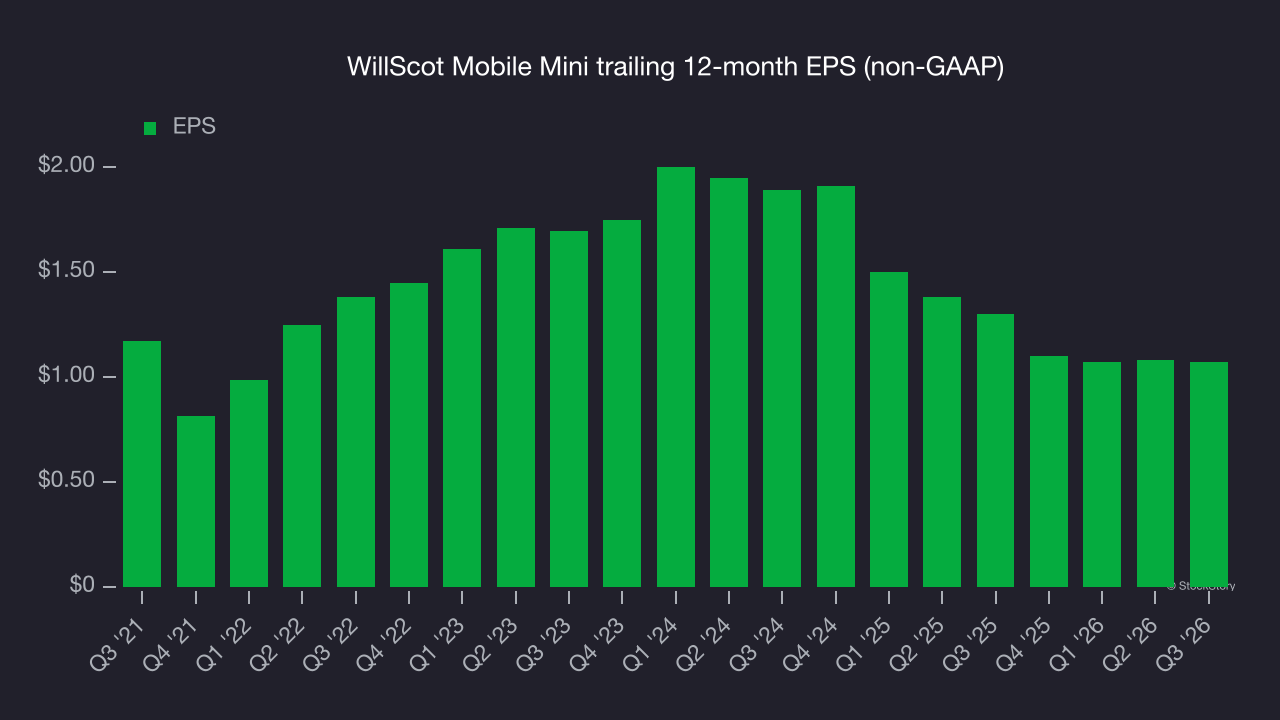
We can take a deeper look into WillScot Mobile Mini’s earnings to better understand the drivers of its performance. As we mentioned earlier, WillScot Mobile Mini’s operating margin was flat this quarter but declined by 15.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
WillScot Mobile Mini’s annual EPS declines of 24.8% over the last two years show it has continued to underperform. These results were poor.
In Q3, WillScot Mobile Mini reported adjusted EPS of $0.29, down from $0.30 in the same quarter last year. Despite falling year on year, EPS beat analysts’ consensus estimates by 2.7%. Over the next 12 months, Wall Street expects WillScot Mobile Mini’s full-year EPS to grow 13.2% from $1.07 to $1.21, according to S&P.
Key takeaways from WillScot Mobile Mini’s Q3 results
WillScot Mobile Mini’s revenue beat analysts’ consensus estimates, and its full-year revenue guidance came in slightly above Wall Street’s consensus. Those were key positives in the Q3 results. Shares remained flat at $17.83 immediately after the report.
When deciding whether to invest in WillScot Mobile Mini, the latest quarter matters, but not as much as longer-term business quality and valuation. For more, read the full research report here (it’s free).